CoinW Research Institute
Key Points
The global cryptocurrency market capitalization is $2.87 trillion, a decrease of approximately 1.71% from last week's $2.92 trillion. As of the time of writing, the US Bitcoin Spot ETF has a total net inflow of approximately $56.88 billion, with a net outflow of $228.58 million this week, and a total net asset value of $104.29 billion, down about 1.46% from last week's $105.84 billion. The US Ethereum Spot ETF has a total net inflow of approximately $12.94 billion, experiencing a net outflow of $319.97 million this week, with a total net asset value of $14.95 billion, down about 4.84% from last week's $15.71 billion.
The total market capitalization of stablecoins is $311.0 billion, an increase of about 0.03% from last week's $310.9 billion. Among them, USDT has a market capitalization of $183.44 billion, accounting for approximately 58.98% of the total market capitalization of stablecoins, down about 0.34% from last week's $184.06 billion; USDC has a market capitalization of $72.48 billion, accounting for about 23.31%, down about 0.64% from last week's $72.95 billion; DAI has a market capitalization of $4.51 billion, accounting for about 1.45%, down about 0.88% from last week's $4.55 billion.
According to data from DeFiLlama, this week's total DeFi TVL is $87.886 billion, a decrease of about 4.73% from last week's $92.253 billion. When categorized by public chains, the top three public chains in terms of TVL are Ethereum, accounting for 55.72%; Base, accounting for 6.91%; and Solana, accounting for 6.55%.
This week's performance of major public chains (Ethereum, Solana, BNB Chain, Ton, Sui, Aptos): The on-chain activity of mainstream public chains shows a significant divergence this week. BNB Chain performs the best, with daily trading volume on DEX increasing by 98.39% to $0.986 billion, daily active addresses increasing by 6.73% to 2.22 million, and TVL increasing by 1.55% to $5.690 billion, with all three indicators showing growth. Solana still ranks first with a DEX daily trading volume of $1.123 billion (+5.05%), but daily active addresses decreased by 19.65% to 2.29 million, and TVL fell 7.33% to $5.767 billion, further narrowing the gap with BNB Chain. Ethereum's DEX trading volume slightly increased by 2.46% to $0.707 billion, while TVL decreased by 3.87% to $49.482 billion, maintaining its leading capital scale. Among other public chains, Aptos's DEX trading volume increased by 50.00%, but the scale is relatively small; Sui and TON respectively saw trading volumes decrease by 41.94% and 50.00%, with user activity and TVL declining correspondingly. In terms of transaction fees, Ethereum, BNB Chain, and Aptos remained stable, while Solana, TON, and Sui gas fees decreased by 8.33%, 22.22%, and 50.00% respectively. Overall, BNB Chain's trading activity and capital accumulation improved simultaneously, while most public chains' TVL is under pressure, reflecting a divergence between on-chain capital and user activity.
New project attention: Spout Finance is a RWA collateral lending protocol based on Solana, mainly allowing users to borrow USDC by using tokenized US stocks as collateral, and covering borrowing costs through premiums generated by covered call strategies, attempting to achieve zero-interest borrowing. EFY Finance is a stablecoin payment and cross-border settlement platform for the Latin American market, mainly providing stablecoin and fiat currency exchanges, cross-border transfers, OTC, digital wallets, and enterprise payment services, helping individuals and businesses achieve cross-border fund flows through stablecoins like USDT. AIsa (marked as Alsa by RootData) is a payment and resource calling infrastructure platform for AI agents, allowing AI agents to access external APIs, AI models, and software services through a unified interface, and automatically settle based on actual usage through fiat or stablecoins.
Directory
Key Points
1. Market Overview
1. Total cryptocurrency market capitalization/Bitcoin market capitalization ratio
2. Fear Index
3. ETF inflow and outflow data
4. ETH/BTC and ETH/USD exchange rates
5. Decentralized Finance (DeFi)
6. On-chain data
7. Stablecoin market capitalization and issuance situation
2. This Week's Hot Money Trends
1. The top five VC coins and Meme coins with the largest increases this week
2. New project insights
3. Industry News
1. Major industry events this week
2. Major events happening next week
3. Important investments and financing from last week
4. Reference Links
1. Market Overview
1. Total cryptocurrency market capitalization/Bitcoin market capitalization ratio
The global total cryptocurrency market capitalization is $2.87 trillion, down about 1.71% from last week's $2.92 trillion.
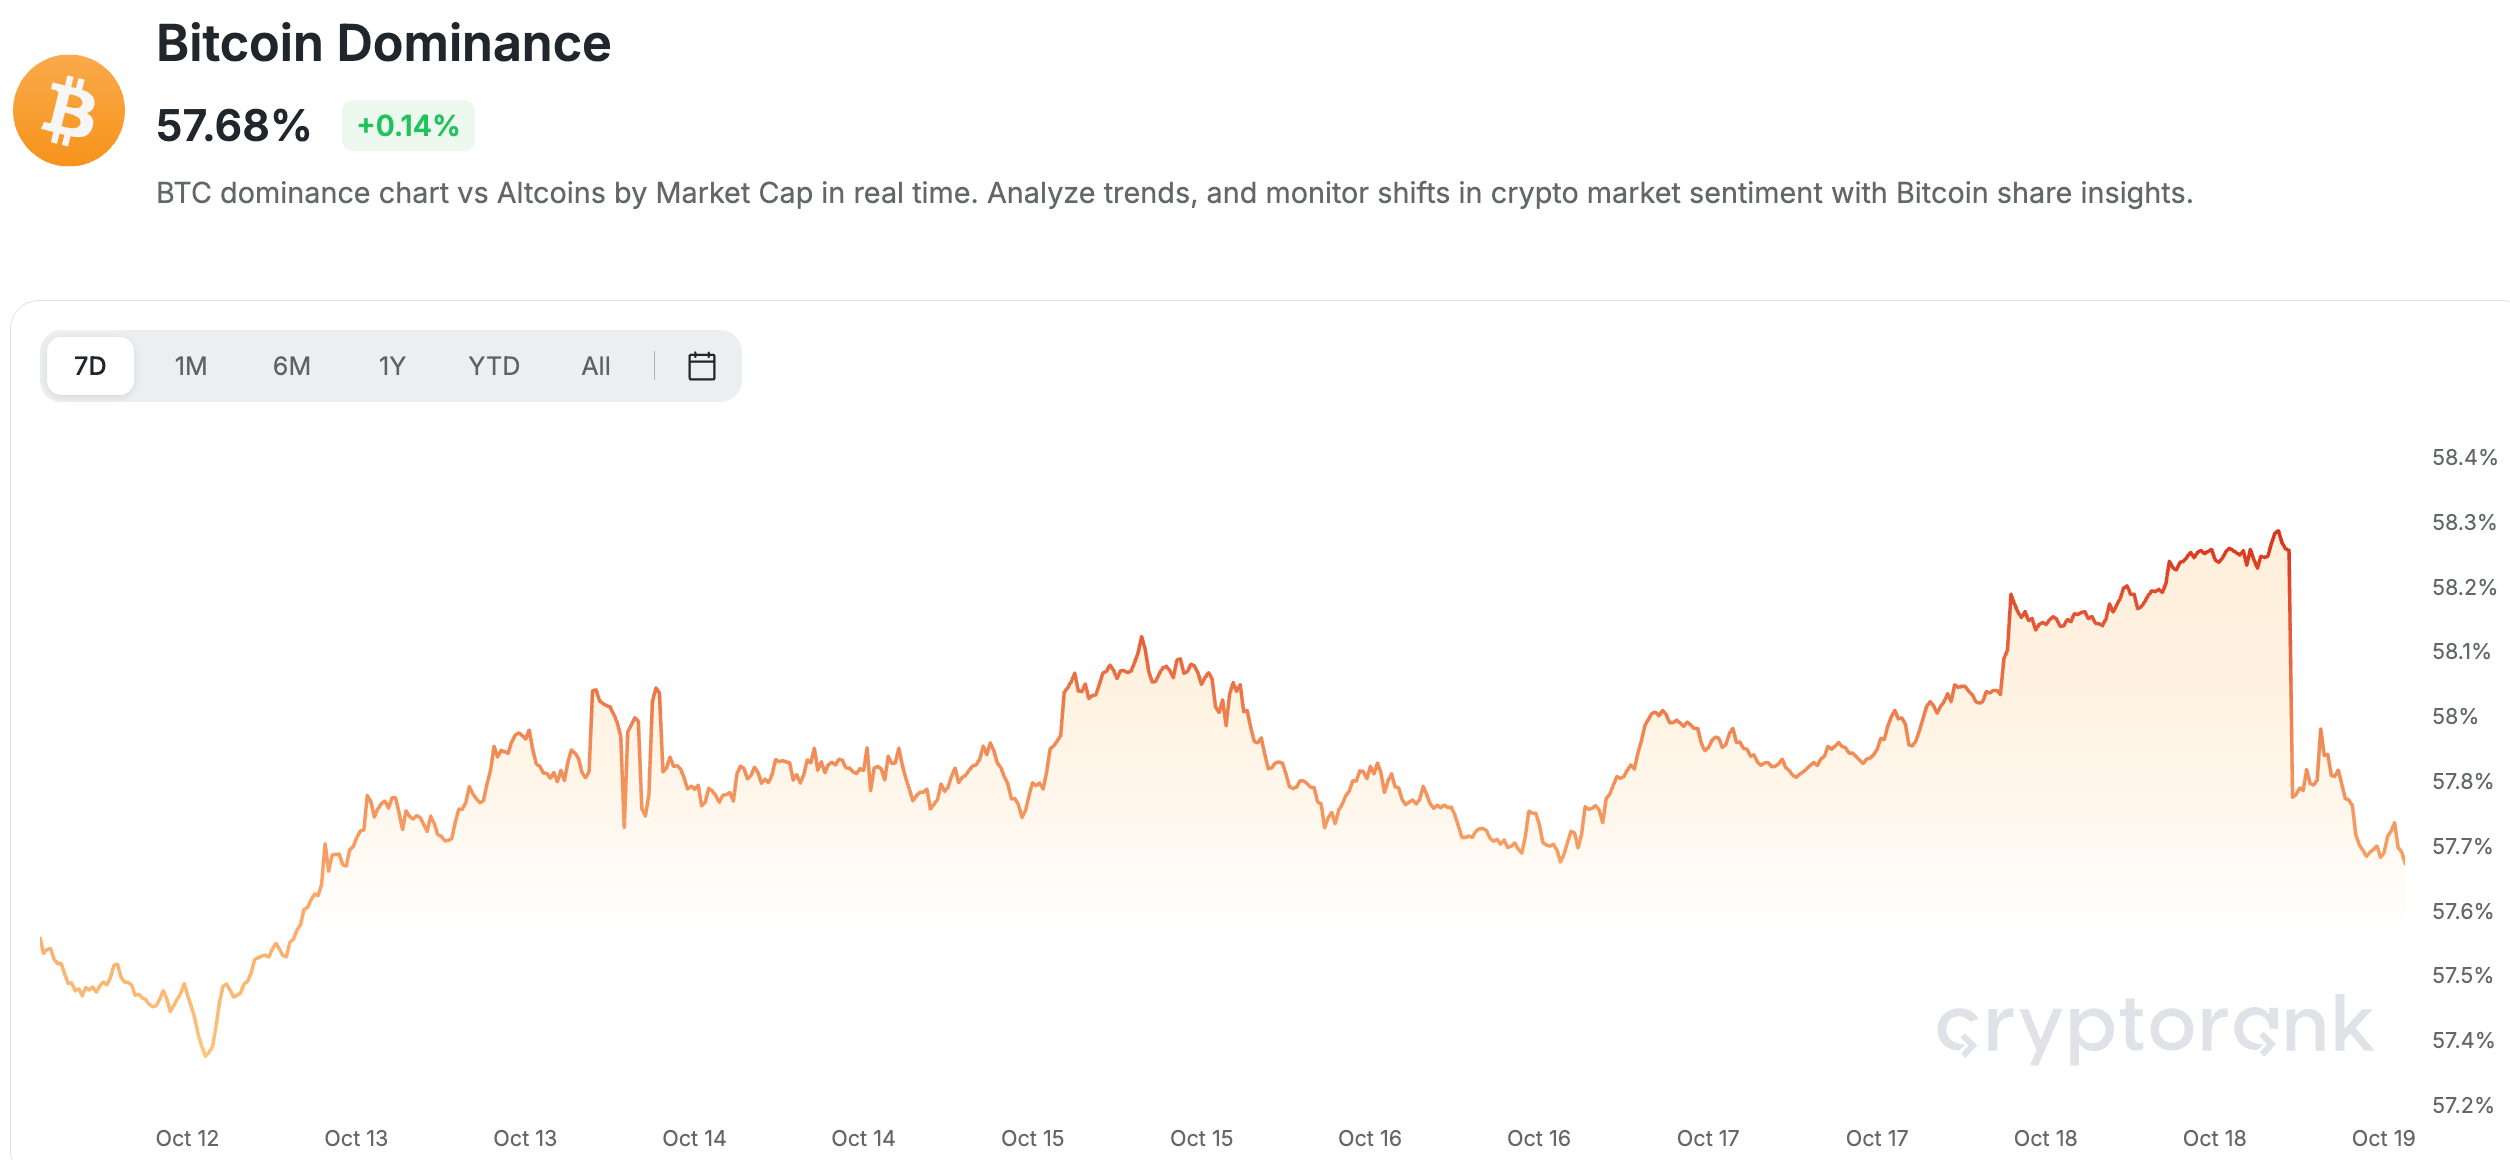
Data source: Bitcoin dominance from cryptorank, https://cryptorank.io/charts/btc-dominance
Data up to October 18, 2026
As of the time of writing, the market capitalization of Bitcoin is $1.65 trillion, accounting for approximately 57.49% of the total cryptocurrency market capitalization. Meanwhile, the stablecoin market capitalization is $311.0 billion, accounting for approximately 10.84% of the total cryptocurrency market capitalization.
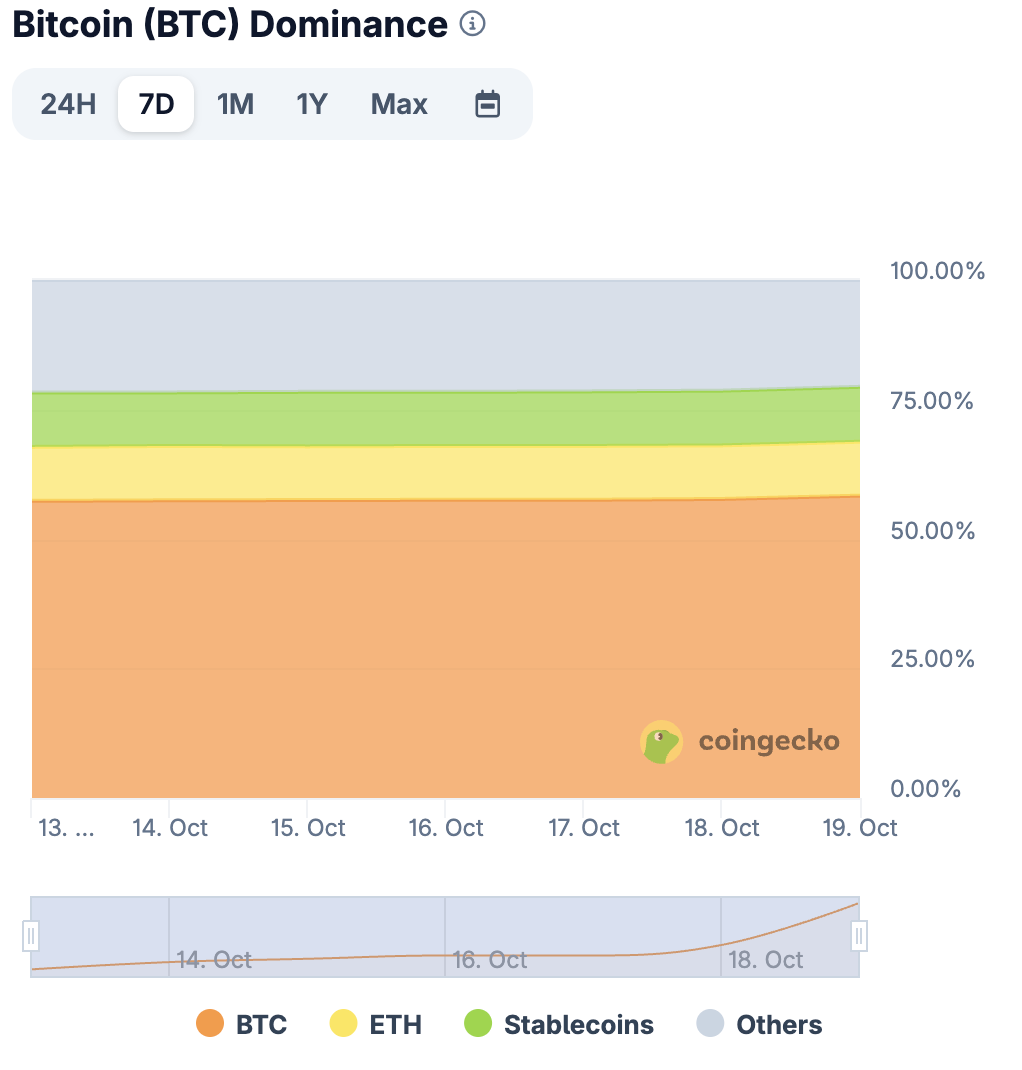
Data source: coingecko, https://www.coingecko.com/en/charts
Data up to October 18, 2026
2. Fear Index
The cryptocurrency fear index is 60, indicating a neutral sentiment; down 8 points from last week's 68.
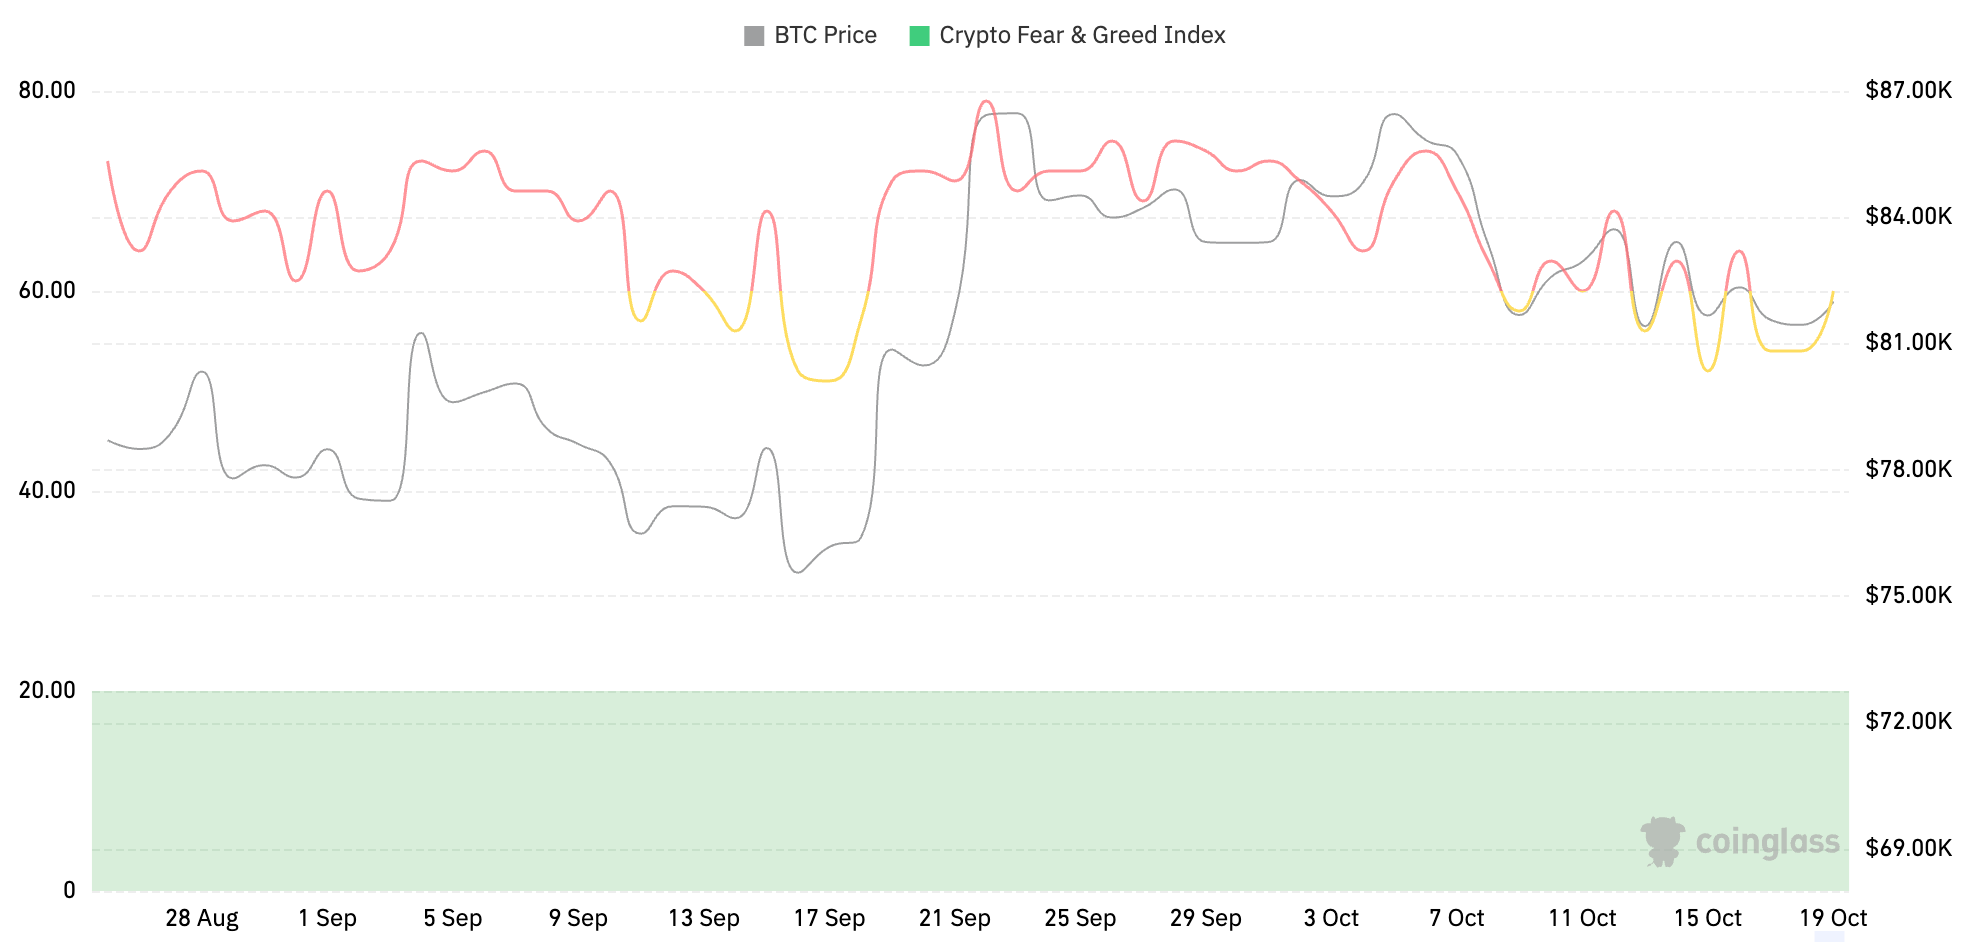
Data source: coinglass, https://www.coinglass.com/pro/i/FearGreedIndex
Data up to October 18, 2026
3. ETF inflow and outflow data
As of the time of writing, the US Bitcoin spot ETF has a total net inflow of approximately $56.88 billion, with a net outflow of $228.58 million this week, and a total net asset value of $104.29 billion, down about 1.46% from last week's $105.84 billion. The US Ethereum spot ETF has a total net inflow of approximately $12.94 billion, with a net outflow of $319.97 million this week, and a total net asset value of $14.95 billion, down about 4.84% from last week's $15.71 billion.
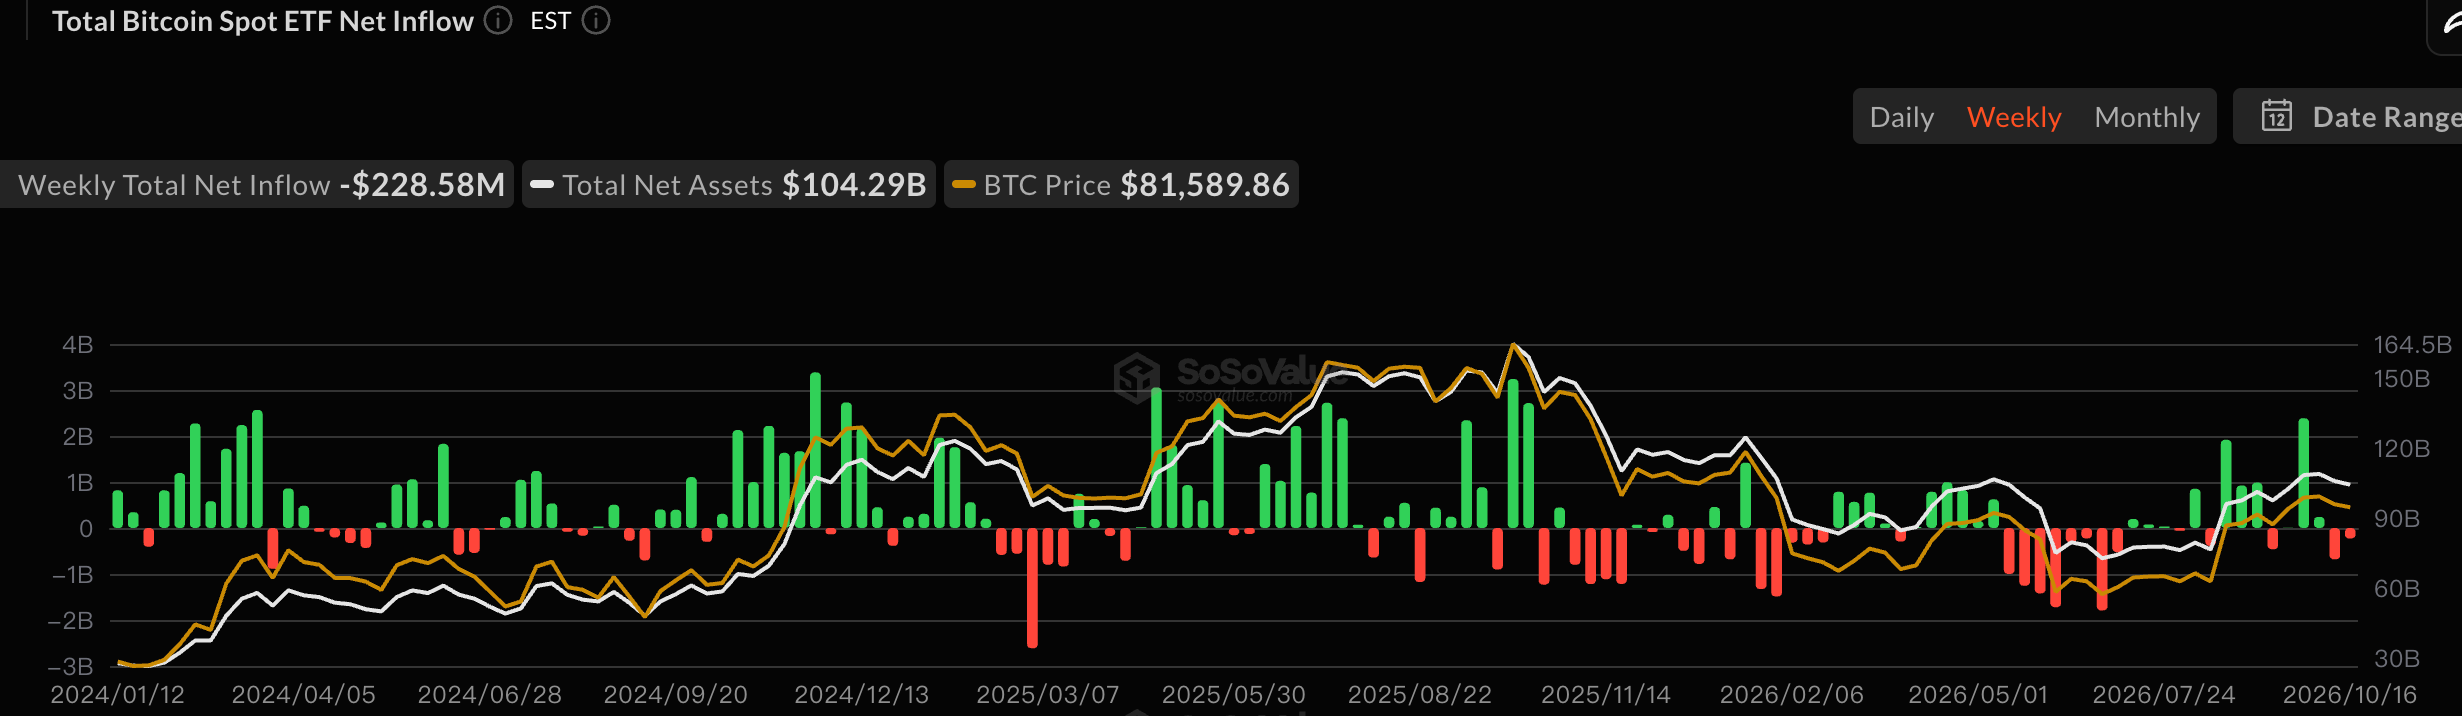
Data source: sosovalue, https://sosovalue.com/zh/assets/etf
Data up to October 18, 2026
4. ETH/BTC and ETH/USD exchange rates
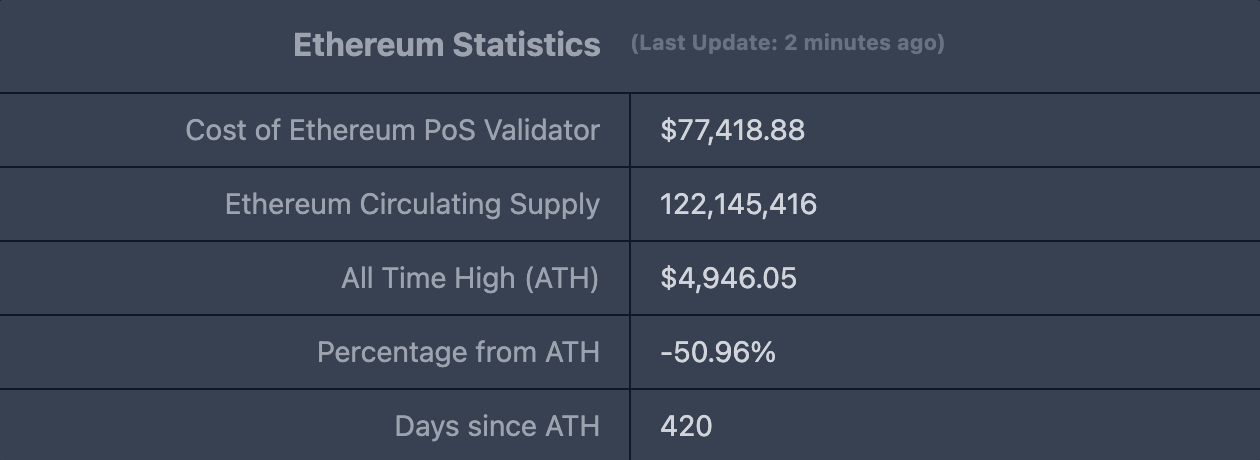
ETHUSD: Current price is $2,421.06, historical highest price is $4,946.05, down about 50.96% from the historical highest price.
ETH/BTC: Currently at 0.029382, historical highest is 0.1238.
Data source: ratiogang, https://ratiogang.com/
Data up to October 18, 2026
5. Decentralized Finance (DeFi)
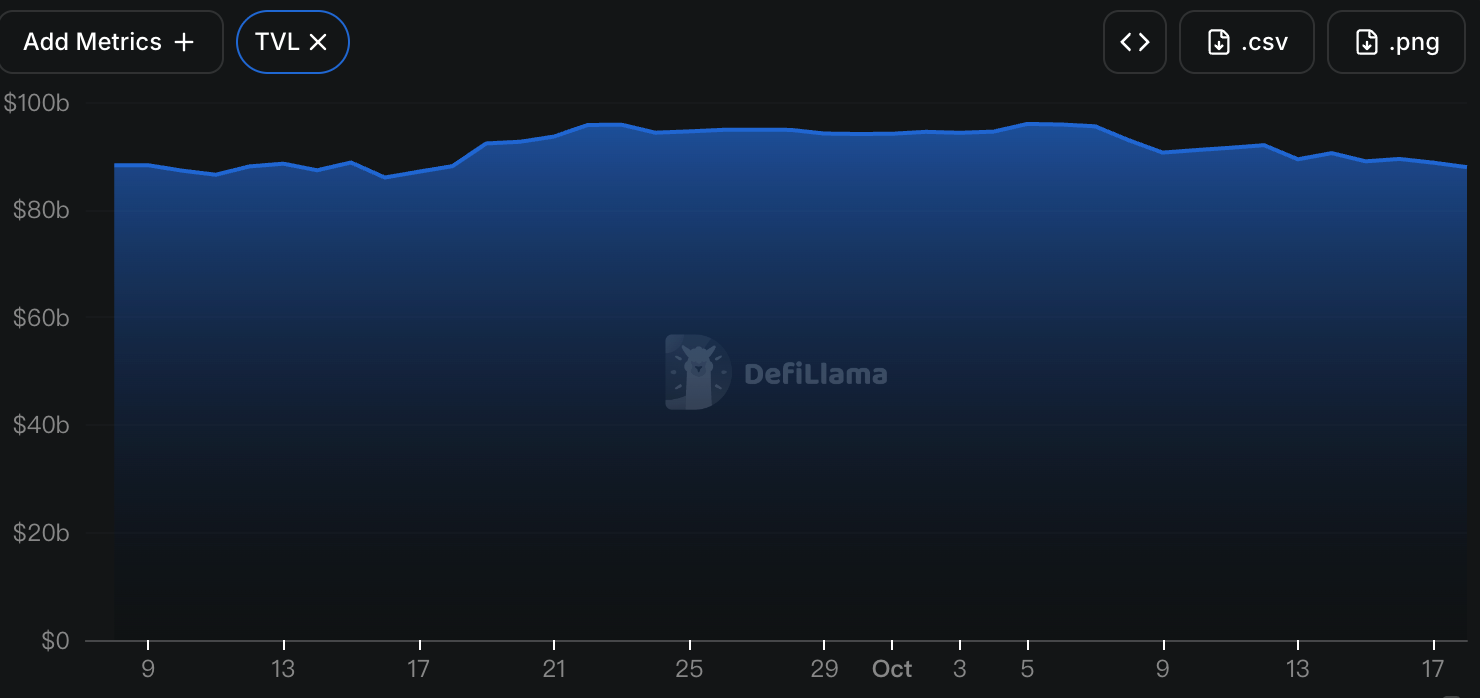
According to DeFiLlama, this week's total DeFi TVL is $87.886 billion, a decrease of about 4.73% from last week's $92.253 billion.
Data source: defillama, https://defillama.com
Data up to October 18, 2026
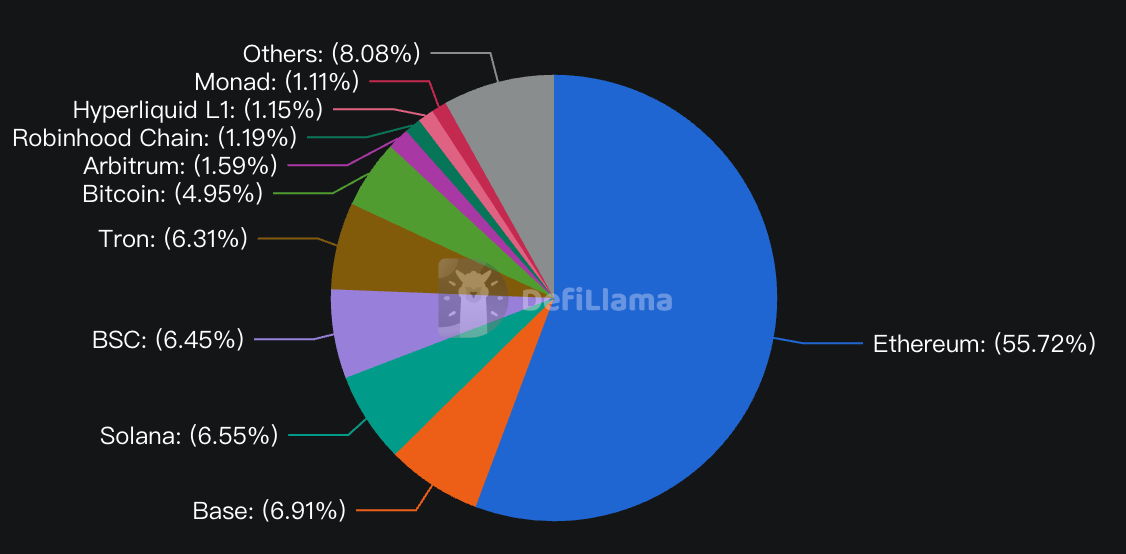
When categorized by public chains, the top three public chains in terms of TVL are Ethereum, accounting for 55.72%; Base, accounting for 6.91%; and Solana, accounting for 6.55%.
Data source: defillama, https://defillama.com/chains
Data up to October 18, 2026
6. On-chain data (Ethereum, Solana, BNB Chain, Ton, Sui, Aptos)
Layer 1 Relevant Data
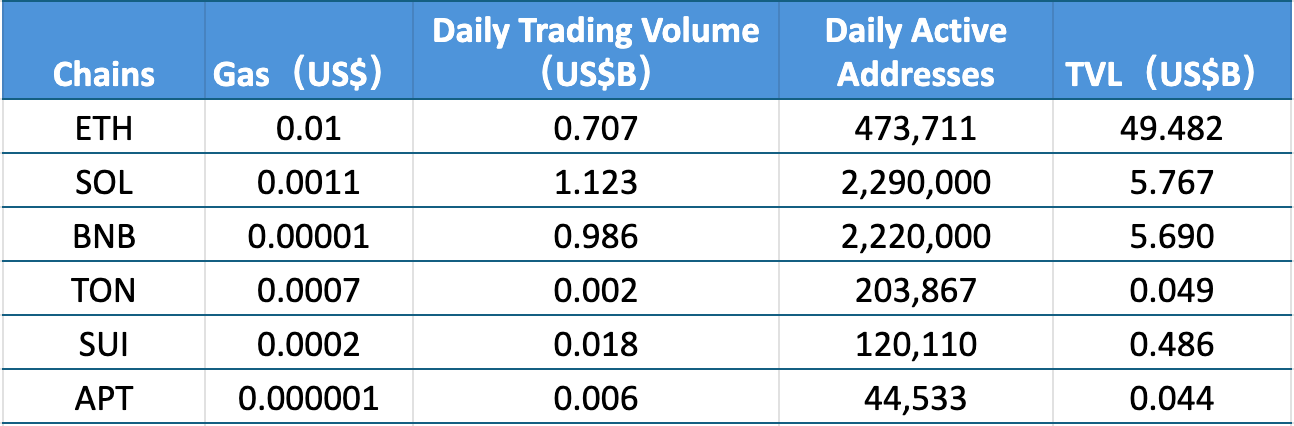
This section analyzes daily trading volume, daily active addresses, and transaction fees for currently major Layer 1 including ETH, SOL, BNB, Ton, SUI, and APTOS.
Data source: CoinW Research Institute, defillama, https://defillama.com
Data up to October 18, 2026
On-chain DEX daily trading volume and transaction fees: On-chain DEX daily trading volume and transaction fees are important indicators for measuring the activity of public chain ecosystems and user trading experiences. The data this week shows a significant divergence in trading activity among mainstream public chain DEXs. Solana continues to maintain the highest trading scale, while BNB Chain's trading volume has nearly doubled, Ethereum and Aptos also showed growth, while TON and Sui saw significant declines. In terms of daily trading volume, Solana ($1.123 billion, +5.05%) remains first; BNB Chain ($0.986 billion, +98.39%) has the largest increase, with trading volume nearly doubling, rising to second; Ethereum ($0.707 billion, +2.46%) shows slight growth, ranking third. Among other public chains, Sui ($0.018 billion, -41.94%) saw a significant decline, TON ($0.002 billion, -50.00%) had its trading volume halved, and Aptos ($0.006 billion, +50.00%) showed growth, but remains relatively small in absolute trading scale. Regarding transaction fees, Ethereum ($0.01), BNB Chain ($0.00001), and Aptos ($0.000001) remained flat compared to last week; Solana gas fees decreased from $0.0012 to $0.0011 (-8.33%), TON decreased from $0.0009 to $0.0007 (-22.22%), and Sui decreased from $0.0004 to $0.0002 (-50.00%). Overall, while the transaction costs of most public chains have decreased further, the changes in trading activity are not consistent.
Daily active addresses and TVL: Daily active addresses reflect the ecological participation and user stickiness of a public chain, while TVL reflects the scale of on-chain capital accumulation. According to this week's data, overall user activity among mainstream public chains is relatively weak; only BNB Chain and Aptos saw an increase in daily active addresses, while Solana, Ethereum, TON, and Sui all declined. Meanwhile, except for BNB Chain, the TVL of the remaining five public chains has all decreased, reflecting overall pressure on on-chain capital accumulation. In terms of daily active addresses, Solana (2.29 million, -19.65%) remains first, down about 560,000 from last week; BNB Chain (2.22 million, +6.73%) ranks second, with a significant reduction in the gap with Solana; Ethereum (473,700, -0.90%) showed a slight decrease. Among other public chains, TON (203,900, -10.34%) saw a decline, Sui (120,100, -27.81%) had the biggest drop, while Aptos (44,500, +5.21%) showed slight growth. Regarding TVL, Ethereum ($49.482 billion, -3.87%) continues to lead by a significant margin; Solana ($5.767 billion, -7.33%) remains second; while BNB Chain ($5.690 billion, +1.55%) ranks third, further narrowing the gap with Solana. Among other public chains, Sui ($0.486 billion, -9.16%) saw a substantial decline, TON ($0.049 billion, -5.77%) decreased, and Aptos ($0.044 billion, -13.73%) had the largest drop. Overall, BNB Chain has achieved growth in trading volume, daily active addresses, and TVL across all three indicators, performing relatively outstandingly, while the capital accumulation of other public chains is generally under pressure.
Layer 2 Relevant Data
According to L2Beat, this week's total TVS for Ethereum Layer 2 is $31.93 billion, a decrease of about 6.31% from last week's $34.08 billion.
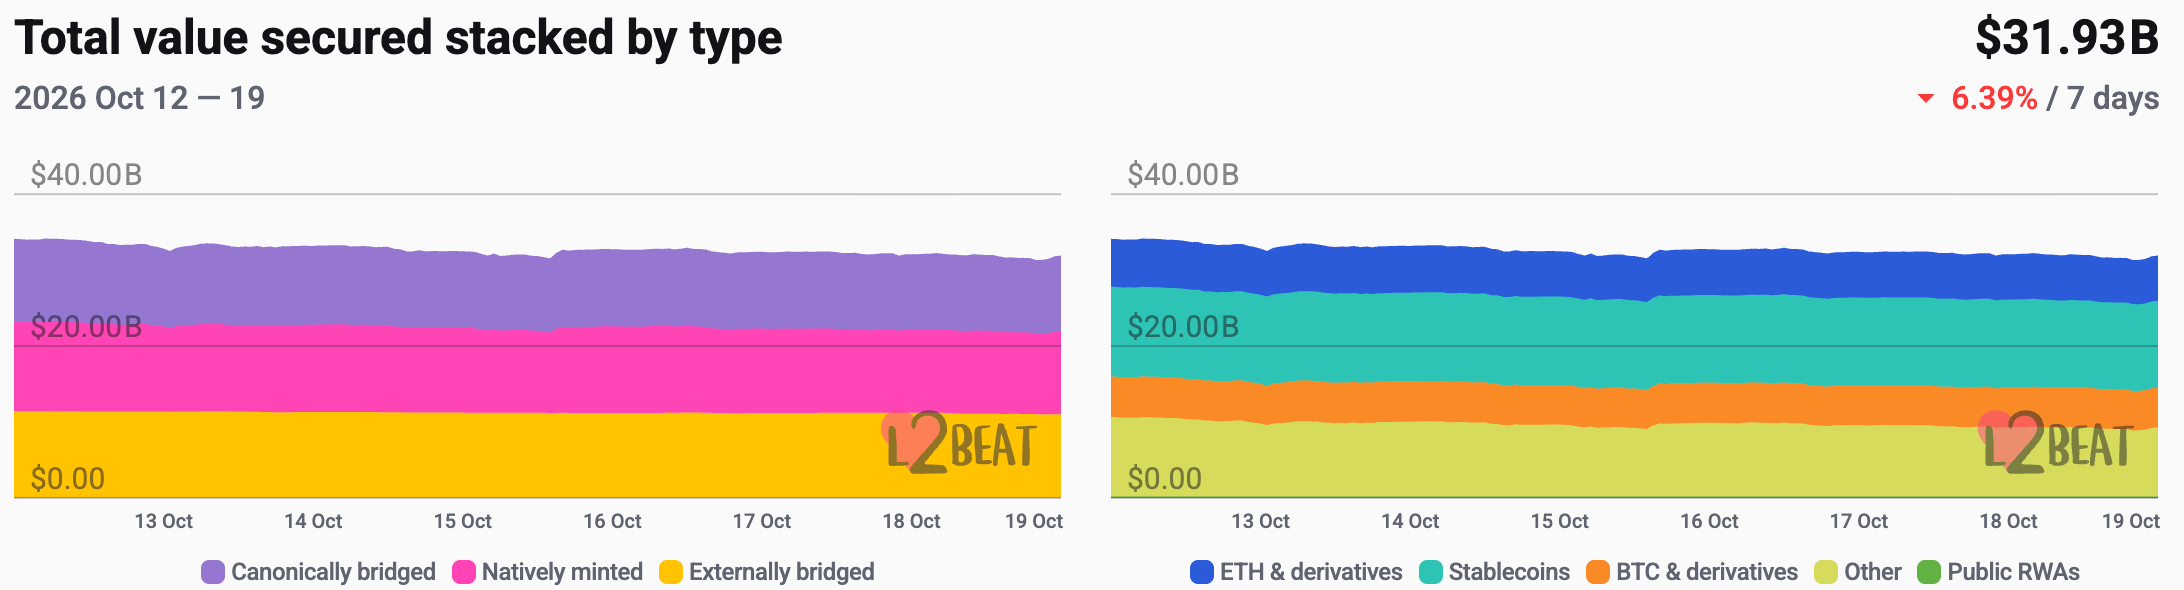
Data source: L2Beat, https://l2beat.com/scaling/tvs
Data up to October 18, 2026
This week, Base and Arbitrum One hold market shares of 58.99% and 13.54%, ranking first and second respectively.
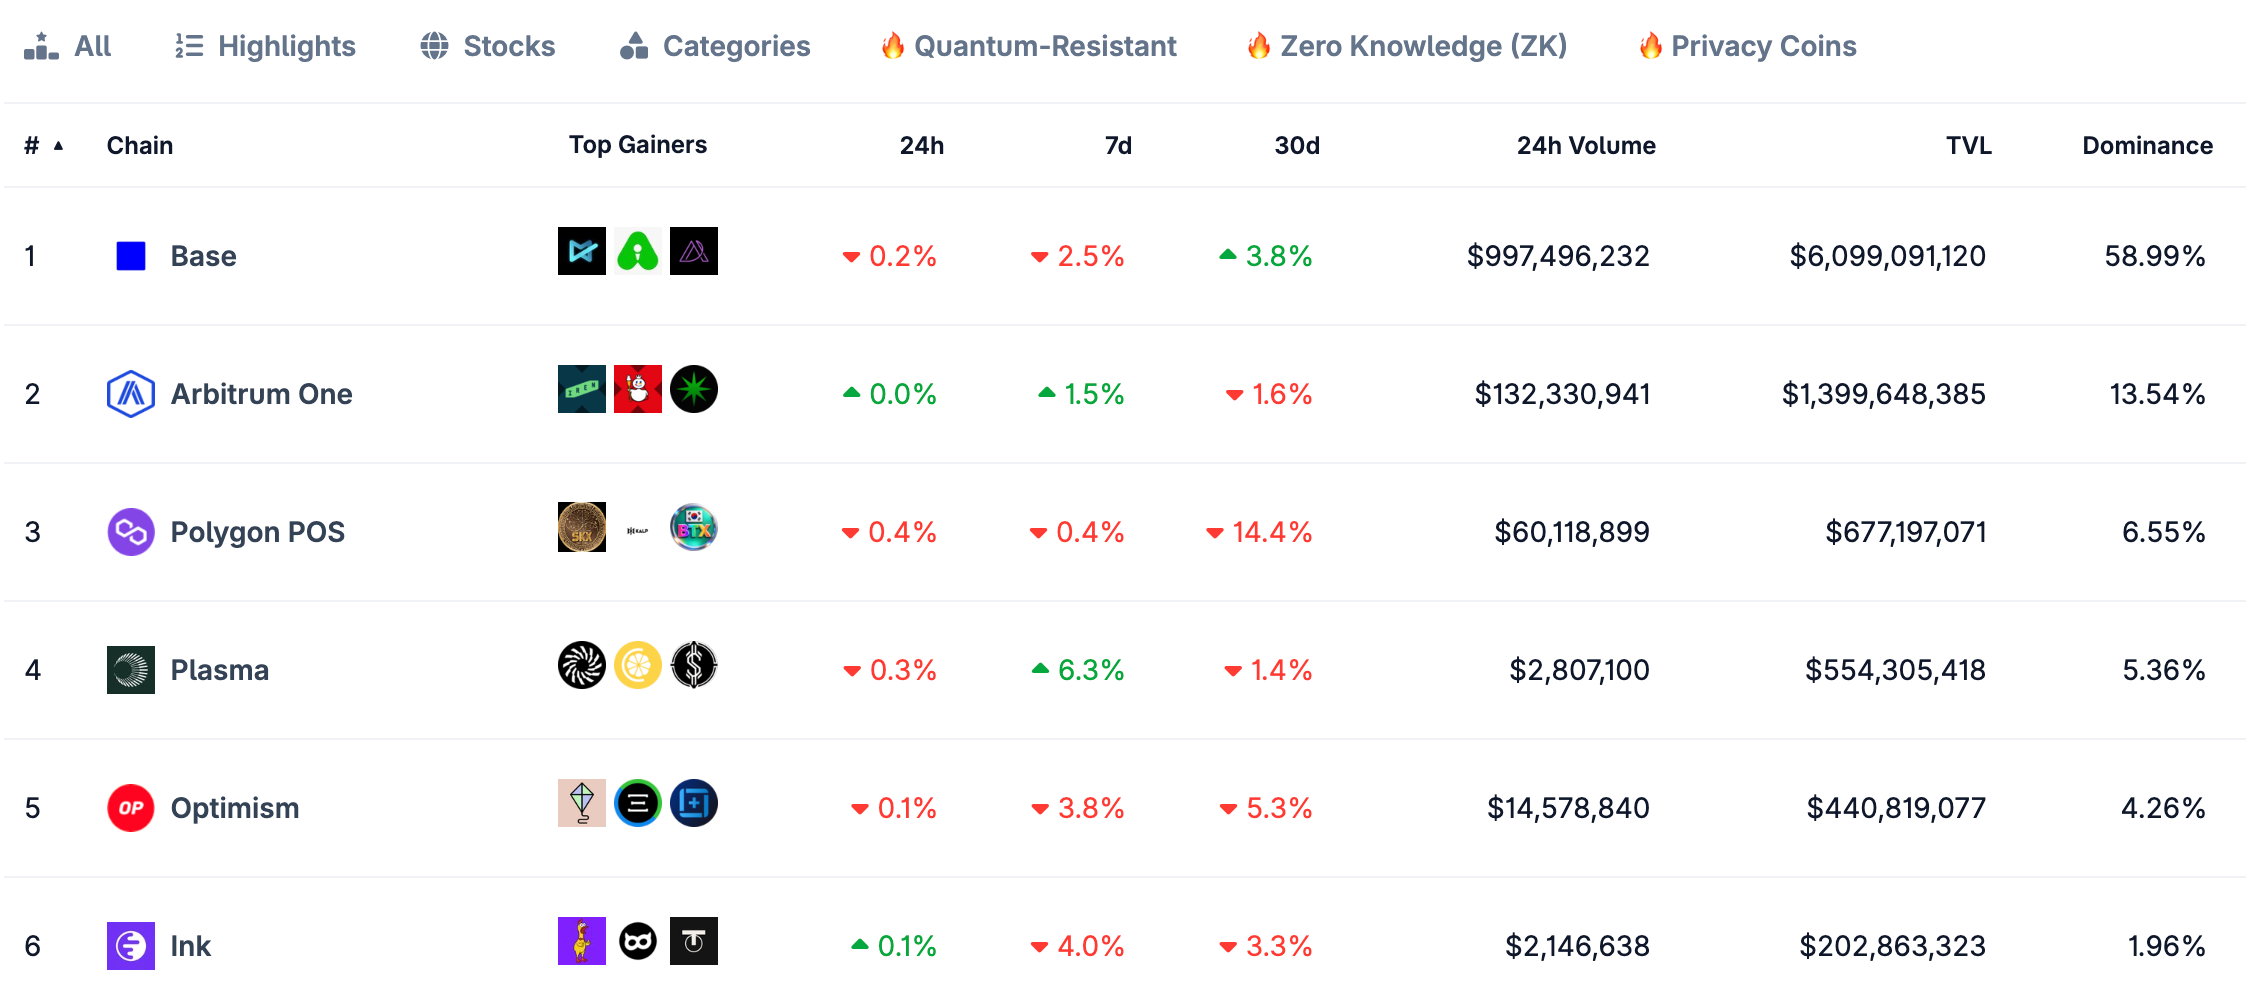
Data source: CoinGecko, https://www.coingecko.com/en/chains/layer-2
Data up to October 18, 2026
7. Stablecoin Market Capitalization and Issuance Situation
According to Coinglass, the total market capitalization of stablecoins is $311.0 billion, up about 0.03% from last week's $310.9 billion. Among them, USDT has a market capitalization of $183.44 billion, accounting for approximately 58.98% of the total market capitalization of stablecoins, down about 0.34% from last week's $184.06 billion; USDC has a market capitalization of $72.48 billion, accounting for approximately 23.31%, down about 0.64% from last week's $72.95 billion; DAI has a market capitalization of $4.51 billion, accounting for approximately 1.45%, down about 0.88% from last week's $4.55 billion.
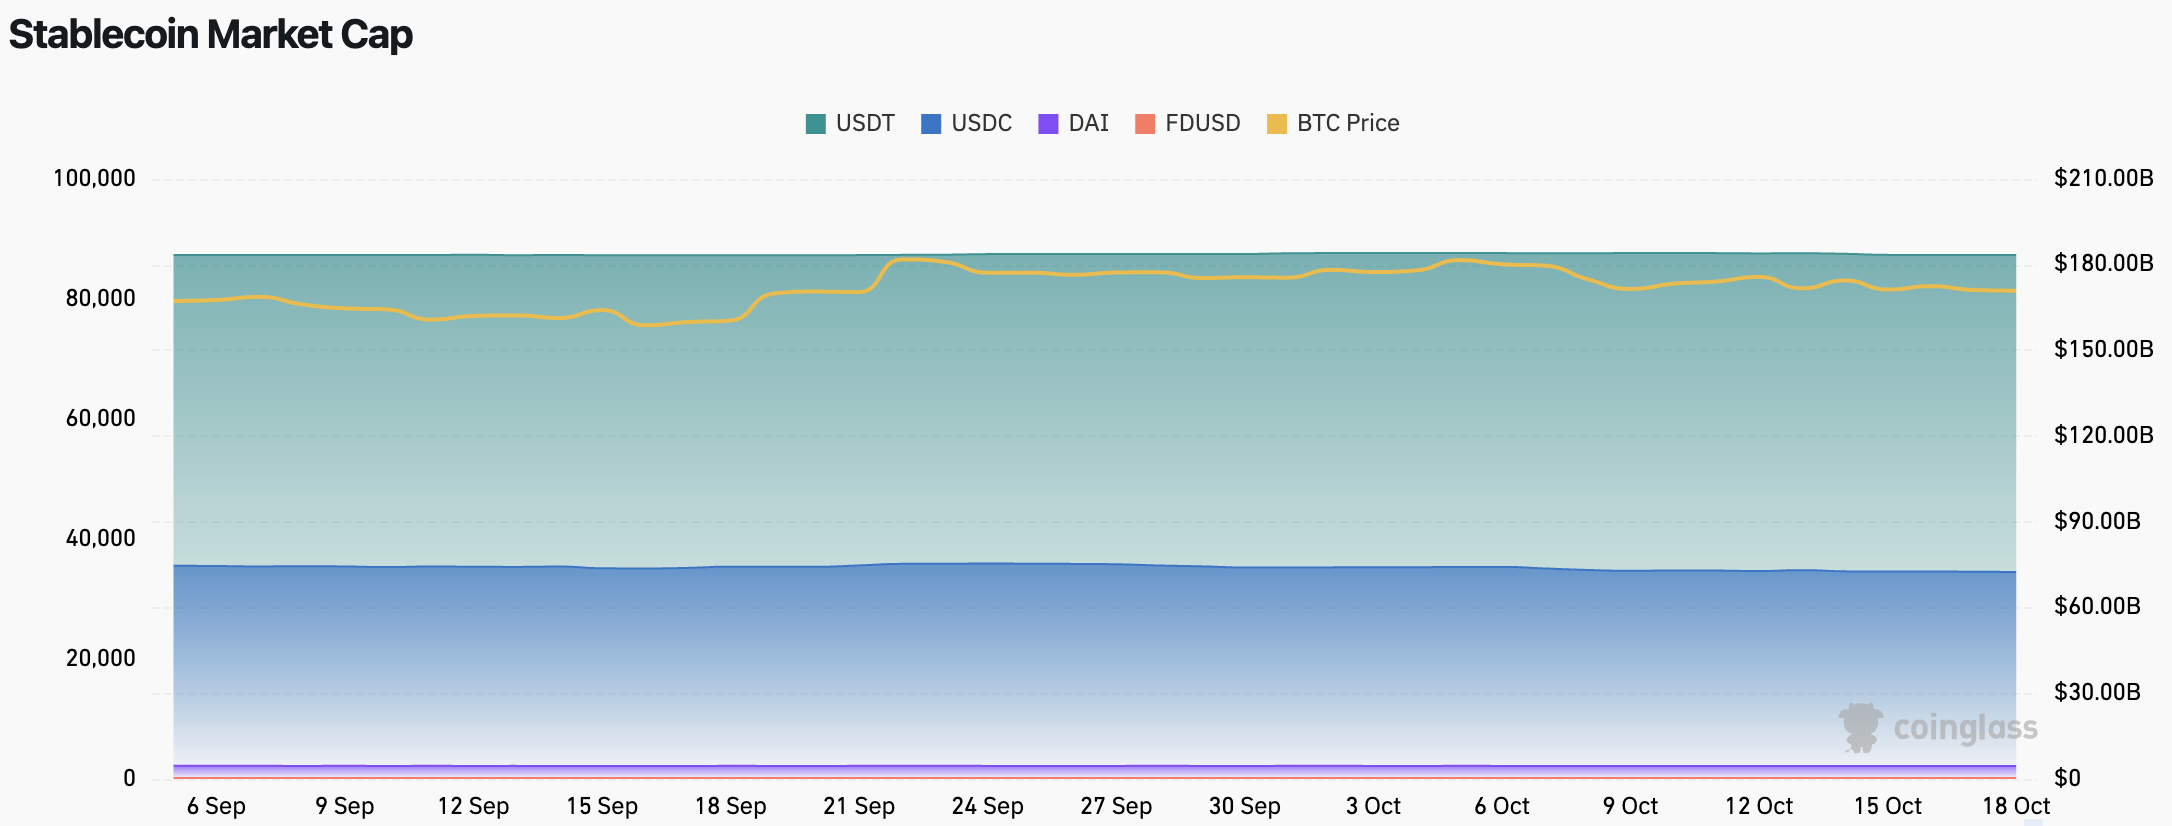
Data source: CoinW Research Institute, Coinglass, https://www.coinglass.com/pro/stablecoin
Data up to October 18, 2026
According to Whale Alert data, this week, USDC Treasury issued a total of 40.17 billion USDC, while Tether Treasury issued a total of 0 USDT this week. The total issuance of stablecoins this week is 40.17 billion, an increase of about 18.53% from last week's 33.89 billion.
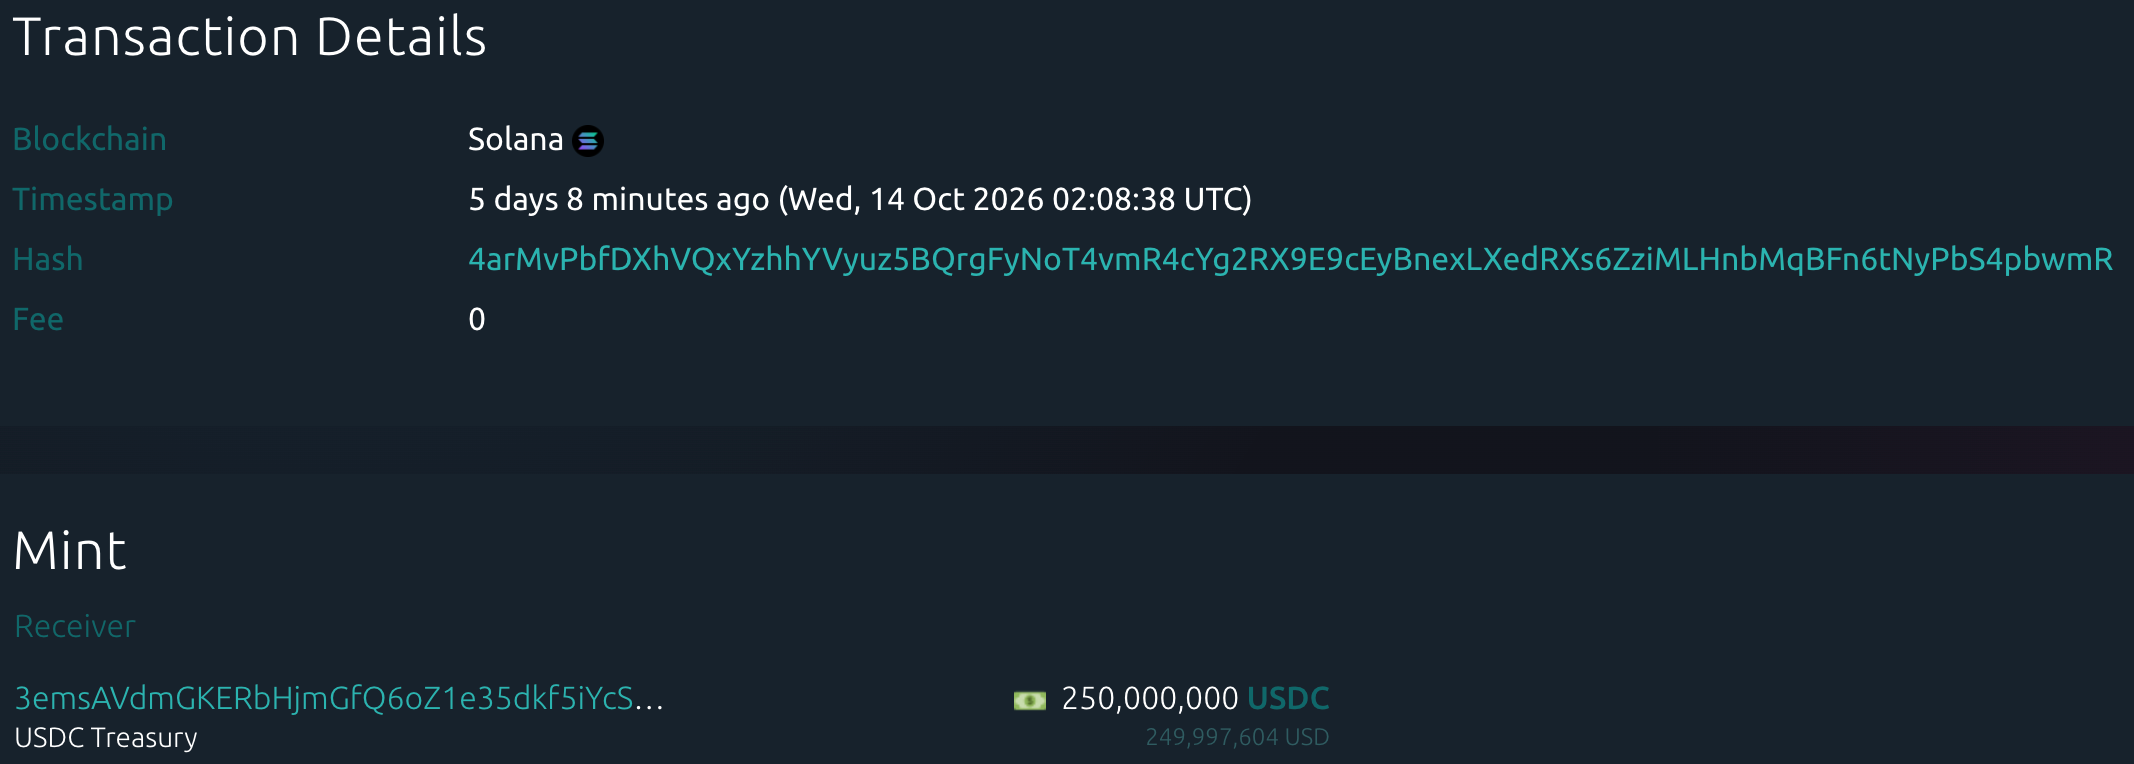
Data source: Whale Alert, https://x.com/whale_alert
Data up to October 18, 2026
2. This Week's Hot Money Trends
1. The top five VC coins and Meme coins with the largest increases this week
The top five VC coins with the largest increases in the past week
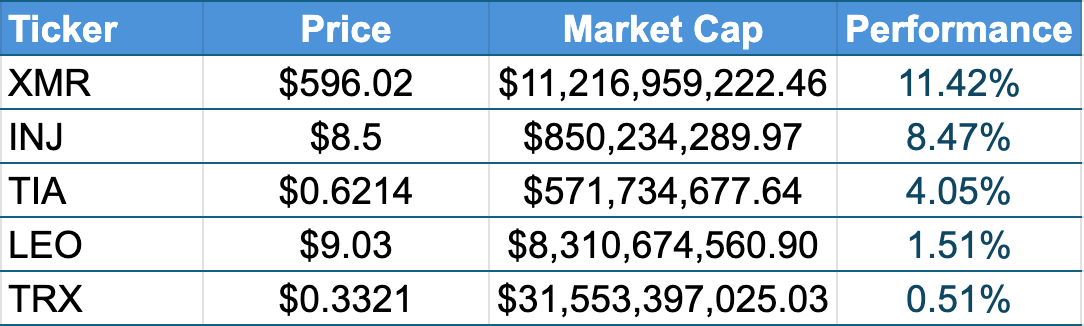
Data source: CoinW Research Institute, coinmarketcap, https://coinmarketcap.com/
Data up to October 18, 2026
The top five Meme coins with the largest increases in the past week
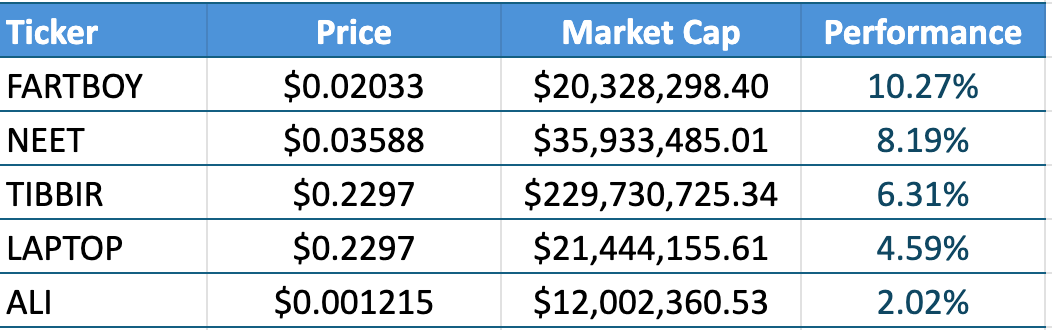
Data source: CoinW Research Institute, coinmarketcap, https://coinmarketcap.com/
Data up to October 18, 2026
2. New Project Insights
Spout Finance is an RWA collateral lending protocol based on Solana, primarily allowing users to borrow USDC by using tokenized US stocks as collateral, aiming to cover borrowing costs through premiums generated from covered call strategies to achieve zero-interest borrowing. The project was established in 2024, with a core team having backgrounds in HSBC, DeFi development, and legal compliance, with former US CFTC Chair J. Christopher Giancarlo serving as a regulatory advisor. On October 15, 2026, Spout announced the completion of $2 million in strategic financing, with investors including Draper Dragon, Anchorage Digital, Flow Traders, Taisu Ventures, Solayer, and support from stakeholders in the Solana ecosystem. The product is still in the Solana Devnet testing phase and has not yet officially launched on the mainnet, nor has it disclosed an independent token issuance plan.
EFY Finance is a stablecoin payment and cross-border settlement platform aimed at the Latin American market, mainly providing stablecoin and fiat currency exchanges, cross-border transfers, OTC, digital wallets, and enterprise payment services, helping individuals and businesses achieve cross-border fund flows through stablecoins like USDT. The project was established in 2023, with a core team including CEO Andrés Tobón and COO Alejandra Gaviria, and has launched operations in multiple markets in Latin America. According to disclosed project information, transaction processing volume in 2025 is expected to reach approximately $1.1 billion, with over 25,000 active personal and corporate accounts, supporting settlements to local bank accounts in 17 countries, and having a certain commercial basis. On October 13, 2026, Tether announced its participation in the seed round funding of EFY Finance, though the specific amount was not disclosed; both parties plan to further expand stablecoin payment infrastructure in Latin America. The project has not yet disclosed an independent token issuance plan.
AIsa (marked as Alsa by RootData) is a payment and resource calling infrastructure platform for AI Agents, allowing AI Agents to access external APIs, AI models, and software services through a unified interface and settle automatically based on actual usage via fiat or stablecoins. The platform also provides consumption limit, permission management, and transaction approval capabilities, helping businesses manage AI Agents' autonomous payment behaviors. The project is headquartered in San Francisco, USA, founded by Jordan Liu. On October 15, 2026, AIsa announced that it has received strategic investments from Tether and HIVEN, totaling over $9 million, with previous investors including Alibaba, Tribe Capital, Sumitomo Corporation, and Draper Associates. According to official disclosures, the platform is connected to over 5,000 APIs, skills, and models, with over 250,000 Agents, having processed over 100 million transactions and has begun pilot projects with some enterprises.
3. Industry News
1. Major industry events this week
NeoSoul (DNA) announced on October 15 that it will establish a special DNA airdrop quota to reward community contributors who have participated in the long-term development of StandX, and expressed its willingness to discuss community support plans with the StandX team. NeoSoul is an infrastructure project for the AI Agent economy, with NeoTrade providing trading agency execution services, EvoEvo focusing on collaboration and evolution of AI Agents, and DNA being used for agency services, data payment, governance, and security pledging. DNA started trading on October 16, with related platforms concurrently launching token incentive activities. However, the special airdrop targeted at the StandX community is different from other distribution plans; the specific quota, qualification standards, snapshot time, and redemption entry have not yet been disclosed, with officials stating they will announce this after the DNA TGE. Future attention will be focused on the user qualification identification of StandX, the actual airdrop ratio, and redemption arrangements.
Derive (DRV) launched a DRV token reward activity on October 14 for eligible users. Derive is a decentralized crypto derivatives protocol that mainly provides on-chain options and perpetual contract trading, formerly known as Lyra. It is worth noting that DRV is not a newly issued token this week; the officials opened DRV collection as early as January 15, 2025, allowing original LYRA holders to migrate at a 1:1 ratio, with an additional 7.71% of the total supply allocated for user and partner airdrops. The protocol also establishes staking, governance, and revenue buyback mechanisms. This week's new activities are targeted at users meeting specific point thresholds, and eligible users can receive 70 DRV, with the number of rewards being limited, and specific qualifications and redemption rules determined by the activity platform. Future attention will focus on reward distribution conditions, liquidity changes brought about by new trading channels, and the actual execution of the protocol's revenue and DRV value capture mechanism.
AlloX (ALLOX) launched a public token sale on October 12, with the subscription window open until October 19, 12:00 (UTC). AlloX is an AI-driven on-chain investment platform that analyzes market narratives using AI, builds multi-asset investment portfolios, and provides automated asset allocation and trading aggregation services. This sale is conducted through Sonar by Echo, supporting subscription in USDT and USDC, with a minimum participation amount of $100. The sale is divided into three tiers, corresponding to fully diluted valuations (FDV) of $65 million, $52 million, and $39 million: the first tier is fully unlocked at TGE, the second tier unlocks 20% with the remaining portion released linearly over 12 months, and the third tier has a 3-month lockup followed by 12 months of linear release. The project team disclosed that over 2.6 million wallets have registered, with approximately $57 million in on-chain investment and over $170 million in DEX aggregate trading volume, although these figures still need independent verification. The final TGE date has not yet been confirmed, and future attention will focus on the actual fundraising scale, initial circulation, and lockup pressure of different sales tiers.
2. Major events happening next week
StandX officially announced on October 15 that it is canceling the platform's token generation event (TGE), replacing it with a one-time DUSD airdrop to the community, and gradually ceasing platform operations. StandX is a perpetual contract trading platform that provides trading and fund management services centered around the yield-bearing stablecoin DUSD. The project disclosed that since its mainnet launch in November 2025, it has served over 237,000 users, with a peak TVL exceeding $200 million. This airdrop covers pre-deposits, alpha testing, mainnet trading, market-making, and invitation activities, with rewards being unlockable, but subject to witch hunt and abnormal transaction reviews. Qualification inquiries will be open on October 26, 00:00 (UTC), with claims opening on November 1 and closing on December 31 at 08:00. At the same time, the platform will enter a reduction mode starting on October 20 and will close remaining positions on January 15, 2027, with withdrawals and DUSD redemptions ceasing by January 31. This event signifies that StandX no longer holds the original token TGE expectations; existing users should prioritize attention to asset exits and airdrop claim deadlines.
Fables (FABLES) plans to conduct its TGE on October 20, with liquidity scores and token claim scheme selections ending around October 19. Fables is a DeFi project built around tokenized stocks and on-chain trading, and the market is watching how it will attract users through trading and liquidity incentives. The current public activity calendar shows the target TGE date is October 20, but the final token allocation, initial circulation size, and trading liquidity are still subject to official announcement. Future focus will be on airdrop qualifications, lockup selections, and actual trading demand post-TGE.
infiniFi (INFI) announced the preliminary economic model of its native token INFI on October 14 and confirmed that TGE is approaching. infiniFi is a DeFi yield protocol implementing a partial reserve mechanism on-chain, mainly providing stablecoin deposits and yield management services to increase capital efficiency through various liquidity term funding allocations. According to disclosed plans, 45% of the total INFI supply will go to the ecosystem, with the team and investors each taking 20%, and the foundation taking 15%. The upcoming community airdrop will be allocated from the ecosystem share. Currently, the 45% ecological allocation does not mean all will be used for airdrops; officials have yet to announce the specific proportion of the community airdrop, total supply, TGE date, snapshot rules, and initial unlocking arrangement, and the token's utility also awaits further disclosure. Future focus will be on the complete token economic model, team and investor unlock cycles, airdrop qualifications, and the value capture relationship between INFI and the protocol's real returns.
3. Important investments and financing from last week
Fission completed a $10 million Series A financing round led by Pantera Capital, with Circle Ventures, New Form Capital, gumi Cryptos Capital, Borderless Capital, and CEO Ari Rubenstein of GTS participating. Fission was established in 2024 by a team with backgrounds at Point72 and Securitize, primarily providing exit and liquidity services for tokenized private funds and other illiquid investment products, helping qualified institutional investors sell tokenized fund shares before the traditional fund redemption cycle ends for quicker capital recovery. The company disclosed that its platform has handled million-dollar redemption transactions. The funds from this round will be used to expand liquidity supply, support more tokenized private and semi-liquid funds, and deepen cooperation with digital asset investment platforms. (October 15, 2026)
DATA Network received a $30 million strategic investment from the Sui Foundation, with both parties promoting the migration of DATA Network from an independent public chain to Sui, with original independent chain plans gradually ceasing operations. DATA Network, formerly Story Protocol, transitioned in June 2026 to focus on AI training data verification and traceability infrastructure, with its core product Trace recording the sources, contributions, and ownership information of AI training data. This collaboration will integrate the Sui blockchain and decentralized storage network Walrus, providing infrastructure for AI data registration, verification, and storage. The existing DATA token is planned to migrate to Sui at a 1:1 ratio, preserving corresponding governance and economic rights; the Sui Foundation will become one of the main institutional holders of the project. (October 12, 2026)
Uniform Labs announced the completion of its seed round financing, raising a total of $8 million, with the latest round led by Polychain and participating from Strobe Ventures, CMT Digital, Metalayer Ventures, Generative Ventures, and Circle Ventures. Uniform Labs is the developer of the tokenized asset liquidity and settlement platform Multiliquid, whose core product enables institutions to convert between tokenized funds, US Treasury bonds, and stablecoins like USDC through single atomic transactions, reducing the settlement waiting time caused by traditional fund subscription and redemption processes. The platform operates in a non-custodial manner, supporting transaction pricing based on Net Asset Value (NAV), and has already deployed on Ethereum and Solana, meeting institutional compliance requirements. Multiliquid has integrated tokenized fund products from asset management institutions like Wellington Management, VanEck, and Janus Henderson. (October 15, 2026)
4. Reference Links
1. Coingeck: https://www.coingecko.com/en/charts
2. Coinglass: https://www.coinglass.com/pro/i/FearGreedIndex
3. Sosovalue: https://sosovalue.com/zh/assets/etf
4. Ratiogang: https://ratiogang.com/
5. Defillama: https://defillama.com
6. L2Beat: https://l2beat.com/scaling/tvs
7. Footprint: https://www.footprint.network/public/research/chain/chain-ecosystem/layer-2-overview
8. Coinglass: https://www.coinglass.com/pro/stablecoin
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。