MSCI is about to announce the index adjustment list, the precarious situation of Bitcoin's largest buyer
Written by: ChandlerZ, Foresight News
The Strategy, which holds over 850,000 Bitcoins, is waiting for MSCI to release a list that could change its shareholder structure.
The index provider MSCI has determined a new method to screen out non-operational companies that do not meet the requirements of its global investable market indices. Strategy has appeared on a previously published potential deletion list, with the final results expected to be announced after 6 AM Beijing time on November 12.
With over 850,000 Bitcoins and a cumulative purchase cost exceeding $64.1 billion, Strategy was previously on the candidate deletion list and if the final list confirms its removal, global passive tracking funds will be forced to adjust their holdings before the market closes on November 30, triggering a rigid sell-off of between $1.57 billion and $2.8 billion. This event will directly suppress Strategy's equity premium and block its core channel for delivering incremental buying pressure to the crypto spot market.
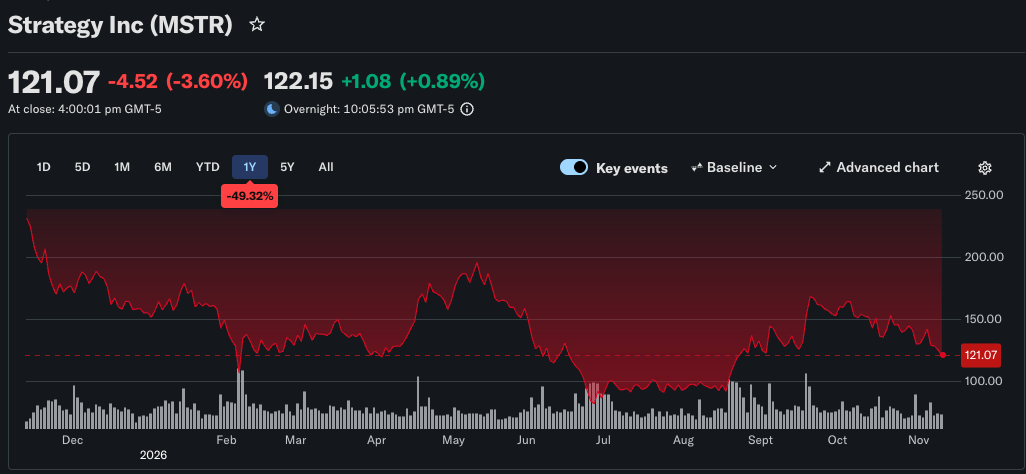
As of the close of U.S. stocks on November 11, Strategy's common stock MSTR closed at $121.07, down 3.60% for the day, which is approximately a 6.4% drop from the closing price of $129.30 on November 5. The company disclosed on November 9 that as of November 8, it held 850,364 Bitcoins, with a cumulative purchase cost of about $64.16 billion.
Why is Strategy being removed from the index?
MSCI's global indices are used by many funds to build stock portfolios, and whether a company remains in the index will affect the holdings of passive tracking funds.
In October last year, MSCI proposed a removal plan for treasury companies where digital assets account for 50% or more of total assets, and this January decided to postpone its implementation in the February review, turning to a broader review of non-operational companies.
On October 16, MSCI finalized a new index admission rule that will begin with the November index review. Companies that primarily rely on asset holdings to derive value and lack actual operational activities may be classified as "non-operational companies" and will no longer qualify for inclusion in the MSCI global investable market indices. In other words, companies like Strategy, Metaplanet, and Upexi that rely on capital market financing to acquire coins may no longer be considered ordinary operational enterprises by MSCI.
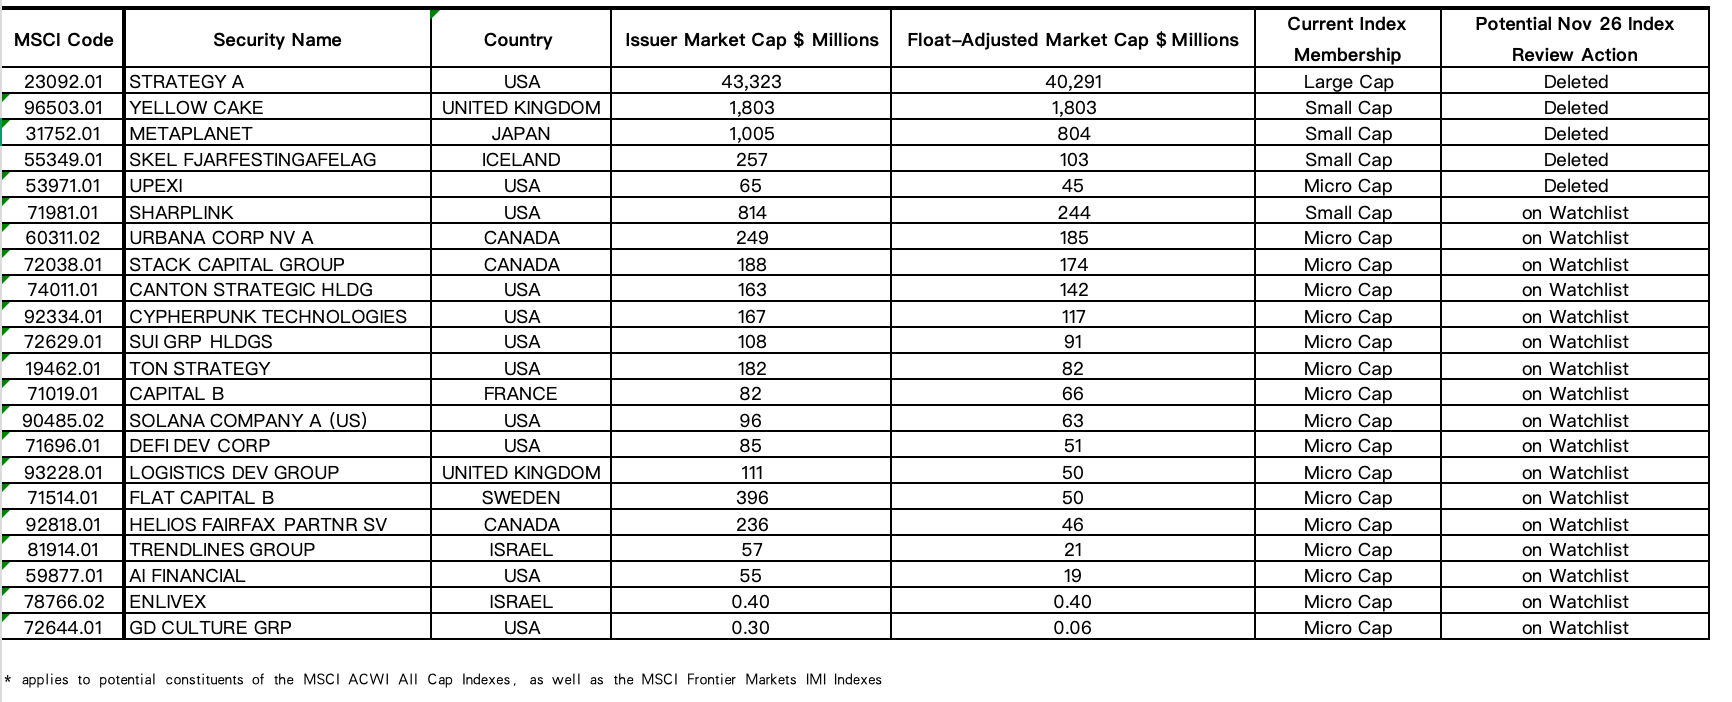
MSCI also published a potential affected list. Among the 22 companies, 14 are directly related to cryptocurrencies: Strategy, Metaplanet, and the SOL treasury company Upexi are listed for deletion, while SharpLink, Solana Company, and 11 other companies have been placed on the watch list.
The new rule first assesses whether a company has enough operating assets in its asset structure. Companies that fail this assessment will be subject to checks on five financial metrics: operating expenses, operating cash flow, fair value changes, and reliance on external financing. If four or more trigger a failure, they may lose index eligibility. For companies already in the index, MSCI requires that they have not passed the screening in both of the most recent annual reporting periods before removing them.
Of the 5 companies proposed for deletion, 3 are digital asset treasury companies:
- Bitcoin treasury company Strategy;
- Bitcoin treasury company Metaplanet;
- SOL treasury company Upexi.
The other two are the UK uranium investment company Yellow Cake and the Icelandic investment holding company SKEL, illustrating that the rules are not formally targeting just crypto assets.
Additionally, 11 crypto-related companies have been placed on the watch list, including:
- ETH treasury company SharpLink;
- CC (Canton) treasury company Canton Strategic Holdings;
- ZEC treasury company Cypherpunk Technologies;
- SUI treasury company SUI Group;
- TON treasury company TON Strategy;
- BTC treasury company Capital B;
- SOL treasury company Solana Compan;
- SOL treasury company DeFi Development;
- WLFI treasury company AI Financial;
- RAIN treasury company Enlivex;
- A company holding BTC that had announced allocation for TRUMP, GD Culture.
Strategy opposes the new method, arguing that it still operates a software business and classifies its Bitcoin operations as an operating segment in its financial reports. MSCI states that the new screening method applies to companies with financial characteristics similar to investment tools and is not limited to businesses holding crypto assets.
Countdown to repositioning, billions of dollars in mechanical clearing
If Strategy is removed, the stock directly faced with selling pressure is its stock MSTR. Funds that fully replicate the related index typically need to sell off the constituent stocks they hold; funds that adopt sampling replication may adjust according to their investment strategies, and the trading times and amounts of different products may vary.
A simulation model released by JPMorgan previously suggested that if all funds with correlated benchmarks retreat, the upper limit of passive outflow may reach $2.8 billion. The quantifiable bottom line officially provided by Strategy is relatively convergent, with estimates showing that passive funds tracking this index collectively hold about 13 million shares of MSTR, accounting for 3.1% of its total share capital, corresponding to a market value of about $1.57 billion at the current price.
Based on a simple calculation using the closing price of $121.07 on November 11, this batch of shares is valued at about $1.57 billion. The company believes this amount is below its then-estimated average daily trading volume, thus having limited impact on its business.
However, high trading volume does not mean that new sell orders can necessarily be met by buyers around the original price. Some investors may trade in expectation of the list ahead of time, and the true price for repositioning will depend on whether other buyers are willing to absorb the sell-off. Passive funds selling MSTR will not directly sell off Bitcoin on Strategy's balance sheet, which remains held by the company.
Will the drop in stock price affect Bitcoin?
The real destructive power of passive capital exiting lies in breaking through the arbitrage loop that Michael Saylor has built relying on U.S. stock market liquidity.
The buying model of Strategy for Bitcoins over the past four years relies entirely on the long-term high premium of its stock price relative to the underlying Bitcoin net asset value (mNAV). As long as the premium exists, the company can issue common stock through the at-the-market (ATM) mechanism at high prices in the U.S. stock market, or even issue low-interest convertible bonds for cash. The fiat currency raised is directed unidirectionally by management into the crypto spot market for buying. The rapid expansion of Bitcoin reserves further stimulates retail and hedge fund speculative sentiment, driving up the stock price premium, leading to the next round of larger-scale equity financing.
From November 2 to 8, Strategy just used this mechanism to sell 2.05 million shares of MSTR for $283.8 million, subsequently converting $81.9 million of that into 1,036 Bitcoins in the spot market.
If removal brings ongoing selling pressure, the price and valuation of MSTR may be impacted, and the funds the company can raise per share when issuing stock in the future will decrease. To raise the same amount of money, Strategy may need to issue more shares, which would dilute the ownership percentage of existing shareholders. If investors simultaneously demand higher returns, the costs of financing through preferred stock or debt may also rise.
Financing pressures further transmit to Bitcoin, requiring the company to reduce future purchases, sell existing assets, or adjust positions in sync with other investors. Removal from the index alone cannot deduce that Strategy must sell Bitcoin nor can it speculate how much Bitcoin might fall as a result.
However, Strategy has already sold Bitcoin this year. The company disclosed that this year some Bitcoin sale proceeds of about $431.8 million were used to support preferred stock dividends and STRC repurchase; meanwhile, the company continues to buy Bitcoin. As of November 8, its dollar reserves specifically for supporting preferred stock dividends and debt interest amount to about $4.77 billion, with another $146.2 million in cash available for broader corporate purposes.
Even Metaplanet, Upexi, and SharpLink have replicated the financial engineering script of issuing stock to accumulate tokens. The core weakness of these enterprises is highly consistent, that is, their main business has weak cash generation capabilities and heavily relies on asset premiums in the public capital markets to maintain operations.
MSCI's qualitative standards have established clear isolation boundaries for traditional financial markets, officially cutting off the unconscious blood supply channel from passive capital to shell companies hoarding tokens. If indices like S&P, FTSE, and others follow suit with similar rules, the massive window for listed companies globally to absorb crypto assets using secondary market equity leverage will face comprehensive constraints from the underlying traditional financial system.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


