China International Capital Corporation Research
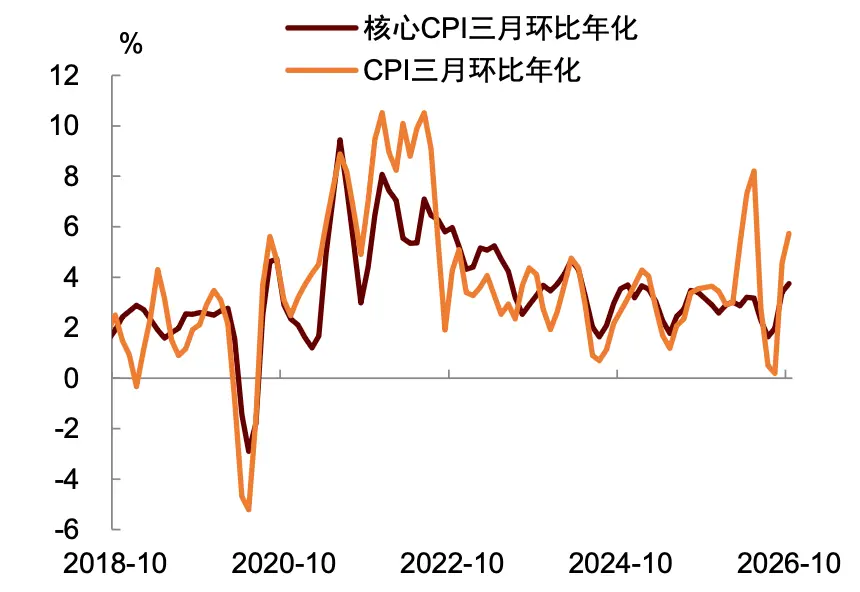
The U.S. October CPI seasonally adjusted increased by 0.4% month-on-month (last month 0.6%), and the core CPI increased by 0.3% month-on-month (last month 0.3%), both higher than market expectations. In October last year, the U.S. government shutdown prevented the release of economic data, resulting in the absence of year-on-year data. Overall, inflation remains sticky, with the core CPI rising for the third consecutive month by 0.3%, supporting the Federal Reserve's continuation of interest rate hikes. Recently, Federal Reserve Governor Waller mentioned that a 50 basis point interest rate hike in December cannot be ruled out. However, we believe that the Federal Reserve's policy is not significantly "behind the curve," and with financial conditions having marginally tightened, the necessity for accelerated rate hikes is weak. We maintain our baseline judgment of a 25 basis point rate hike in December, as this round of tightening is still relatively gradual and moderate.
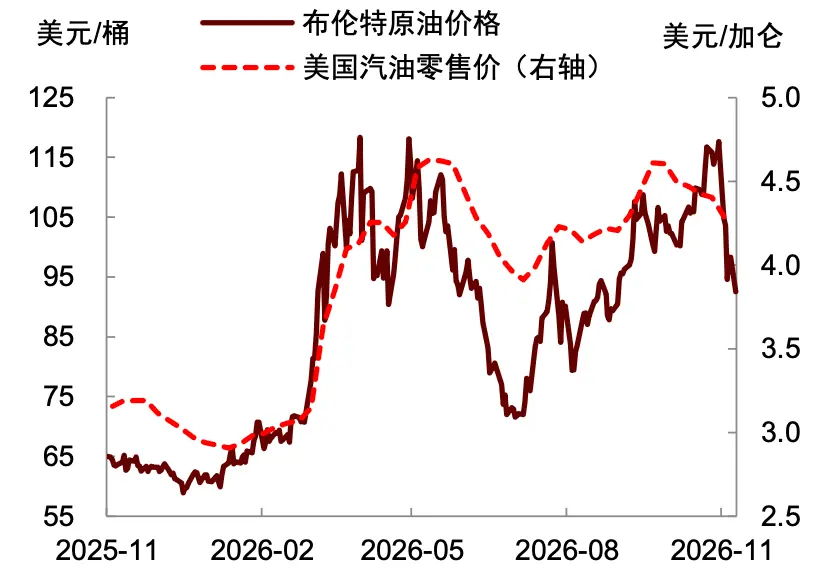
Energy inflation is marginally weakening, while food prices are accelerating. In October, the energy CPI increased by 0.7% month-on-month, a significant drop from September's 5.2% increase. Among these, gasoline prices increased by 1% month-on-month, and fuel prices increased by 2%, both significantly lower than the increases in September, while natural gas pipeline services fell by 0.8% month-on-month. However, electricity prices rose by 0.9%, marking the highest point since May of this year. Against the backdrop of data center construction and growing electricity demand, electricity prices may face some upward pressure.
The October food CPI rose by 0.5% month-on-month, the highest since May of this year. Among these, grocery prices increased by 0.4%, and dining out prices increased by 0.5%. The increase in food prices is broadly based, with price rises observed for fruits and vegetables, dairy products, and meat, not driven by any single category. This may have been influenced by the previous rise in energy prices being passed down.
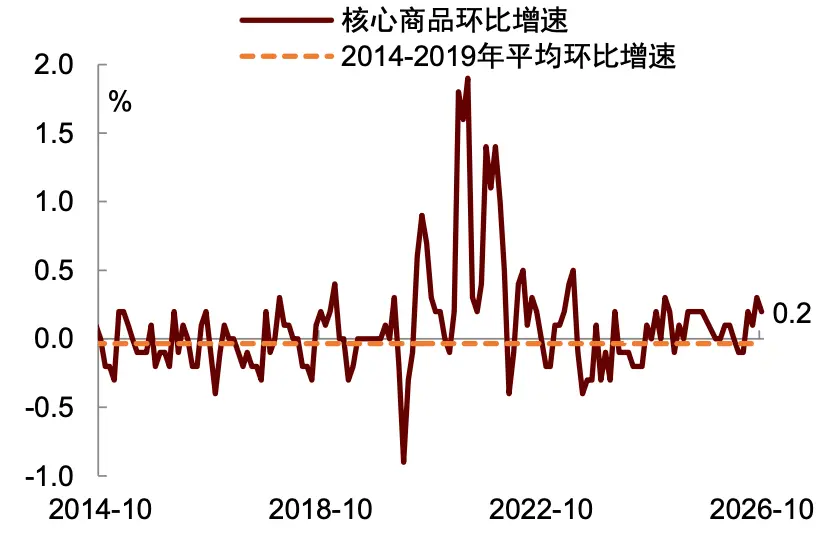
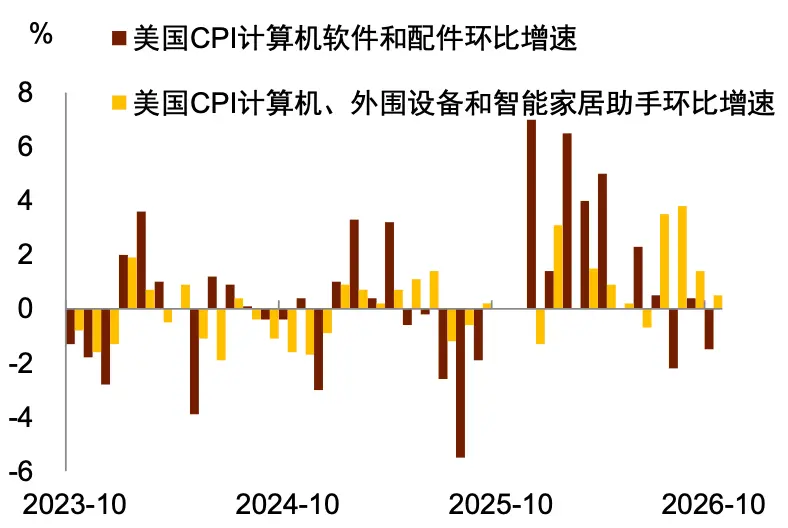
The prices of core goods are generally mild. Excluding energy and food, the core goods price increased by 0.2% month-on-month in October, slowing from September's 0.3%. Among these, new cars (0.2%), furniture (0.7%), and medical goods (0.5%) continued to rise, while used car prices fell by 1.2%, reaching the lowest level since February of this year. The prices of computer software and accessories decreased by 1.5%, and the price growth of computers, peripherals, and smart home assistants slowed from last month's 1.4% to 0.5%, indicating that AI inflationary pressures are marginally easing. However, prices for AI-related hardware are still rising, and subsequent inflationary pressures remain to be observed.
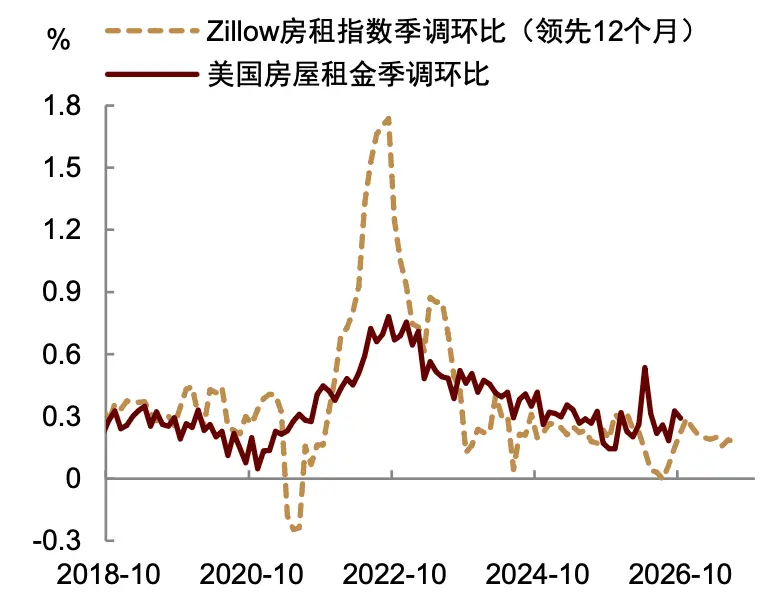
Rent inflation remains generally stable. In October, the housing CPI rose by 0.3% month-on-month, slightly down from September's 0.4%. Among these, Owners' Equivalent Rent (OER) rose by 0.3%, and actual rent increased by 0.2%, remaining steady compared to last month. From the forward-looking indicators of rent, there are no signs of accelerated rent inflation.
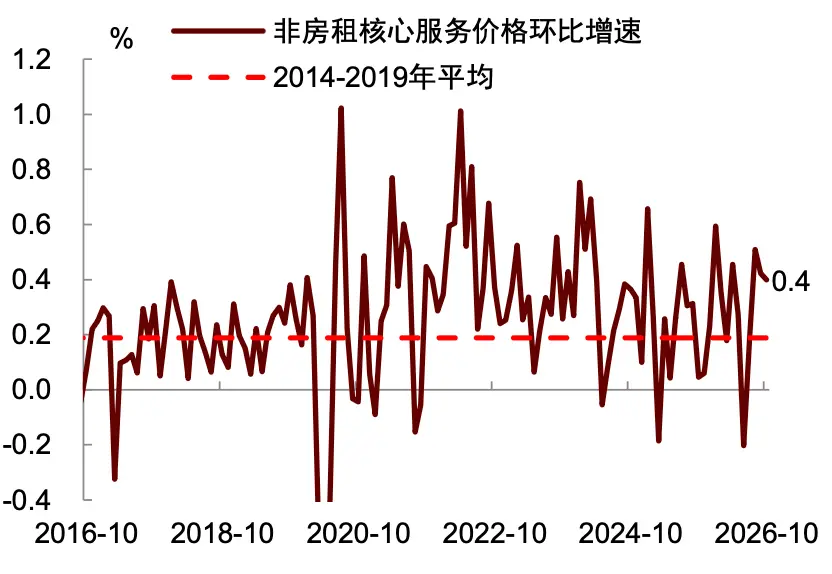
Non-rent core service inflation (supercore) remains quite sticky, with the rate of increase in transportation service prices widening. In October, non-rent core service prices rose by approximately 0.4% month-on-month, remaining roughly flat compared to last month. Among these, transportation service prices increased by 0.8%, higher than last month's 0.6%, but the structure of price increases has changed. Car insurance prices rose by 0.7%, public transportation prices increased by 2.0%, while air ticket prices slowed from last month's 1.2% increase to 0.4%. Additionally, medical service prices rose by 0.3%, and entertainment service prices increased by 0.9%, indicating that the sources of service inflation remain relatively broad and overall quite sticky. Looking ahead, as international oil prices have fallen recently, the pressure from energy costs transmitting to transportation and other service prices is expected to ease, but wage growth in manufacturing and construction has sped up, requiring attention to whether the rebound in labor demand will further push up wages in labor-intensive service industries, creating mutually reinforcing pressure between wages and service prices.
We believe that inflation pressures are relatively high, supporting the Federal Reserve's continuation of interest rate hikes, but the necessity for accelerated rate hikes is not strong. The October core CPI rose by 0.3% for the third consecutive month, indicating that inflation remains quite sticky, supporting the Federal Reserve's further tightening of monetary policy. We also maintain our previous judgment: the Federal Reserve will raise rates again in December.
Before the CPI data was released, Federal Reserve Governor Waller stated that if the October core CPI month-on-month reaches 0.3% or higher, a one-time increase of 50 basis points should be considered to maintain the credibility of monetary policy. This data meets the conditions he proposed, and the market is concerned about it. We believe that a more significant rate hike usually means a need to accelerate policy adjustments to compensate for previous insufficient tightening, but recent financial conditions have marginally tightened, indicating that previous tightening is already producing effects; at the same time, the month-on-month inflation growth for the past two months reflects more of a stickiness, with no signs of accelerated increases, and the Federal Reserve does not need to accelerate tightening. In fact, Waller himself also supported pausing rate hikes in the October meeting, as he should have opposed remaining static if he believed monetary policy was "behind the curve" at that time.
A possibility cannot be ruled out: with the recent midterm election results in, the Democratic Party has achieved a great victory, alleviating the pressure on the Federal Reserve, and some officials may prefer to take action early to ease persistently high inflation. However, whether there is a need for a one-time increase of 50 basis points still needs to be assessed. Even within the Federal Reserve, a radical rate hike strategy may not necessarily receive support from the majority of officials, as the previously most hawkish Dallas Fed President Logan only believes that there should be two more rate hikes of 25 basis points each. In conclusion, before more economic data is released, our baseline scenario remains a 25 basis point rate hike in December, with this round of tightening still being a gradual and relatively mild tightening cycle.
Chart 1: Core and Overall CPI Month-on-Month Annualized Upward Trend
Source: Wind, CICC Research Department
Chart 2: Recent Decline in Crude Oil Prices
Source: Wind, CICC Research Department
Chart 3: Slight Decline in the Month-on-Month Growth Rate of Core Goods Inflation
Source: Haver, CICC Research Department
Chart 4: Marginal Easing of AI-Related Inflationary Pressure
Source: Haver, CICC Research Department
Chart 5: Strengthening Stickiness of Housing Rent Inflation
Source: Haver, CICC Research Department
Chart 6: Slight Decline in Non-Rent Core Service Inflation
Source: Haver, CICC Research Department
[1]https://www.federalreserve.gov/newsevents/speech/waller20261110a.htm
[2]https://www.federalreserve.gov/newsevents/pressreleases/monetary20261028a.htm
Source
This article is excerpted from "Inflation Stickiness Remains, Supporting Continued Rate Hikes by the Federal Reserve," published on November 11, 2026.
Liu Zhengning Analyst SAC Certificate No.: S0080520080007 SFC CE Ref: BRF443
Xiao Jiewen Analyst SAC Certificate No.: S0080523060021 SFC CE Ref: BVG234
Lin Yuxin Analyst SAC Certificate No.: S0080526060003
Zhang Wenlang Analyst SAC Certificate No.: S0080520080009 SFC CE Ref: BFE988
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


