The market has fallen by 19%, while tokens with buyback plans have averaged a 62% increase.
Written by: WallStreetBets
Translated by: Luffy, Foresight News
2026 is a year where crypto projects generating revenue thrive.
From the beginning of the year to now, we have seen the total revenue of various protocols reach 11.68 billion USD. If November and December can perform close to October, this number should reach around 13.9 billion USD by the end of the year, which is less than 1 billion USD compared to 2025, when the market environment will be much better.
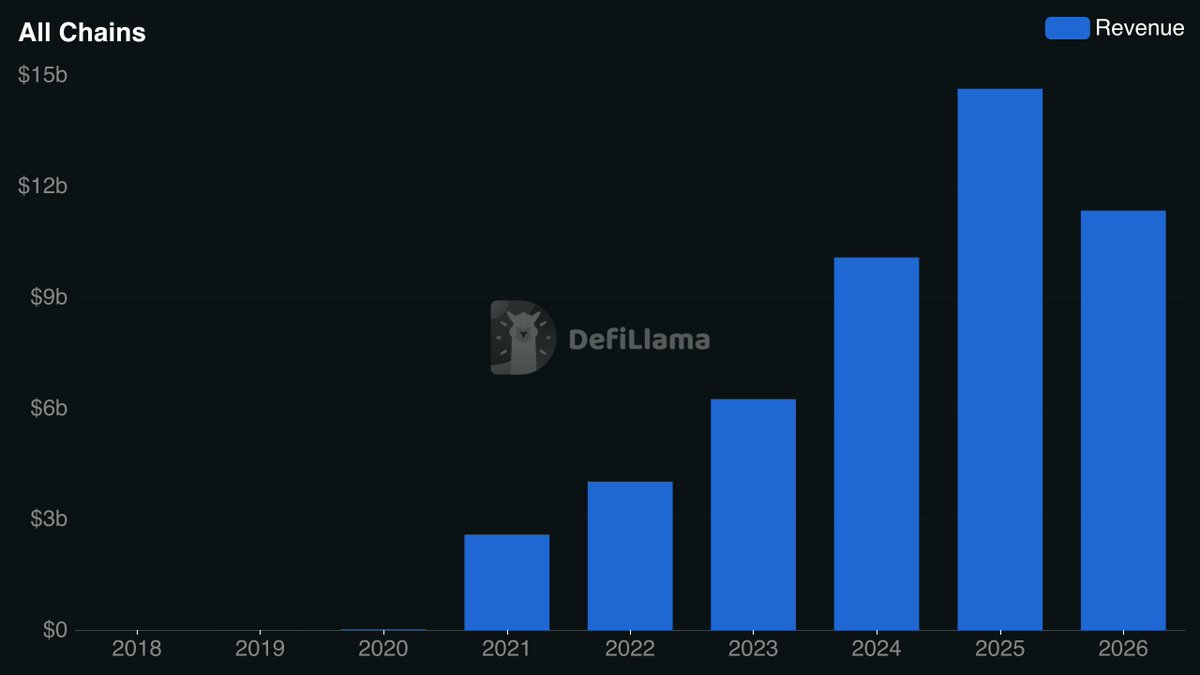
Annual revenue of crypto protocols
What we are witnessing is a trend driven by fundamentals, which is still gaining momentum despite the weakening market. Whenever I see this divergence, I want to figure out what drives it and, more importantly, where the investment opportunities are.
In this article, I will break down my findings, including:
- Why I believe the crypto "revenue narrative" is still in its early stages
- How to evaluate revenue-generating businesses and identify attractive token opportunities
- Why major teams from Hyperliquid to World Liberty Financial are embracing buybacks
- Where I am looking for the next wave of market-beating targets
The Basic Logic of the Revenue Narrative
Crypto has never been short of investment narratives, but the problem is that most narratives do not last long.
We have seen investors chase NFTs, the metaverse, SocialFi, and a succession of "public chain seasons." Money pours in, valuations soar, but the music always stops. When the music stops, all that remains for investors is massive losses.
These stories have one thing in common: market performance is driven more by narratives and speculation, with traditional business fundamentals carrying too little weight.
However, over the past few years, some changes in the industry are fundamentally changing how investors allocate capital.
Firstly, we now have a better understanding of "where blockchain creates real economic value and product advantages." After years of experimentation, some product categories have established clear product-market fit, and there are even breakthrough tracks like prediction markets and tokenization that have emerged from the industry bubble.
I also see more institutional capital flowing into this space through paths closer to traditional finance, such as DeFi vaults, rather than just for speculation; suits are more common at crypto conferences than hoodies; and regulatory progress in Washington has also made substantial advances.
Overall, the industry has matured quite a bit. As a result, the main allocators of capital influencing the crypto market are increasingly shifting from speculative, high-risk bets to supporting teams that are more aligned with traditional business fundamentals. This shift has significant implications for future investment trends.
As institutional investors and major capital allocators driving the market begin to prioritize sustainable business models, the investment narratives they drive will increasingly reflect the same priorities. This also changes the lifespan of narratives: when investment trends are driven by fundamentals, they have a better chance of sustaining investor interest across market cycles, especially when the underlying business continues to grow beyond the short-term price of the token.
If we are heading towards a new crypto bull market, this is where I want to position my portfolio: behind long-term trends driven by enduring demand that can compound over time.
This is also the reason I initially focused on the privacy track and now on the "revenue narrative."
The revenue narrative is an investment trend, centered around a class of growing crypto businesses. They have existing customer bases, sustainable income, and can translate business success into meaningful real value for token holders. As the industry matures and investors increasingly focus on business fundamentals, the argument is that these companies are likely to be some of the biggest winners in the next bull market.
What makes this opportunity particularly interesting is its breadth: unlike other narratives that center around specific technologies and applications, revenue creation spans every segment of the crypto market.
At first glance, the investment approach seems straightforward: applying the same fundamental analysis that investors have used for decades to assess successful companies. But in an industry still catching up to these standards, I believe investors willing to look beyond traditional financial metrics have additional opportunities.
The advantage here is that a successful crypto business does not necessarily mean its token is a successful investment.
This is because, unlike equity, most crypto tokens do not give holders legal ownership of the underlying business or its profits. Therefore, a protocol can generate hundreds of millions of dollars in revenue, yet this economic value may not flow to the token held by investors.
Thus, finding the best money-making business is only half the success.
The real opportunity lies in finding those businesses that can both maintain commercial success and have effective mechanisms to translate that growth into value for token holders.
This is where token buybacks come into play:
- In traditional stock markets, publicly traded companies buy back shares with excess cash to reduce the number of shares outstanding and increase the ownership proportion of remaining shareholders.
- Cryptocurrencies involve different economic and regulatory considerations. Unlike shareholders, most token holders do not have legal ownership in the business behind their tokens; explicitly tying token holder returns to the management efforts of a team could raise securities law issues.
- As a result, buybacks have become a popular mechanism for establishing a more direct relationship between "business success" and "token value."
The basic concept of buybacks is similar to traditional share buybacks. A protocol can use a portion of its revenue to buy tokens on the open market and then either destroy them, lock them up, or place them in treasury.
However, despite similarities to traditional finance, buybacks have been one of the most controversial topics in crypto over the past two years. Projects have spent hundreds of millions of dollars buying back tokens, yet the market results are often disappointing, leading many investors to question whether this strategy is even effective.
My perspective is different.
At this stage, I believe we have accumulated enough evidence to move beyond the debate of "are buybacks useful" and instead gain a clearer understanding of when, why, and under what conditions they are truly effective.
And that is what I want to clarify.
The Great Debate on Cryptocurrency Buybacks
The buyback strategy truly took off in 2025.
That year, 28 major crypto projects spent over 1.4 billion dollars buying back their tokens. However, only 3 tokens with buyback plans outperformed Bitcoin during their buyback windows (AAVE, HYPE, SKY), while many projects saw significant declines in their token valuations. Needless to say, 2025 made many projects realize that spending millions of dollars on buying back tokens did not necessarily translate into better market performance.
Many investors looking at the disappointing results of the 2025 buyback plans, especially the huge discrepancy between "money spent" and "token performance," concluded that this strategy simply didn’t work.
I believe this conclusion overlooks important context.
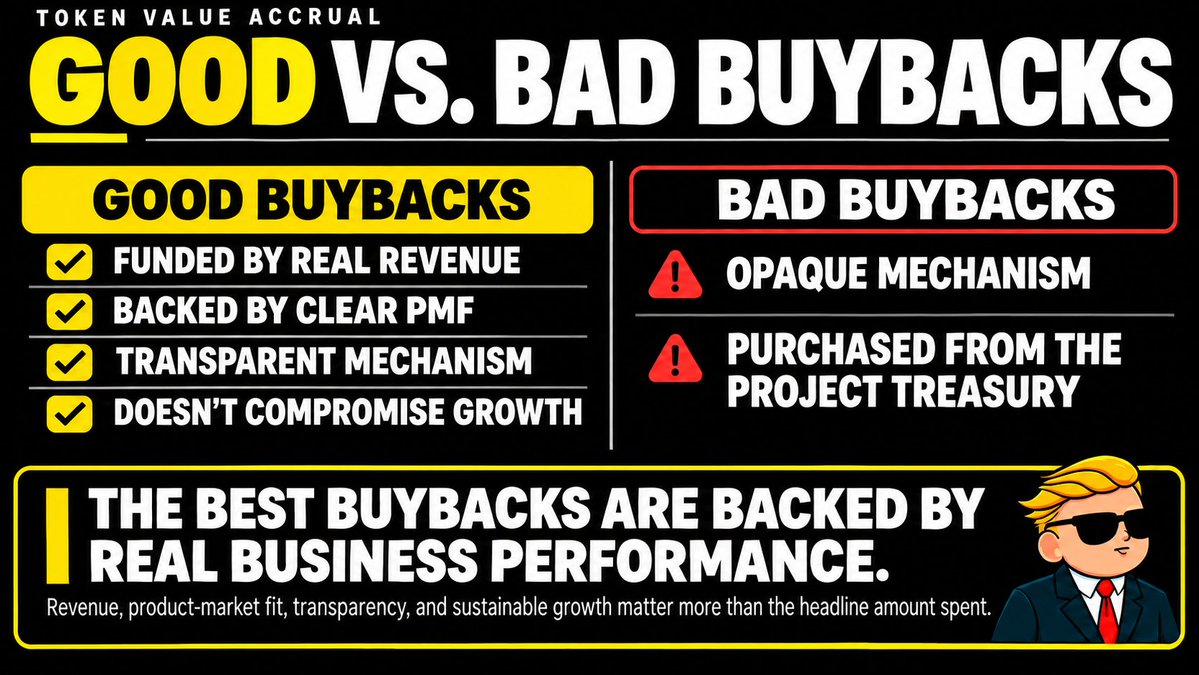
Rather than merely assessing the impact of buybacks on token prices, I am more concerned with what conditions they were executed under and where effective and ineffective buyback strategies differ. Based on this, I believe we can first establish four clear criteria for a "good buyback plan":
- Supported by revenue: The buyback is funded by real business income rather than existing treasury reserves or other unsustainable capital sources.
- Established product-market fit: The underlying business has demonstrated sufficient demand and repeatable revenue to support long-term buybacks.
- Transparent execution: Token holders can independently verify how the buyback mechanism functions, including the source of funds, execution process, and the destination of the bought-back tokens.
- Sustainable capital allocation: Funding for buybacks should not impair the ability of the company to reinvest for growth, maintain financial stability, or seize higher return opportunities.
Beyond these fundamental standards, several other factors will affect the effectiveness of buyback plans, worth considering when evaluating projects:
1) Market Environment
Jupiter is probably the most cited case of "buybacks failing to deliver expected market performance."
In February 2025, the platform began allocating 50% of its on-chain protocol revenue to buy back JUP. By January 2026, the team had spent over 70 million dollars buying back tokens, but JUP continued to fall sharply.
This disappointing performance prompted Jupiter's co-founder Siong Ong to speak out and shift funds back to business growth. The plan was ultimately extended.
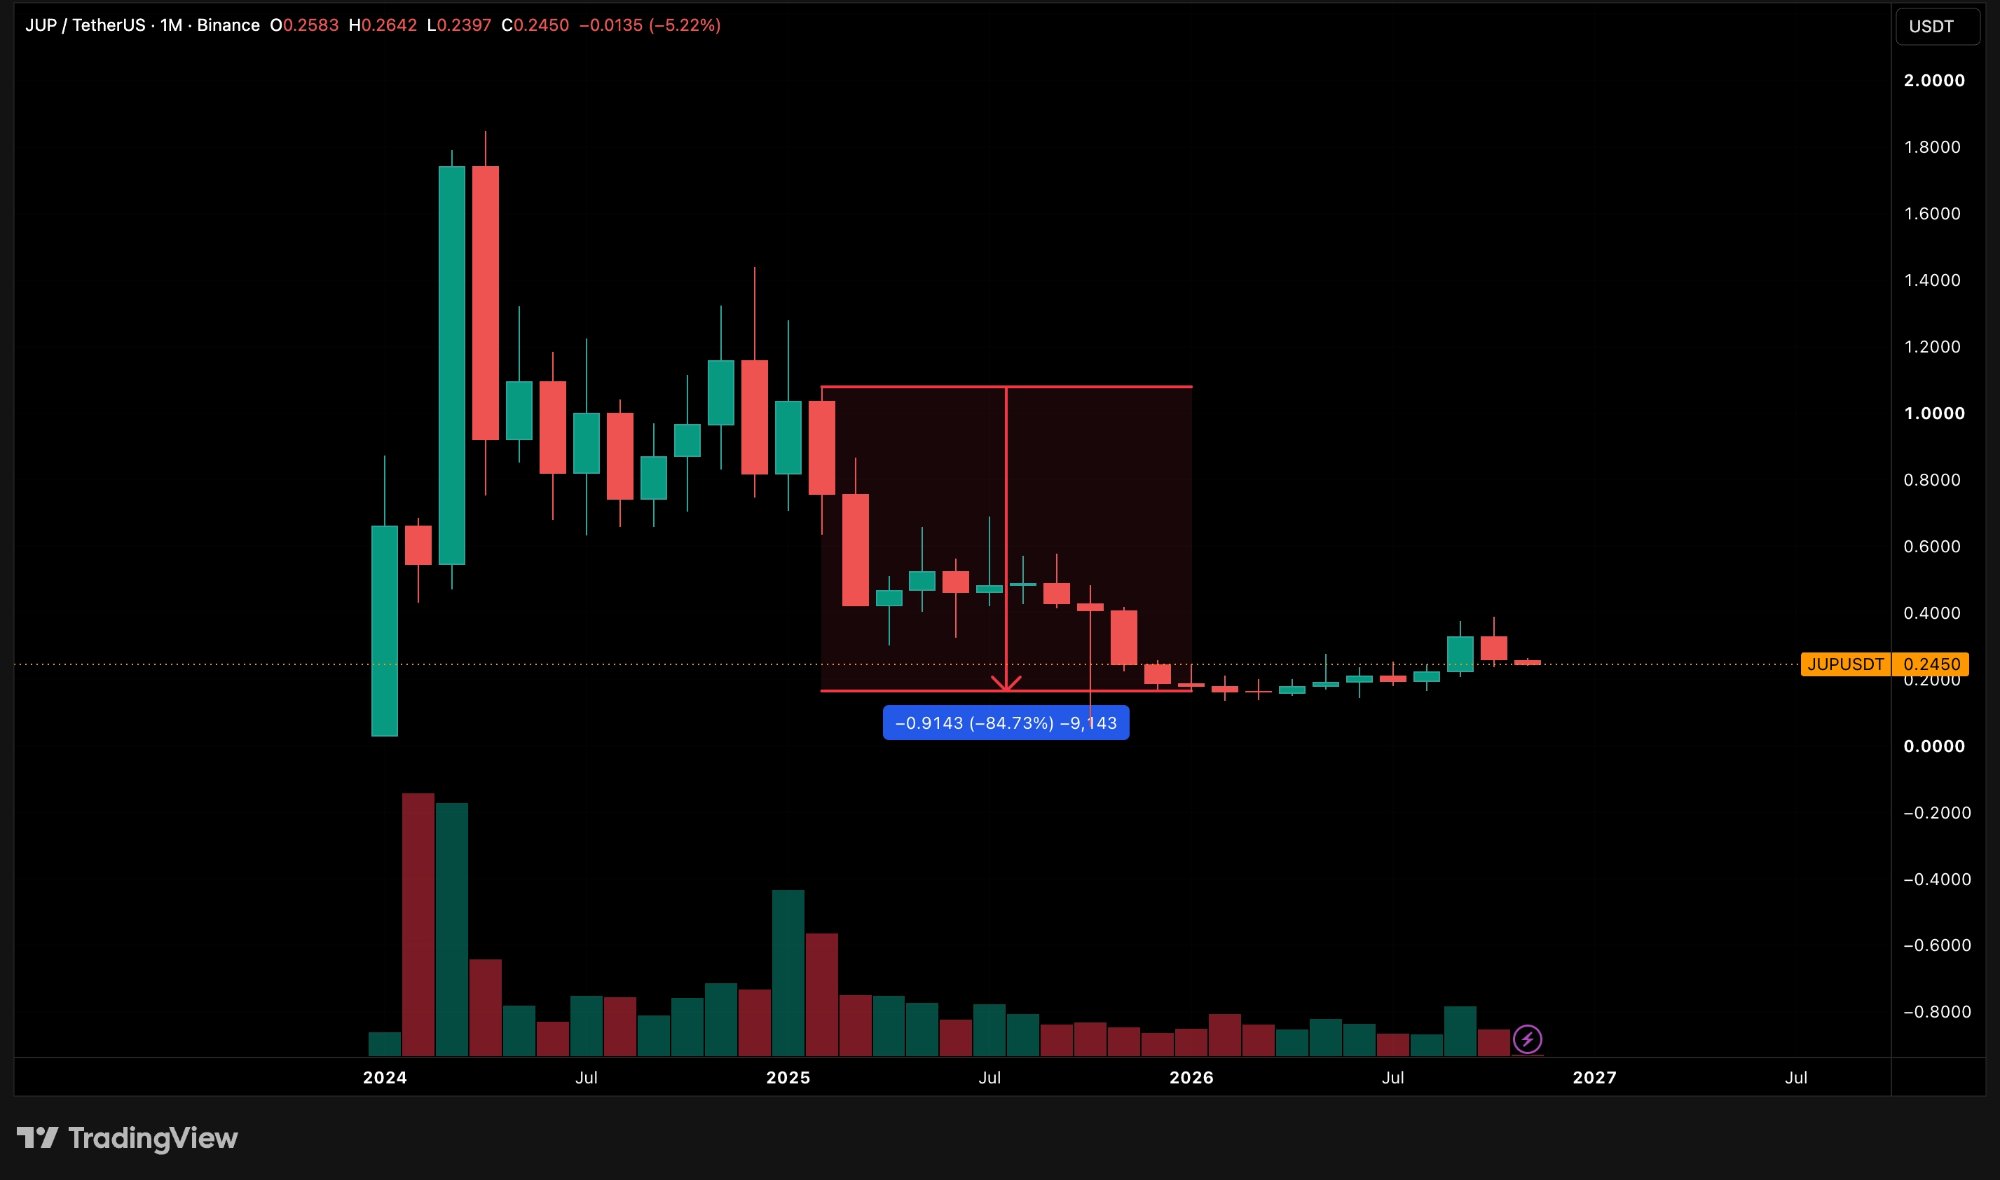
Criticism surrounding Jupiter's buyback has focused on its inability to support JUP's price, leading to the question: Would the team have been better off using that money to grow the business?
But I believe it is more critical to look at what market conditions these buybacks occurred under.
January 2025 was the peak for many targets in a cycle of the Solana ecosystem. After that, SOL fell from a high of 294 dollars to 96 dollars. Around the same time, major Solana protocol-related tokens such as Sanctum, Kamino, and Jito all fell more than 80%, while well-known meme coins like Fartcoin and WIF dropped over 90%.
In other words, Jupiter spent more than 70 million dollars buying back JUP during a period of extreme selling pressure across the entire Solana ecosystem. The lesson is: buybacks can create significant demand for tokens, but even large-scale purchases may struggle to offset a broader long-term market downturn.
Sometimes, no matter how fast you row, you cannot outpace the tide.
2) Token Issuance
Another important consideration is: how large is the newly circulating supply of tokens compared to the amount bought back?
A protocol can spend tens of millions of dollars on buybacks, but if the supply from token unlocks, emissions, and other distributions exceeds the amount absorbed by the buybacks, the effects will be drowned out.
Research by Bill Hsu shows a negative correlation between token supply growth and relative market performance. Fundamentally, what matters is not how much a team spent on buybacks, but whether those purchases genuinely improved the supply-demand dynamics of the token.
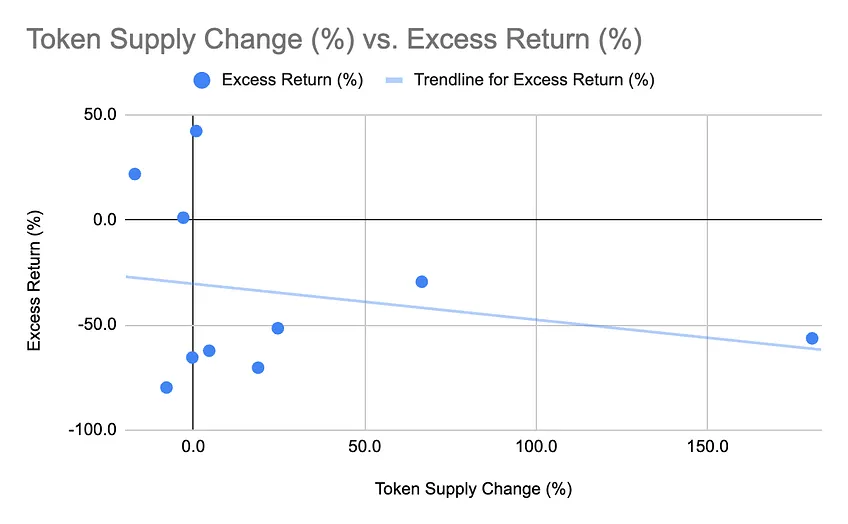
Change in token supply of the top ten crypto buyback plans in 2025 vs. excess returns relative to Bitcoin. Source: Bill Hsu
3) Buyback Mechanism Itself
Many crypto protocols commit a fixed percentage of revenue to automatic buybacks, regardless of token valuation. While this certainly creates predictable demand and shows a clear commitment to token holders, it may not be the most efficient way to allocate capital.
This is not the practice in traditional stock markets.
For example, Buffett's Berkshire Hathaway has historically bought back shares while maintaining sufficient liquidity. The logic is to buy back shares when they are undervalued, and retain capital when valuations are high or there are better investment opportunities.
I understand the appeal of "programmatic buybacks" in crypto, especially when many tokens—particularly those supported by solid income businesses—seem cheap for quite some time due to extended market downturns.
However, as the market environment improves and valuations expand, I expect more teams to shift towards discretionary buybacks that take into account token prices, growth opportunities, and broader capital allocation priorities.
Ultimately, the goal should be to maximize the long-term value for token holders, not simply to maximize buyback expenditures. As investors, your job is to assess which teams' practices are the most effective.
Fortunately, we now have an increasing amount of market data to assess which buyback methods are truly effective. And the performance in 2026 provides strong evidence for "taking buybacks supported by revenue seriously."
Buyback Performance in 2026
Cryptocurrency buybacks have had another remarkable year this year.
Various projects have spent over 900 million dollars on token buybacks and related destruction mechanisms, with Hyperliquid and Pump.fun accounting for the vast majority. Uniswap, Jupiter, and Sky are also worth noting.
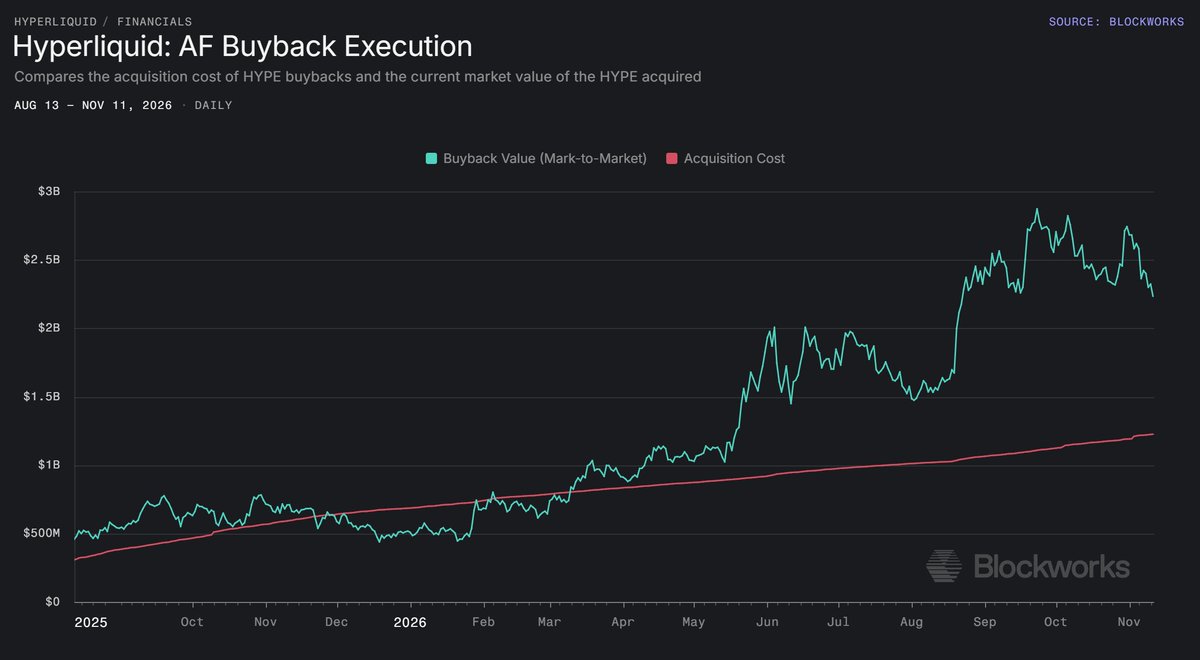
Hyperliquid's buyback tokens are in profit
Most importantly, many tokens associated with these plans have delivered impressive returns this year.
For example, looking at the 30 protocols with the highest revenue over the last 30 days: nearly half (14 projects) do not have publicly traded native tokens, among the remaining 16 projects with investable tokens, 12 have active buyback plans:
- 9 have positive year-to-date token returns
- 3 have negative year-to-date returns
- Average return this year +62.2%, median +32.6%
In contrast, 4 projects without active buyback plans:
- 1 has positive returns this year
- 3 have negative returns
- Average return this year −31.6%, median −31.5%
The average year-to-date performance gap between the two groups is a staggering 93.8 percentage points.
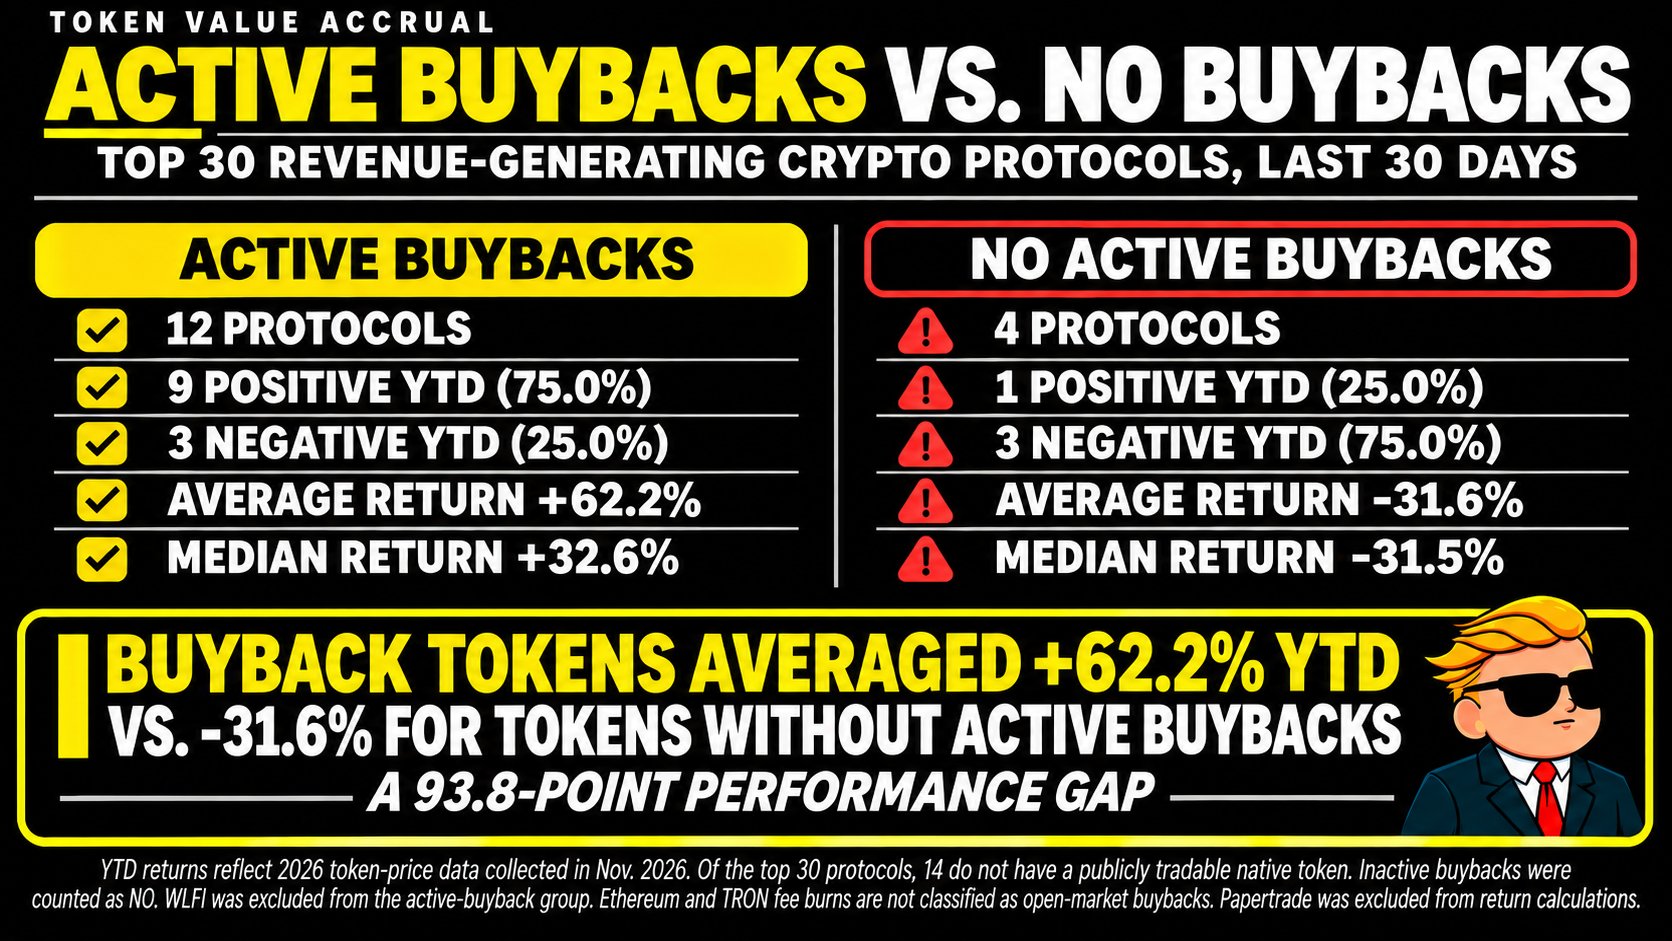
Even more impressive is that these token performances occurred against the backdrop of an approximately 19% decline in total crypto market capitalization this year.
With results like these, I am not surprised when revenue-strong teams announce their embrace of buybacks. For example, World Liberty Financial just launched its WLFI buyback plan last week, and I expect more teams to follow suit in the first quarter of next year.
It is also important to compare this year's buyback performance with other value distribution strategies—especially those distributing revenue directly to token holders.
In September, research from DeFiLlama compared the performance of "tokens with buyback plans" versus "tokens directly allocating income to holders."
The conclusion was: year-to-date, the median return of tokens with buyback mechanisms was 19.7%, while tokens employing direct income distribution returned 11.1%.
When researchers weighted these returns by market capitalization, the gap widened significantly: buyback tokens +190%, directly distributing tokens +29%.
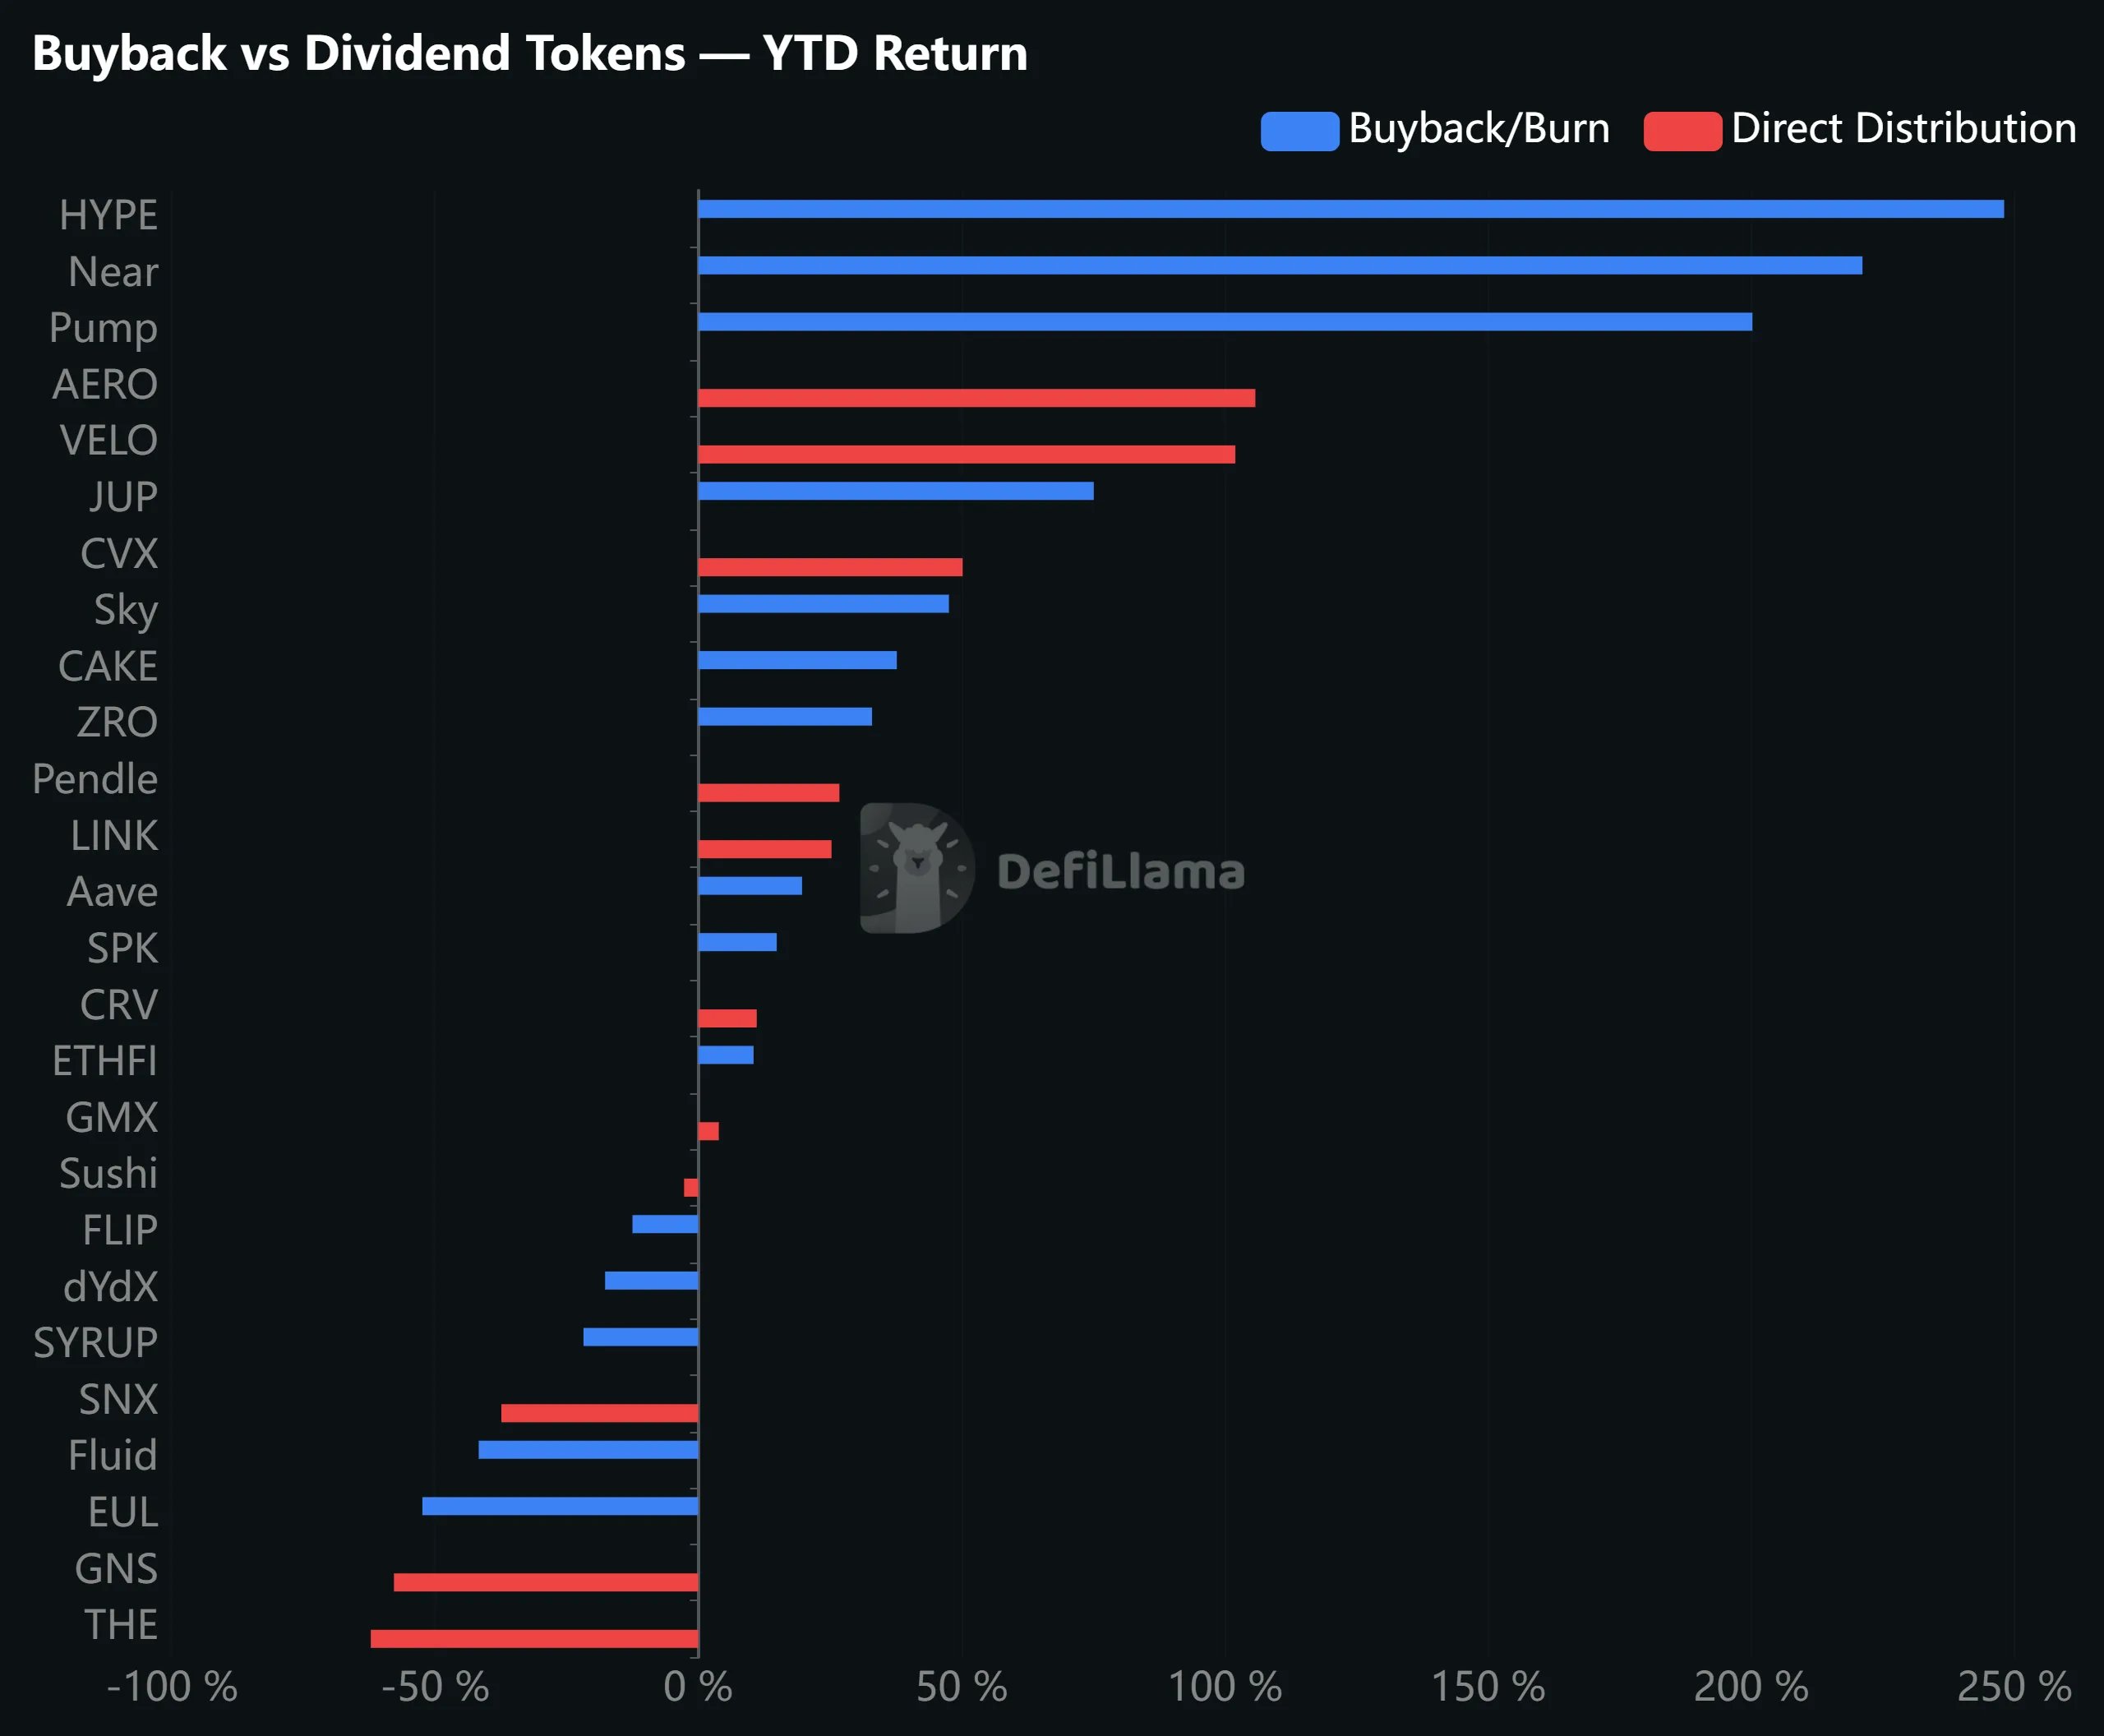
Buyback tokens outperform direct distribution tokens on average
We also see a positive shift in the proportion of protocol income flowing back to token holders.
The same study showed that as of September 2026, crypto protocols had achieved monthly income exceeding 1 billion dollars for 23 consecutive months. Two years ago, about 5% of that flowed to token holders; by September, that proportion had tripled to 15%, reflecting the growing prevalence of income distribution mechanisms.
So, summarizing the lessons from 2026:
- Teams with buybacks are significantly outperforming in open markets
- Buybacks are outperforming other income distribution models
- Increasing crypto business revenue is being allocated to tokens, suggesting this trend will continue
What I Am Watching
For me, future opportunities lie in identifying those crypto businesses that are "doing buybacks the right way," especially those situated in segments with long-term growth potential.
Let’s look at a few directions worth exploring.
1) Where the Money is Flowing
Our analysis of the 30 highest revenue crypto protocols identified 9 projects that have active buybacks and positive year-to-date token returns.
If these businesses can deliver strong performances in adverse market conditions, I think there is significant imaginative space for what they can achieve when the market bull returns.
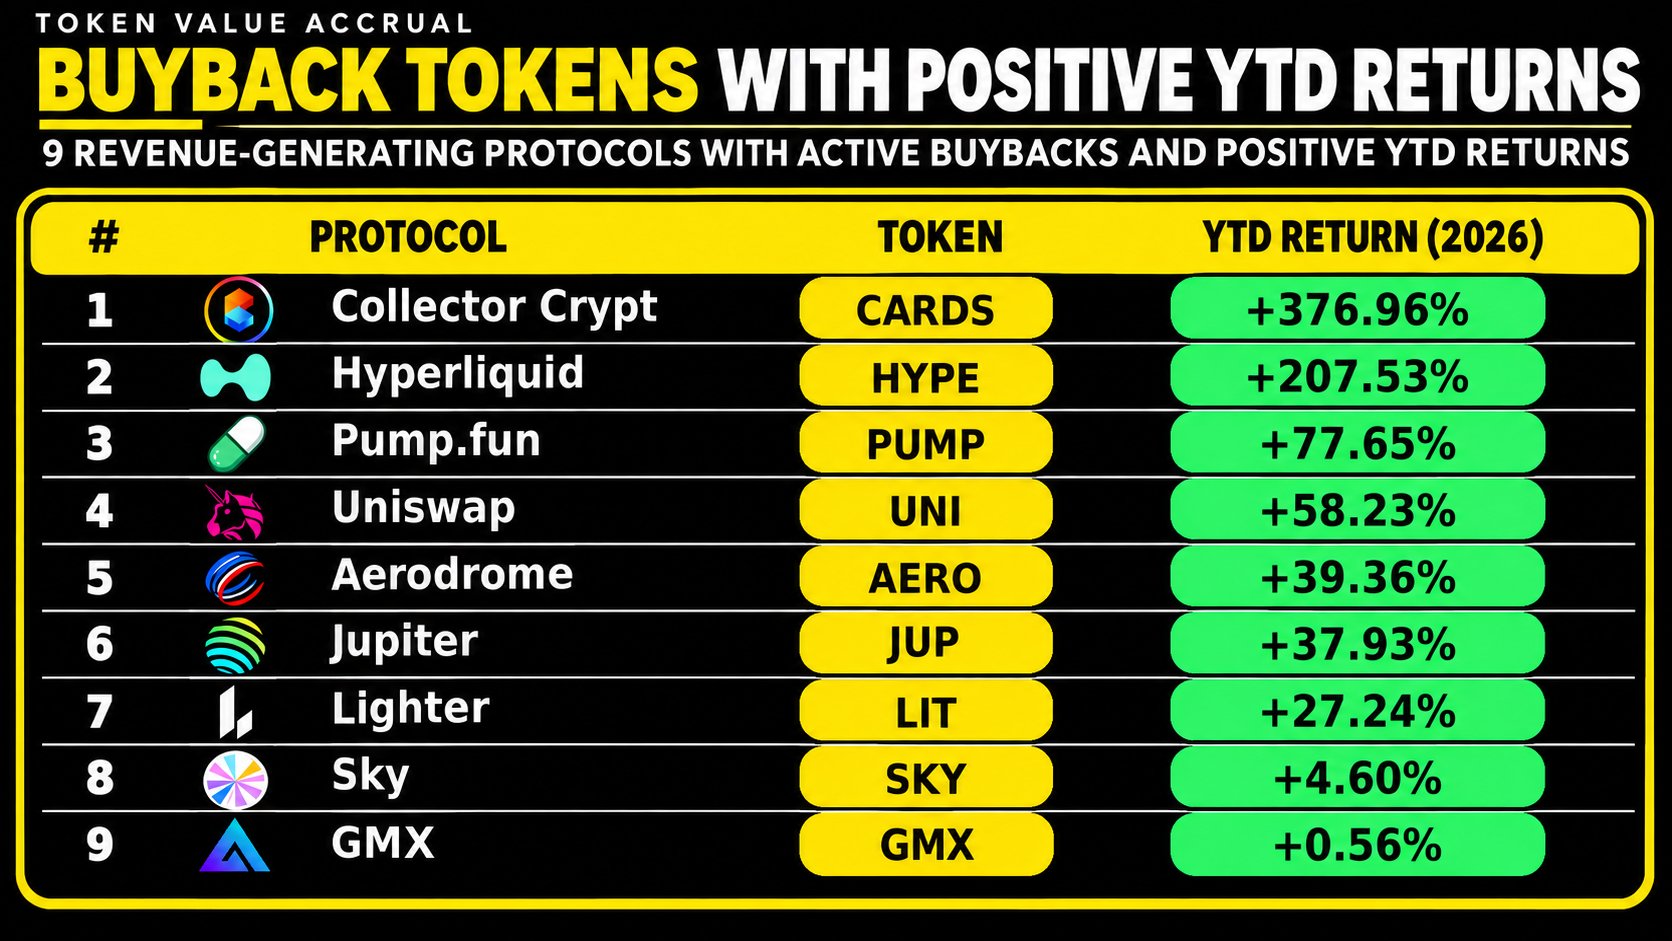
Beyond individual protocols, it is also vital to examine where broader crypto industry revenue is generated. These segments are most likely to have conditions conducive to successful buyback plans.
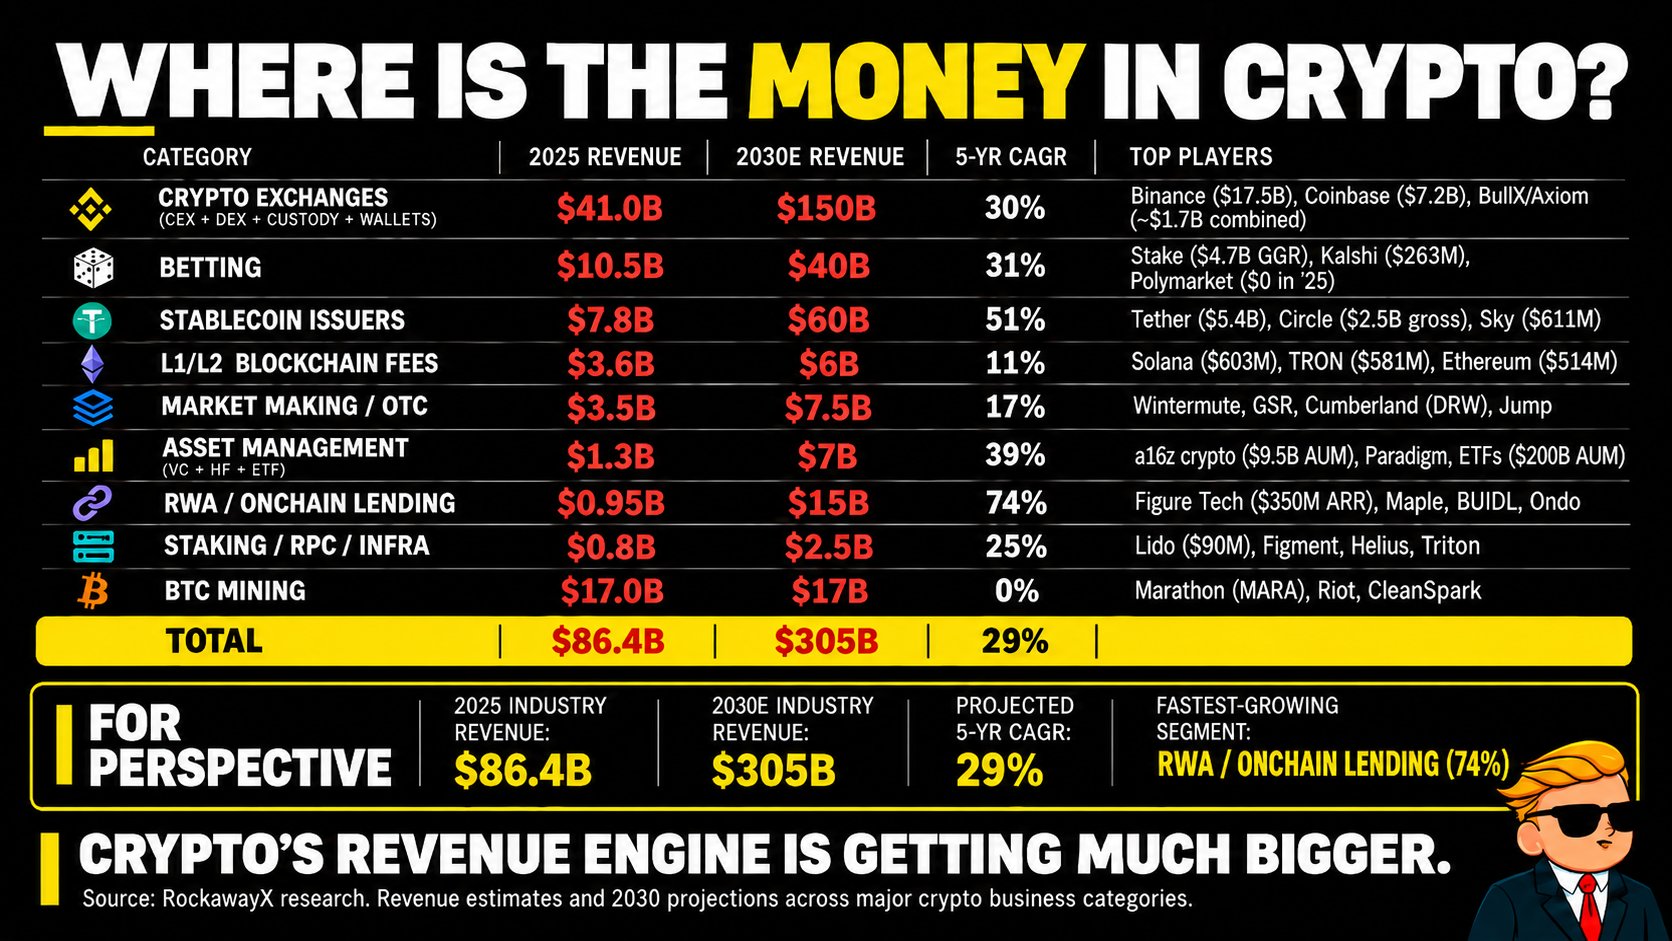
In 2025, the crypto industry was estimated to generate 86.4 billion dollars in revenue; by 2030, this figure is projected to reach 305 billion dollars.
In the future, the fastest-growing segments are expected to be stablecoins and RWA lending: research predicts annual revenues of 60 billion dollars and 15 billion dollars respectively in 2030. These two sectors are ones I will focus on.
2) World Liberty Financial
Until now, the opportunities for investors to directly capture the economic upside of the stablecoin revolution have been relatively limited. I have always believed that stablecoins are one of the strongest product-market fit cases in crypto and have the potential to fundamentally reshape global finance.
Companies and protocols like Tether, Circle, World Liberty Financial, and Ethena have proven that stablecoins are not just a use case for blockchain technology but the foundation for building billion-dollar businesses. However, despite explosive growth, the opportunities for investors to directly participate in the value created remain quite limited.
Looking at the existing landscape: Tether remains private; Circle has gone public, but it shares a significant amount of revenue with distribution partners; Coinbase captures part of the economics of USDC, but its stock represents a broader business. Meanwhile, holding XRP or PayPal stock does not provide direct exposure to the income generated by RLUSD or PYUSD.
This is where World Liberty Financial's newly launched buyback plan catches my attention.
By allocating a portion of the income related to USD1 reserves (over 150 million dollars annually) towards its buyback plan, World Liberty Financial is establishing a more direct connection between the economic success of the stablecoin business and the demand for WLFI tokens, allowing token holders to benefit as USD1 adoption increases.
As the circulation of USD1 expands, reserve income will also grow, creating more resources for buybacks. In my view, this is the most direct attempt to connect the "economic of stablecoin issuers" with "publicly traded tokens" to date.
3) Venice
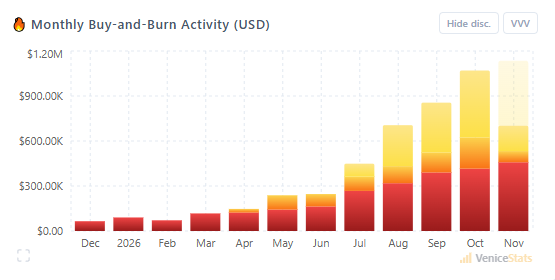
The privacy-oriented AI platform AskVenice recently surpassed 4 million users, with annual revenue exceeding 100 million dollars. On November 9, the company executed a buyback, removing about 458 thousand dollars worth of tokens from circulation.
At the same time, automated burns funded by new subscriptions and API quotas saw a month-on-month increase of 40% in October. In October, Venice burned approximately 1.07 million dollars worth of VVV, with November expected to achieve a new high of 1.14 million dollars.
What I find particularly interesting about Venice is that few crypto-related businesses achieve this level of commercial success outside the industry.
This year, other investors have also taken notice. Their support, combined with Venice's own buyback, has driven VVV prices up over 1200% this year.
4) Bittensor
Thus far, the example of Bittensor demonstrates how buybacks can benefit individual projects, while its implementation across the entire ecosystem illustrates what can happen. I have not seen this level of commitment to buybacks in other places within the crypto industry.
Bittensor operates through a "subnet" network, where you can consider subnets as individual tech startup companies competing for the release of TAO tokens. The market demand for each subnet's unique alpha tokens (the startup's own native cryptocurrency) plays an important role in determining how emissions are allocated, so token performance may directly relate to the team's sustainability.
As a result, buybacks, burns, and emission management become central to subnet strategies. This ecosystem has turned into an ongoing experiment in token economics; I believe any team considering buybacks, regardless of whether they are on Bittensor, is worth studying.
According to Subconnect data, as of August 2026, 14 out of 24 subnets with external income have already funded their alpha token buybacks with revenue. These 24 subnets collectively project annual revenues between 28 million and 35 million dollars.
A recent interesting example comes from Targon, currently the third largest subnet by market capitalization in Bittensor.
On October 27, Targon reported destroying approximately 2.1 million dollars worth of alpha tokens (SN4), of which about 445 thousand dollars were from new buybacks; this activity was funded by revenue from its AI computing business.
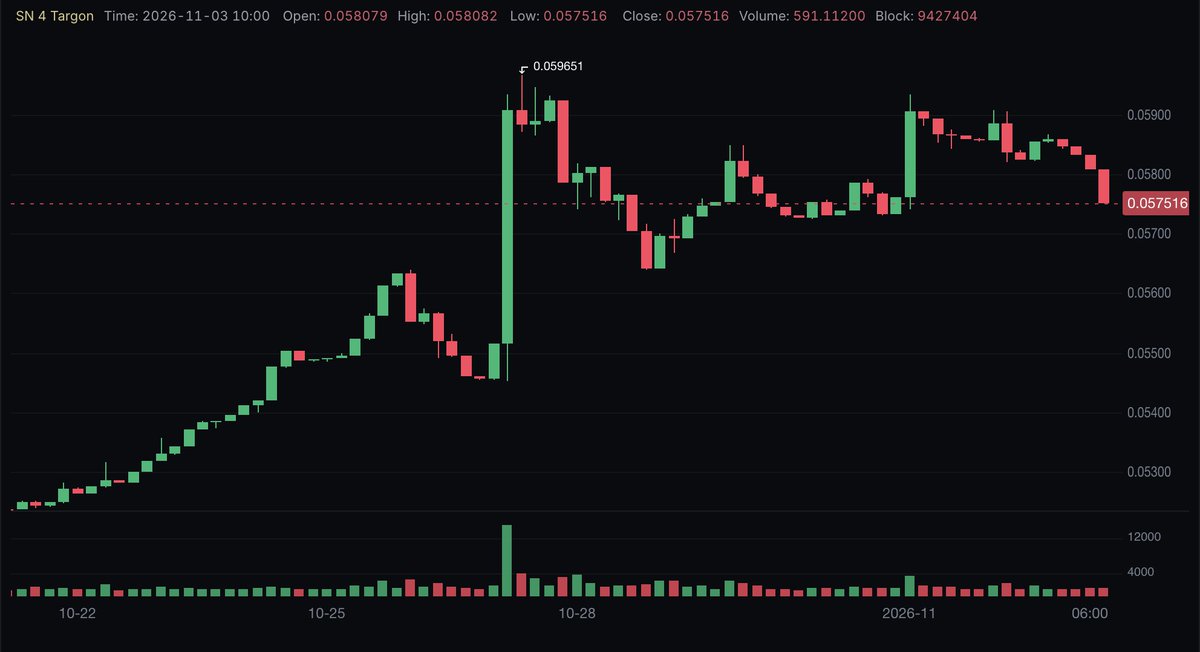
Targon SN4 price trend
Within seven hours of the announcement, SN4 surged over 13% on the weekly chart. Even in the backdrop of a market decline, as of the writing, the token remains about 3% higher than its pre-announcement price.
I believe this provides an early sample for how the broader crypto market may evolve when buybacks become more prevalent.
5) Robinhood Chain
Robinhood Chain is another ecosystem worth watching for buyback innovations, especially those involving tokenized RWAs.
Longdotxyz is leading some of these experiments. In September, the platform launched LONG 500, a mechanism designed to connect community tokens with tokenized stocks through a sharing economy model.
It works as follows:
- 5% of the fee from newly generated stock tokens flows into the AI community treasury, accumulating tokenized stocks in the shared reserves.
- Another 5% is used for the buyback and destruction of the community token paired with each stock, which anyone can trigger.
The interesting part of this approach is that LONG combines token buybacks with the accumulation of real financial assets. As more stock communities come online and generate trading activities, this system can simultaneously reduce the supply of participating community tokens, support liquidity, and allow for the growth of the entire ecosystem's asset reserves.
This is a more complex value accumulation method than simply allocating protocol revenue to buy back native tokens, creating a model that allows growth in various markets to feed back into a broader ecosystem.
In the future, I expect to see far more of these types of experiments on the Robinhood Chain.
What Happens in a Real Bull Market?
We have spent years observing how the crypto market rewards narratives, speculation, and commitments to future adoption. Today, the revenue narrative has fully emerged, and we see an industry that possesses business activity and financial performance enough to support a more fundamentally driven investment landscape.
Despite a relatively unfavorable market situation, several leading revenue-generating crypto protocols have still delivered impressive token returns, expanded user bases, and continued to create substantial income.
Now, imagine what happens when these conditions change.
For these businesses, increased adoption and market activity will translate directly into more revenue. And when a significant portion of that income funds token buybacks, the resulting demand can grow alongside the protocol itself. When combined with improved market sentiment and capital re-entry, the potential for excess returns becomes quite attractive.
In that scenario, buybacks will no longer simply help teams stay afloat in harsh environments, but will feel more like pouring gasoline on an already thriving fire. Not to mention, if the prediction of the crypto industry reaching revenues in the hundreds of billions by 2030 comes true, it means there remains tremendous economic value yet to be created.
That is why I believe the "revenue narrative" in crypto is just beginning.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


