Author: nikos, focused on DeFi, Vaults, and RWA, previously worked at BitstampUK, InfraredFinance, and Fuel Network
Translation: Gu Yu, ChainCatcher
A payment fintech company can today borrow 30 million USDC in a single transaction on Aave or Morpho. What it cannot secure anywhere on-chain is a promise: this 30 million dollars will be there tomorrow morning and every morning for the next year, at a price it already knows. This promise is exactly the product sold to it by banks and is the piece that the lending stack has yet to build.
Yesterday, I broke down fixed-rate working capital: how TradFi funds it, how Aave V4 Spokes, Avon, and Morpho Midnight will accommodate it, and where their respective shortcomings lie. This piece discusses what should be built upon it. It addresses still unresolved issues, a four-layer product, and where the moat will fall.
What Remains Unresolved
Four gaps are identified from the comparison, each located one layer above the lending market.
No one promises capacity. A V4 Spoke limits how much a borrower can draw, but nothing guarantees liquidity will be there when it draws. Quotes signed by Midnight lenders can be canceled at the last moment when borrowers need them. Avon will route to any quoting party. A fintech company that pre-funds 10 million dollars every day needs that limit to exist even on its worst days, which is the day lenders withdraw.
Isolation stops at Spoke. On V4, a loss from an unrecouped Spoke affects every supplier of that asset in the Hub. On Midnight and Avon, the loss remains in one market where the lenders bear all the losses. Neither sets a first-loss layer between borrowers and priority capital, which is exactly how every warehousing credit line and conduit is constructed in TradFi.
The founder's capital floats among its holders. About 600 million dollars of tokenized working capital credit is held by those cycling it with floating USDC debt. When borrowing rates skyrocket, they sell, and the founder loses what they thought was stable funding. The fixed-rate market can only resolve this if it is deep enough over the right period. Setting a cap on borrowing rates can resolve it without such depth; however, there is no running product offering this cap against Aave or Morpho borrowing rates.
Accounts receivable cannot be liquidated within an hour. On-chain liquidation assumes there is a price and a buyer. Accounts receivable tokens come with a NAV report and a redemption queue measured in days. The tools used by banks (stopping advances, taking over collections, allowing asset pools to naturally expire, selling to pre-arranged buyers) currently have no on-chain equivalent.
What the Foundation Layer Has Already Achieved
Most of the tough mechanisms already exist.
The previous two attempts set benchmarks. Wildcat allows borrowers to set their own terms (capacity, APR, reserve ratio, withdrawal period) in their own markets. When Kinto defaults in 2025, it will be the first default since 2023, leaving losses in that market, with lenders expected to recover 76% of principal. 3Jane provides an unsecured USDC limit backed by on-chain data and bank data, allowing undrawn funds to earn yields on Aave, splitting lenders into 85% priority and 15% subordinate. Both prove parts of the tech stack are feasible. Neither sells promised capacity to fintech companies, does not route between V4 and Midnight, nor operates in conjunction with accounts receivable collateral.
Four Layers
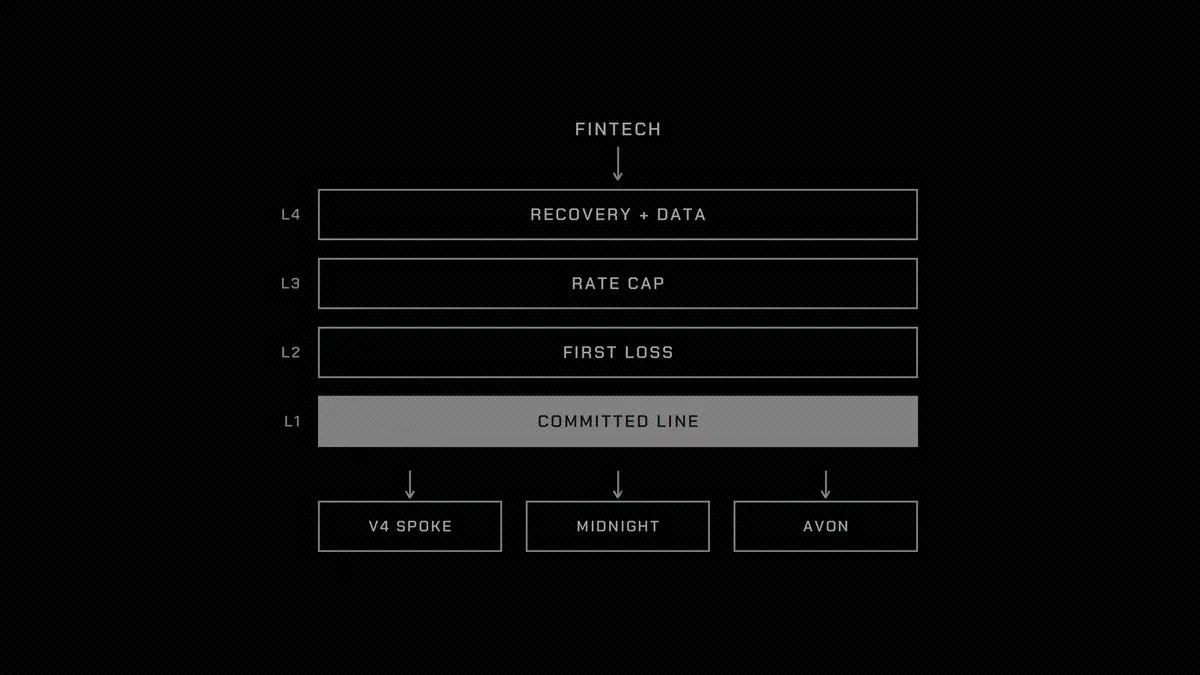
This product is a credit platform situated between fintech borrowers and the lending market, constructed into four layers, each capable of operating independently, and collectively stronger.
Layer 1: Committed Capacity
A financing facility is a treasury with an authorized scope. Depositors fund it, and it commits to a borrower to provide up to X, either at a spread above a reference rate or at a fixed rate, over a 6-12 month period, through APIs for withdrawal and repayment. Undrawn funds are placed in the deepest floating market, earning the market's rate. Each withdrawal goes to the cheapest place for that collateral and maturity: a dedicated V4 Spoke or a Midnight market with a due date matching that withdrawal's due date. Borrowers pay the spread on the drawn portion plus a commitment fee on the undrawn portion, which is what makes this commitment worth adhering to.
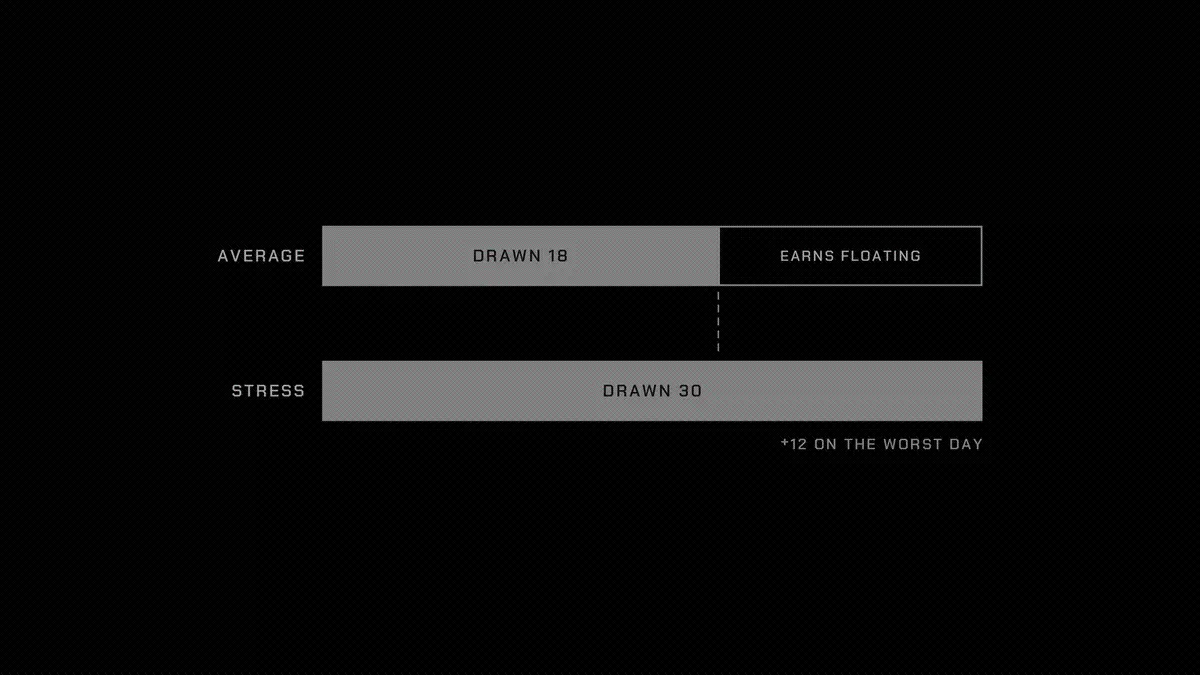
On a financing facility providing an average of 60% draw on 30 million dollars, the spread is 4%, and the commitment fee is 0.5%, resulting in depositor earnings relative to the floating rate of
60% × 4% + 40% × 0.5% = 2.6%
or 780,000 dollars annually. The risk is from the option the treasury has already sold. Borrowers tend to draw the most when under stress, thus the financing facility must withstand a jump from 18 million dollars to the full 30 million dollars on the worst day. This means determining the size of the commitment based on the liquidity the treasury can draw from the floating market under stressed scenarios, not based on average usage. It also means that withdrawal queues cannot block an already committed draw.
Layer 2: First Loss of Each Financing Facility
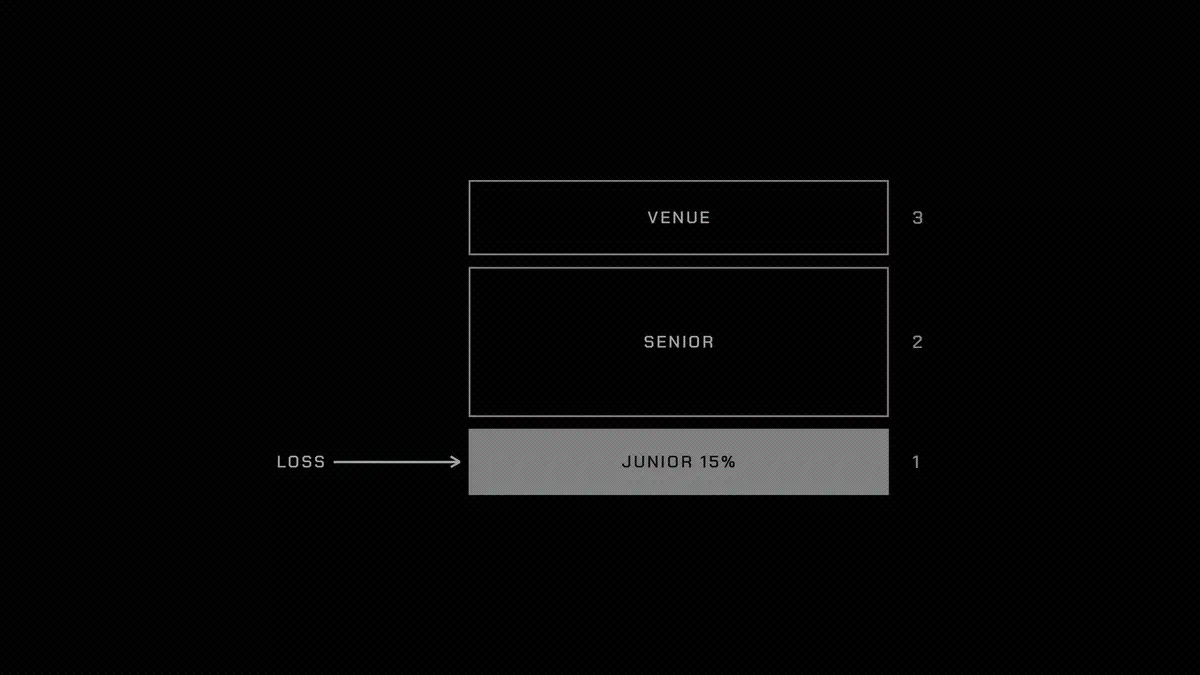
Each financing facility has a subordinate layer that absorbs losses prior to the priority depositors and also before its Hub or market. It is the equity layer of the warehousing credit limit, formalized and placed on-chain. It can be contributed by the initiator, specialized credit funds, or both parties together.
Setting the subordinate layer's size to 15% of the drawn amount, that is 2.7 million dollars on an 18 million dollar drawn amount, earning it 60% of a 720,000 dollar spread. It earns
432,000 ÷ 2,700,000 = 16%
above the floating rate. A 5% loss on the drawn book, that is 900,000 dollars, would take away a third of it, while there would be no loss on the priority side. On V4, the subordinate layer makes the isolation of Spoke from Hub suppliers real. On Midnight, it enables a screened treasury to provide priority claims to depositors for a given market, otherwise they would bear all of that market's risks.
Layer 3: Cap on Borrowing Rates
When the borrowing index at a certain venue runs above the strike price, the cap pays its holders:
payoff = max(0, r_b − K) × N × t
At a strike price of 7%, if the USDC borrowing rate averages 9% over 30 days for a nominal principal of 100 million dollars, the cap pays
100,000,000 × 2% × 30/365 ≈ $164,000
If most of a founder's tokens are held cyclically, it can purchase caps for its holders that pay out when borrowing rates soar, rather than forcing them to sell. The sellers are those who naturally go long on high rates: floating-rate lenders, fixed-rate treasuries, and idle funds of the financing facility itself. These components exist in Kairos-style permissionless swaps and Boros's rate engines. What does not exist yet is a liquid, standardized cap for the Aave and Morpho borrowing indices.
Layer 4: Recovery and Data
This layer turns accounts receivable into collateral that the lending market can bear. It has three parts.
Standby Buyers: A whitelist for liquidation that accepts only pre-committed buyers (issuers, backup servicers, distressed credit funds), transacting at mutually agreed discounts and earning a standby fee for being present. It replaces the Midnight 60-minute climb to complete liquidation mechanism with a transaction to sell to those who can wait for collections.
Valuation: Pricing collateral by NAV minus expected losses, with discounts expanding as reported aging increases, and adjusting to reality upon collection, rather than accounting for worst-case premiums from day one.
Triggers: Proven accounts receivable, guarantee fund balances, and settlement delay data feeds that automatically reduce drawCaps, treasury limits, and financing facility limits when the asset pool deteriorates. This is the stop-advance clause for warehousing credit limits, being plugged into various venues.
Where the Moat Lies
Contracts will not be the moat. The lending market is converging to the same components, and Aave Labs's acquisition of Avon indicates these venues intend to own fixed rates themselves. Anything built on top must hold value because of what it knows and who it signed, rather than what it deployed.
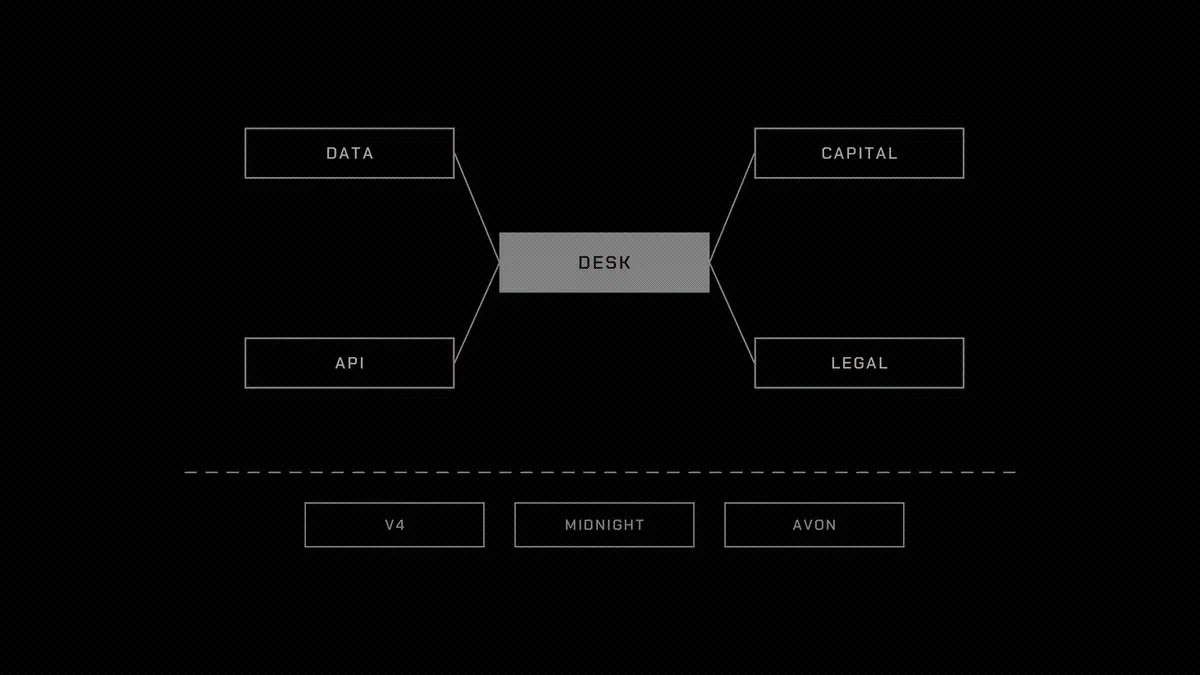
Underwriting data comes first. This credit platform sees every draw, repayment, and settlement delay of its borrowers, and this loss history will continually accumulate. Two years later, it can price a payment corridor or an accounts receivable pool, and do so better than new entrants, who cannot see this data.
The capital network is bilateral. Priority depositors want a first-loss layer in front of them. Subordinate capital and standby buyers want a stable, already underwritten flow of financing facilities. Whoever first brings both sides together sets the pricing terms for the next financing facility.
Then there is integration. Fintech companies integrate a credit API rather than three lending markets. Once borrowers regularly draw from this credit platform every morning and its triggers are plugged into their settlement data, the switching costs become real.
Finally, there is legal packaging, which is also the most challenging part. Providing unsecured loans to payment companies, a receivable claim that stands in their jurisdiction, both parties' KYC: these require time and expertise, and they keep fast replicators out.
Where the Difficulty Lies
Commitments are options. Pricing draws under stress and holding liquidity against them, while not stifling depositor returns, is the core risk issue. If you get this wrong, this credit platform will likely default on its commitments in the most critical week.
Recoveries of unsecured or accounts receivable credit are slow and legal, not on-chain. Wildcat’s first default recovered 76%. 3Jane sold bad debts to licensed collection agencies. The waterfall must price this period.
The foundation layer is changing. Aave's fixed-rate program after the Avon transaction, the adaptation of Morpho going live this quarter, and the Midnight market using accounts receivable as collateral, each could absorb part of this tech stack. This credit platform must be the router and underwriter, not a feature set to be launched by some venue next quarter.
Regulatory matters lie beneath it all. Lending to licensed payment institutions is the cleanest entry point, and it is also the one where counterparties' regulators will go to read the terms list.
I am interested in building this, exploring this idea amidst several others, and looking for those interested in pushing it forward. If you are building any of these layers or want to build, please message me. The four questions above are worth resolving, regardless of who ultimately solves them.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


