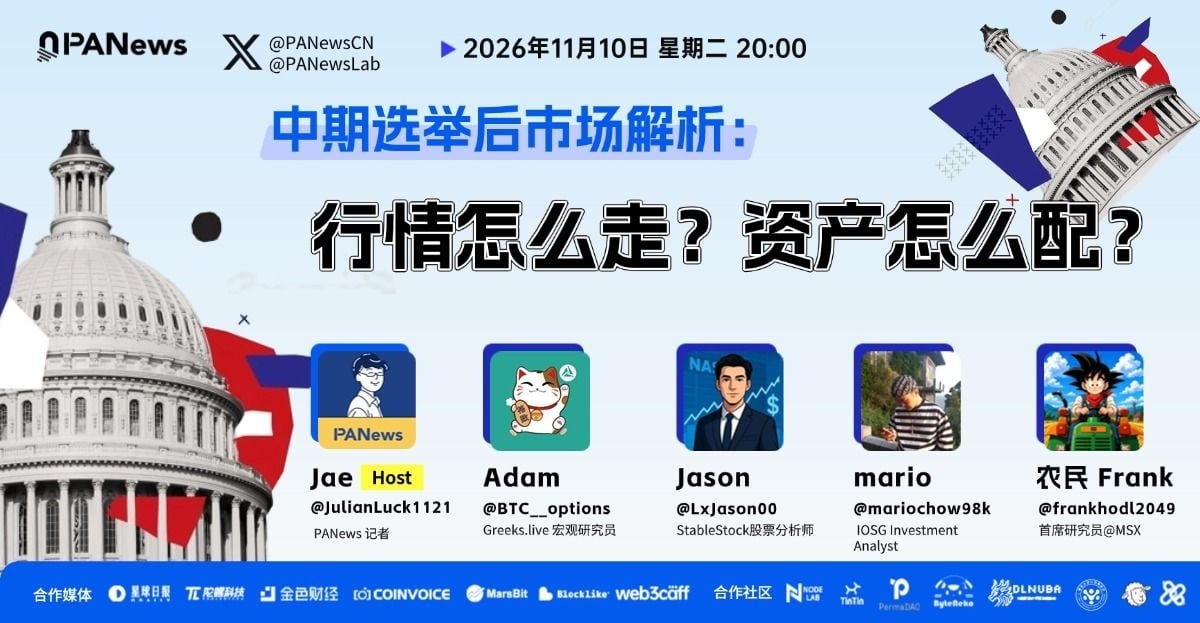
On the evening of November 10, PANews held a themed Space titled "Post-Midterm Election Market Analysis: How Will the Market Move? How to Allocate Assets?" This episode invited macro researcher Adam from Greeks.live, investment analyst Mario from IOSG, chief researcher Frank from MSX Research Institute, and stock analyst Jason from StableStock to engage in discussion.
After the midterm elections, Bitcoin experienced a decline followed by a rise, and then was dragged down again by the sharp drop in the US stock market, falling below $75,000 and returning to the price level seen when Trump won in 2024. In response to the upcoming market trends, the four guests provided different assessments: some believe the bear market has not yet ended, and the bottom still needs to be repeatedly confirmed; others believe the correction is nearly complete and expect a rise next year.
From the direction of US regulation to the diversion of funds from AI to the crypto market and the prospects of traditional financial assets being integrated into blockchain, the guests also engaged in in-depth sharing.
Below are the main points of the discussion, representing only the personal views of the guests and not constituting investment advice.
When Will Bitcoin Hit Bottom? Some Expect a Bearish Market for Six Months, While Others Bet on a Rebound Next Year
Both Adam and Mario believe that Bitcoin has not yet reached its bottom.
Adam is a staunch supporter of the four-year cycle theory. He has defined this round of price increases since August as a "rebound in the bear market," and options data corroborates this: the implied volatility of call options has not risen, and institutions have only bet up to $90,000 with nearly no transactions at the $100,000 level. He believes that the approximately 40% retracement of Bitcoin is not yet sufficient, stating that "we need to grind for at least another six months."
Mario provided two indicators: the total amount of stablecoins has not increased, and ETF funds are continuously flowing out. "Both are negative, indicating that traditional finance is still unwilling to pull funds from AI."
Jason's assessment is more optimistic. He pointed out that in previous midterm elections, Bitcoin hit new lows simply because those years were already bear markets. This year, Bitcoin fell to around $58,000, a drop of over 50%, and it has been close to a year since the last high. With the degree and time both having been reached, plus institutional "buying on the dips" support, he believes that "it may fall further next, but it won't hit new lows, and will rise next year."
Frank questioned the "midterm election pattern" itself. He believes that once the ETF is approved, the pricing logic of Bitcoin has changed, becoming more interconnected with US stocks and tech stocks, stating that "weekends are basically stagnant." Rather than looking at historical patterns, it's better to directly observe whether US stocks can stop falling and stabilize.
Has the Regulatory Trend Changed? The White House and Congress Might Engage in a New Round of Game Playing
With the Democrats taking Congress, long-time critic of the crypto industry Senator Warren is expected to become the Chair of the Senate Banking Committee in January next year. What does this mean for the industry?
Adam believes the biggest change is that uncertainty has returned. Trump has begun to cut ties with his family crypto projects in preparation for leaving office; the CLARITY market structure bill is likely to be delayed, and even some things that have already been established may be re-discussed. He specifically mentioned Hyperliquid: "A highly leveraged, no KYC platform being able to serve US users was unimaginable a few years ago; now, with policy fluctuations, HYPE is dropping."
Mario's view is the exact opposite. He believes that in the short to medium term, HYPE is actually "the asset least afraid of a Democratic Congress," because its benefits mainly come from the executive level, without needing legislation. The real risk will come in 2029 if an unfriendly government arrives; the CFTC may retract its approval of perpetual contracts.
Frank also believes that there is no need for excessive pessimism. The looseness of the past two years mainly comes from executive powers, such as the SEC easing litigation, CFTC promoting US stock perpetual contracts, and Bitcoin as a strategic reserve; the new congressional turnover has limited impact on this. The key issue with the CLARITY bill is not the bipartisan struggle, "but rather that banks do not want deposits to flow out; it's a negotiation between traditional finance and new crypto players over the terms." The projects related to the Trump family will be the ones really impacted.
Jason's summary is very straightforward: the heads of the SEC and CFTC are still appointed by Trump, and enforcement will not tighten immediately; the next two years will see a standoff where "the White House continues to loosen, while Congress desperately investigates." However, he does not believe this is necessarily a bad thing in the long term, stating that "even if the legislation is stricter, uncertainty is removed, and institutions will dare to enter once they know the rules."
Stablecoin Shuffle: USD1 Faces Political Risks, Circle Encountering Profitability Challenges
The GENIUS stablecoin bill will be implemented in January next year. Who is under the most pressure?
The guests generally hold a pessimistic view on the Trump family's USD1. Adam thinks stablecoins need time to settle, stating, "If everyone knows it might be abandoned in two years, no one will be willing to take it on now." Frank also pointed out that Warren has long held a tough stance on crypto and anti-money laundering; Trump's family projects will be her main targets.
Regarding USDT, the guests believe its impact is limited. Its main scenarios are in offshore exchanges and payments outside the US; the new regulations primarily restrict the domestic US market.
On the contrary, Frank believes the real pressure is on Circle. A significant portion of USDC's circulation relies on Circle subsidizing exchange profits with US Treasury yields, which are then indirectly subsidized to users. If subsequent legislation blocks this outlet, it will be a huge negative for Circle, and USDC circulation has currently dropped to a low point for the year. Jason adds that exchanges are also under pressure, with stablecoin-related revenue accounting for about 30% of Coinbase's total revenue. The future revenue models for stablecoins may need to shift towards tokenized deposits, tokenized money market funds, and other products.
Behind the Capital Divergence Due to AI, the Weak Growth of Crypto is the Real Concern
This year, AI has pulled in significant amounts of capital. Where will the incremental funds for the crypto market come from?
Adam's view is sharp: the poor performance is an issue of the crypto circle itself. Aside from stablecoins and tokenization of US stocks, there has been little progress in native crypto products, stating, "If I were an investor, I would definitely invest in AI now, even buying Bitcoin would have to come after AI."
Frank's words are even more severe: from DeFi, NFTs to DePIN, Layer 2, the rounds of narratives have not brought about endogenous growth, "Even without the siphoning effect of AI, the crypto market has already reached the end of the previous model; AI has merely accelerated the exposure of this reality." So do not expect that once the AI bubble bursts, funds will automatically flow back.
Jason, however, holds a different view. He believes that Bitcoin's decline this year is not because AI has snatched funds, but rather that policy benefits were fully realized last year, and this year is just a cyclical correction. Moreover, AI stocks have begun to differentiate since mid-year, and capital is already weak. Regardless of whether AI data centers continue to expand, it's not beneficial for US stocks; funds may instead flow to Bitcoin, stating that "next year, Bitcoin will outperform US stocks, especially beating the Nasdaq 100."
Traditional Finance on the Blockchain: Expansion of Trading Scenarios, Incremental Funds Still Awaiting Entry
Can the on-chain US stocks and commodities bring in new capital?
Mario provided a positive signal: on Hyperliquid, the trading volume for US stock-related markets once reached about 50%, attracting many hedge funds and proprietary trading firms.
Frank is more cautious. He believes that offshore exchanges introducing US stock trading still serve existing crypto trading users; Robinhood tokenizing stocks will not lead users to switch to crypto. What can truly bring in incremental capital are services that traditional finance cannot provide, such as 24/7 US stock perpetual contracts.
Jason believes the biggest breakthrough point remains institutions, which are waiting for clear regulations, stating that "once the law clarifies, pension funds and retirement funds will enter in large numbers."
Asset Allocation: Increasing Bitcoin Holdings, Shifting to Defensive Sectors
Lastly, the guests shared their allocation strategies for the next two years:
- Adam: Dumbbell-shaped allocation. Large positions gradually allocated to Bitcoin, minimal allocation to high-risk assets like HYPE, and using options structured products and arbitrage to enhance returns.
- Mario: Bitcoin, plus assets that do not rely on congressional legislation, and the privacy sector less influenced by policy and AI.
- Frank: In crypto, mainly allocate to ETH and tokens with a dividend mechanism on the Ethereum chain; in US stocks, eliminate AI hardware and switch to public cloud platforms like Google and Microsoft.
- Jason: Only buy Bitcoin in crypto, increasing holdings on dips next year; in US stocks, if the Nasdaq 100 does not hit new highs, reduce holdings in tech stocks during rebounds, shifting towards defense, healthcare, and banking stocks.
Full replay of this Space: Click here to listen.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


