The barbaric conqueror, according to an eternal historical rule, is themselves conquered by the higher civilization of the subjects they have subjugated.
Written by: Mr. Zuo
Searching for the Next King of Arbitrage
In 2017, Binance rapidly became the world's number one through regulatory arbitrage, but by 2025, the more liberated Hyperliquid could only capture 15% of Binance's market share, and does RWA as a source of DeFi underlying asset hold any space for regulatory arbitrage and a scalable future?
Compliance became the main theme of 2026, as offshore Binance officially established itself in the UAE ADGM, and @Coinbase introduced the genius act and the clear act, even major Eastern countries are tentatively testing RWA regulations.
We are at a clear turning point; blockchain will not replace the internet, and Web3 is just a self-righteous scam. The effect of token listings ended with Binance's acquisition of Bitcoin, but Hyperliquid is making strides in precious metals and predictive markets, while RWA represented by coins (stablecoins), stocks (U.S. stocks), bonds (U.S. treasuries, subprime bonds), and bases (hedging, active) is timely now.
In this context, compliance transcends the mere ceremonial role of holding the cards of small countries while harnessing the benefits of large nations, evolving into a real framework of separation of trading, clearing, and custody. When the industry breaks through scale limitations, regulatory benefits will become profitable.
In silence, compliance not only signifies the end of the previous frenzy era, accompanied by thunderous roars, but there will always exist opportunities for arbitrage in developing tracks.
Let's start from the exchanges for a glimpse into the economic considerations beyond compliance.
Civilized Wall Street, Mad Barbarians
The barbaric conqueror, according to an eternal historical rule, is themselves conquered by the higher civilization of the subjects they have subjugated.
In 2022, FTX collapsed dramatically, and Wall Street once harbored the idea of occupying the exchange track. Castle Securities, Fidelity, and Charles Schwab collaborated to launch EDX Markets in Singapore, operating under the principle of separation of trading and custody within the compliance framework of Singapore's MAS.
As Gary Gensler's SEC relentlessly pursued Binance, @Coinbase and @krakenfx could only retract into the U.S. spot market, unable to venture into the high-end markets of contracts and options. At that time, the market held high hopes for EDX Markets,
If there are no surprises, we should witness Binance's downfall, similar to BitMEX after March 12, 2020, but history never repeats itself. @HyperliquidX is the real winner, and neither the declining Binance nor the retreating Coinbase in the U.S. market are the protagonists of the next act.
To learn the successful experiences, one must understand the lessons of the failures.
After its establishment in 2017, Binance at least did two things right:
- While actively embracing overseas markets, it continued to accommodate users from mainland China, with trading volume and user scale acting as a seesaw;
- In 2019, it launched IEO (Initial Exchange Offering), creating a genuine wealth effect before DeFi Summer.
After the September 4 ban, providing trading services for users from mainland China was in a "grey area." The third regulation directly targeted trading platforms, requiring them not to provide quoting, matching, and clearing services. If we refer to He Yi's response to Cathie Wood, Binance would respond with "not providing services for mainland Chinese users."
From 2017 to 2019, Binance secured the first position in global offshore exchanges. From 2020 to 2022, Binance filled the contract market left by BitMEX. From 2022 to 2024, Binance dominated the global altcoin market, and the effect of token listings equated to the Binance effect.
Entering 2025, Binance officially took the helm under the compliance framework of Abu Dhabi ADGM and categorized itself into three entities: trading, clearing, and over-the-counter, but this still retained Binance's unique arbitrage features.
Especially, compliance did not prevent Binance from listing meme coins; additionally, ADGM and the entire financial system of the UAE fundamentally lack the capability to regulate a behemoth like Binance, which can be compared to the Bahamas' helplessness towards the global FTX.
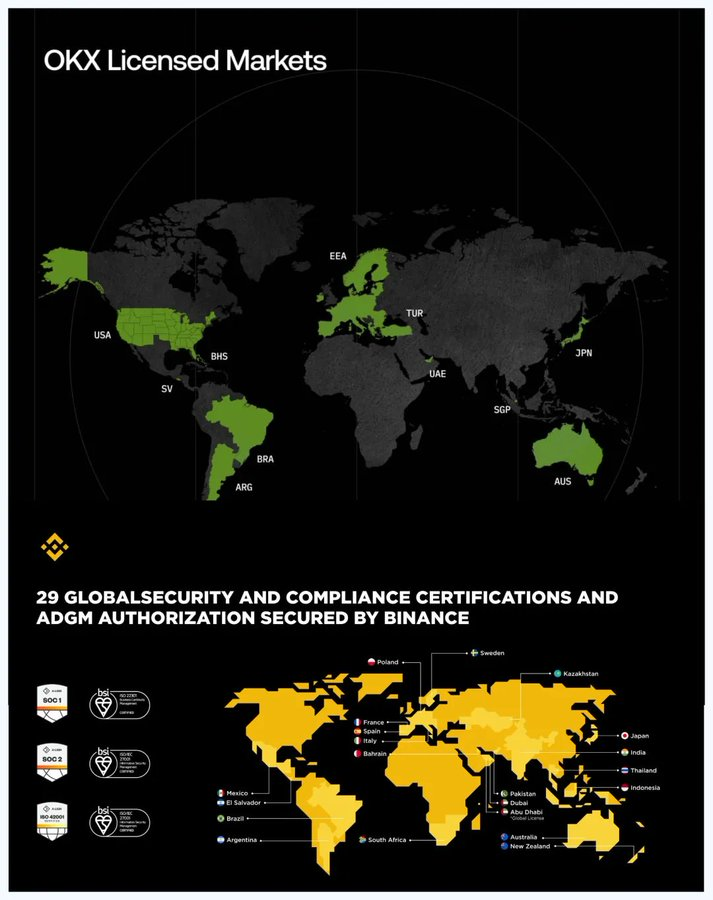
Image caption: Only by taking the civil service exam can one succeed; image source: @Binance @okx
Coinbase has been the most compliant since the collapse of FTX, but this compliance stems from the continuous transformation of the SEC, CFTC, and OCC since Trump's rise to power, requiring them to adopt more crypto-friendly regulatory measures.
Generally, the SEC is responsible for reviewing whether a specific token meets the definition of a security. The CFTC oversees derivatives trading, and the OCC is responsible for bank licensing for custody operations. The U.S. lacks a regulatory framework for a "crypto exchange license" similar to ADGM, only having regulatory scopes based on business types.
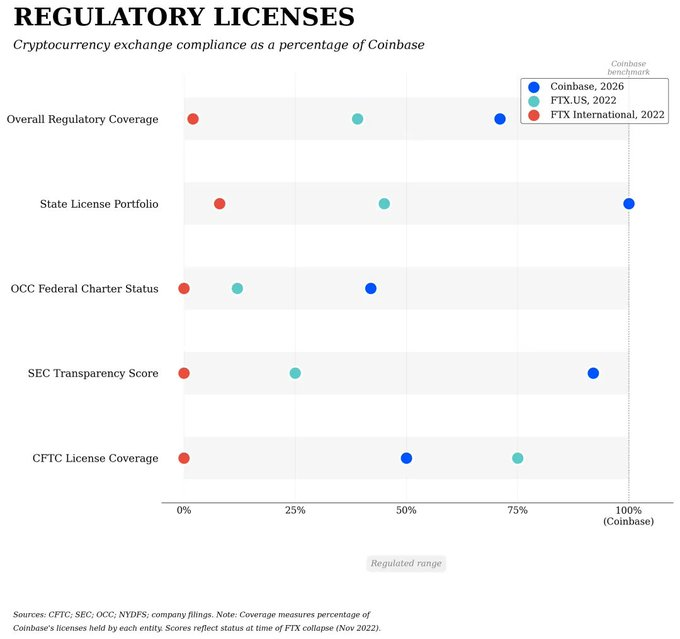
Image caption: Regulatory progress; image source: @zuoyeweb3
This construction of regulatory frameworks is still ongoing, but it can be confirmed that Coinbase will shape the U.S. compliance framework, covering aspects like listing (spot, contracts), trading (spot, contracts), custody (retail, institutional), clearing/settlement (fiat, crypto), auditing (technical, asset)/insurance (fiat, crypto).
Binance's licensing under ADGM is not the same concept as Coinbase's licensing in the U.S., where the latter's licensing will be effectively regulated by relevant authorities.
Regulation aims to clarify rules rather than protect retail interests. For example, institutional clients in Coinbase's custody business enjoy bankruptcy isolation protection, corresponding to Coinbase Custody Trust Company.
However, the funds deposited by ordinary retail clients in Coinbase correspond to Coinbase Inc. If it's fiat currency, there might be FDIC deposit insurance protection from the corresponding bank, but crypto assets may very likely face the same fate as FTX.
For instance, buyers of FTX's FTT tokens are recognized as equity holders and are not strictly protected in claims. Similar to Coinbase, the only good news is that Coinbase has not faced a bank run crisis.
Hyperliquid's "Unlicensed" Entry into the RWA Field
The progress of humanity must no longer resemble the terrifying pagan monsters, where one needs the severed heads of the slain to drink sweet wine.
Regulatory arbitrage still exists. In the field of crypto asset trading, EDX's compatriot Hyperliquid is also starting in Singapore, eroding Binance's global market and Coinbase's U.S. market.
This could be called second-level arbitrage, with Binance extracting profits from global regulation and Hyperliquid reaping profits from Binance.
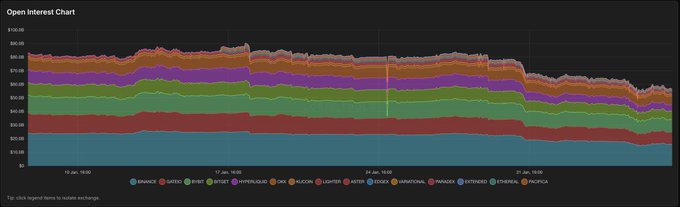
Image caption: CEX and DEX are hard to distinguish in quality; image source: @LorisTools
Hyperliquid has banned U.S. IP addresses, but this ban has no real effect. Comparatively, U.S. users can hardly open an account on Binance's global site and can only use Binance's U.S. site.
Coinbase initially allowed contract trading for U.S. users, but its transaction volume was equivalent to nonexistent, so in a peculiar space, Hyperliquid seized some European and American users outside of Binance and Coinbase to engage in derivatives business.
However, it should be noted that Hyperliquid's arbitrage cannot replicate Binance's growth miracle nor can it learn from Coinbase's occupation of the U.S. compliance market; it can probably only capture 15% of Binance's market share.
As Hyperliquid makes progress in precious metals, predictive markets, and other non-traditional businesses, its impact on the global financial market is gradually strengthening. If the U.S. can regulate Binance and Tornado Cash, actions against Hyperliquid will likely not encounter resistance from Singapore.
Ultimately, most "underground economy" models cannot enter scalable domains. Taking USDT as an example, its issuance reserves and circulation restrictions are becoming increasingly stringent, as evidenced by the bybit hacking incident with USDT and the freezing of illicit funds post the Huobi incident.
Huobi can support the entire underground economy of Cambodia and even Southeast Asia, but Cambodia cannot afford the price of being placed on the "grey list" by the FATF for money laundering.
Binance can support an economy dominated by altcoins on the BNB chain, but the squeezing effect between China and the U.S. prevents Binance from accessing higher-quality trading assets.
This essentially reflects America's cost advantages in low regulation. American external economic sanctions do not center on the dollar and the U.S. military, but on America being the largest single consumer market and the main financial market globally. Once Cambodia and Binance are cut off from their ties with the U.S., the next step would be North Korea.
Thus, Binance is paying a high price to remain compliant, and it is only a matter of time before Hyperliquid’s compliance becomes a reality.
This raises an extended question: can RWA replicate the trajectory of crypto asset trading tracks, retaining itself amidst regulatory arbitrage and develop its transaction volume within a compliance framework?
This is premised on Hyperliquid's near impossibility to surpass Binance in the crypto asset trading field and almost being unable to exceed Coinbase in terms of compliance level.
If we look back at 2017, CZ himself might not believe that CEX is the future. Looking forward, postal coins, P2P, O2O, and ofo are all transient phenomena; looking back, DeFi mining, NFTs, GameFi, and SocialFi have all come to naught.
Thus, Binance and BNB should be understood as project foundations, where their halo is continuously extended through wealth effects, which were supposed to end hastily, much like another financial bubble.
But under network effects, the network effect of trading has shed the shackles of crypto assets and entered all financial domains, thus encountering RWA in a broad sense. Stablecoins disrupt CBDCs, and asset-based securitization will inevitably lead to tokenization.
For instance, the recent regulatory guidelines from Tokyo University essentially reflect America's spillover impact in the financial sector, which will rewrite on-chain finance in unique ways.
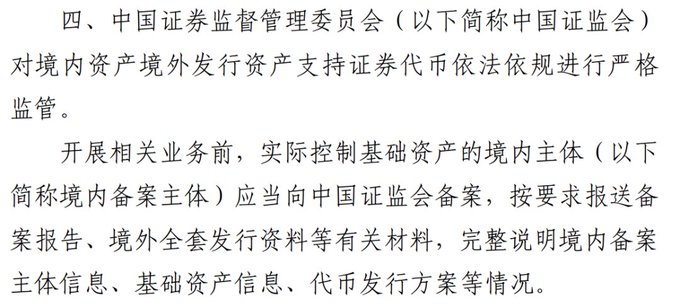
Image caption: Flowers bloom inside the wall, fragrance wafts outside
Regarding Tokyo University's new regulatory measures, Caixin explains that there are four categories: foreign debt, equity, asset securitization, and others. However, in my view, the only significant angle is the tokenization of securities, aligning with the reform direction of "securitizing all assets," specifically:
- The competent authority is the Securities Regulatory Commission
- Issuance requires approval from the Securities Regulatory Commission
- Allowed only for issuing from domestic to overseas
Moreover, this securities tokenization guideline clearly states that rights and benefits must comply, corresponding to the SEC's encouragement of the evolution process of original "stock tokenization," while the situations regarding overseas renminbi stablecoin, foreign debt, and funds are rather unique.
- Overseas offshore renminbi stablecoin operations have always existed, such as USDT issued by Tether, but practical use is lacking, leading to very small business volumes;
- Issuing overseas bonds and funds on-chain has factually commenced, fully isolating domestic assets and directed at overseas clients, unrelated to this guideline.
This regulation pertains to the overseas issuance of domestic assets, essentially emphasizing this separation: overseas belongs to overseas, domestic belongs to domestic, only when the two intersect does it necessitate entering the regulatory process.
In the current RWA field, the U.S. and China have virtually initiated a land grab, with this liquidity spillover to on-chain being sufficient to rewrite the current financial landscape.
Conclusion
The fate of an industry obviously relies on self-struggle, but historical trajectories must also be considered.
CZ might not even believe that CEX is the future; even Bitcoin may just be a phase of a new pyramid scheme, quickly becoming a historical term like P2P and high-interest loans, which wither away in the wind.
Yet no one expected CEX to survive into 2026, and Hyperliquid is advancing toward precious metals and predictive markets, but it has still not flipped Binance.
If Hyperliquid adds RWA, will it finally reach the other shore this time?
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


