The turning point may be after the interest rate cuts in the second half of 2027, when ETF funds resonate with central bank gold purchases, leading to a potential acceleration in gold prices.
Written by: Dong Jing, Wall Street Insights
Goldman Sachs has significantly lowered its gold price forecast, as the Federal Reserve's hawkish shift suppresses investor demand. Although central bank gold purchases remain strong, the short-term upward space for gold is still significantly compressed.
According to the Pursuit of Trends trading desk, Goldman Sachs' commodity research team released its latest precious metals research report on November 5, drastically reducing its gold price forecast: the year-end target price for 2026 has been lowered from $4650/ounce to $4150/ounce, and the year-end target price for 2027 from $5400/ounce to $4800/ounce.
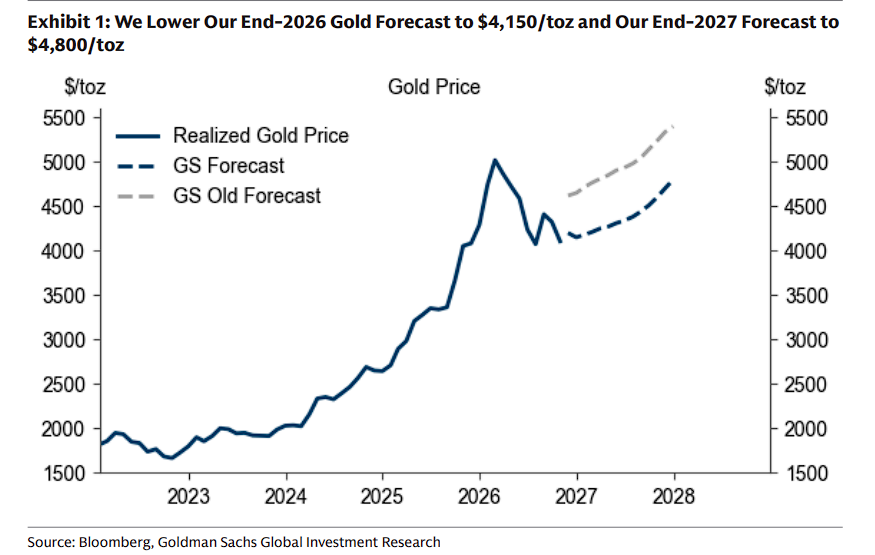
Goldman Sachs pointed out that despite the recent recovery in the bond market bringing market pricing closer to its economists' prediction of the Federal Reserve's terminal rate, the baseline scenario assumes that the Federal Reserve's hawkish shift and an interest rate hike in December 2026 will suppress investors' concerns about "currency depreciation." This will lead to a return of macro policy hedging demand for gold—particularly reflected in demand for bullish options—back to historical averages rather than returning to the high levels seen early this year.
Goldman Sachs clearly stated that the current gold market dynamics are increasingly similar to those of 2022: central bank gold purchases provide strong structural buying support, but higher interest rates suppress investor positions, resulting in a moderate increase in gold prices.
At the same time, Goldman Sachs maintains a long-term constructive view on central bank gold purchases, predicting that the average monthly gold purchases by central banks will remain at 60 tons from 2026 to 2027, far higher than the average of 17 tons per month before 2022. However, this structural support is unlikely to offset the suppression of investor sentiment from rising interest rates.
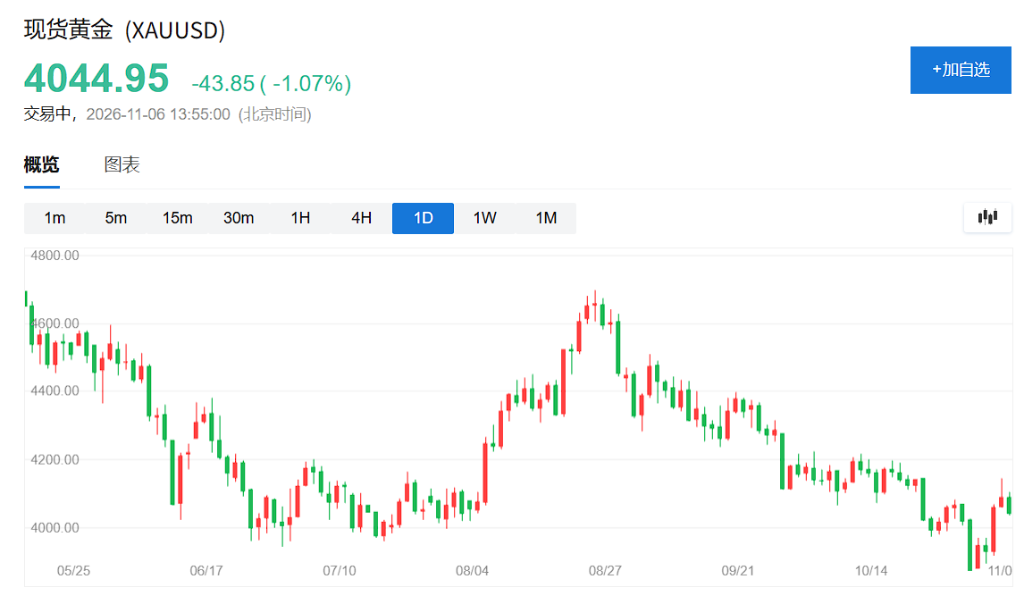
On Thursday, international spot gold fell more than 1%, reaching a low of $4036.82/ounce. However, in the past two trading days, as oil prices and US stocks fell, spot gold rebounded consecutively, once reaching above $4100/ounce.
Target Price Significantly Lowered, Federal Reserve's Hawkish Shift is the Core Driver
The direct reason for Goldman Sachs' lowering of its gold forecast is the profound impact of the Federal Reserve's recent hawkish stance change on market positions.
Specifically, Goldman Sachs has lowered its year-end gold target price for 2026 from $4650/ounce to $4150/ounce and from $5400/ounce to $4800/ounce for 2027.
Goldman Sachs' baseline scenario assumes that the Federal Reserve will raise interest rates again in December 2026, which will keep investor concerns about "currency depreciation" in a suppressed state. Therefore, the macro policy hedging demand that previously drove gold prices higher—specifically manifested in demand for bullish options—is expected to return to historical average levels rather than revisit the highs of early 2026.
In terms of downside risks, if the Federal Reserve raises interest rates again in March 2027, coupled with a higher terminal rate and delayed interest rate cuts, Goldman Sachs estimates that the gold price at the end of 2027 will be only $4660/ounce (further down from the baseline scenario of $4800/ounce).
Central Bank Gold Purchases Remain Strong but Struggle to Support the Market Alone
Despite the target price being lowered, Goldman Sachs maintains a long-term constructive view on gold, with core support coming from structurally strong central bank gold purchasing demand.
Goldman Sachs predicts that from 2026 to 2027, central bank gold buying will remain at 60 tons per month, far exceeding the historical average of 17 tons per month before 2022. Goldman Sachs' real-time tracking data (GS Nowcast) shows that current central bank gold purchases have reached 85 tons per month based on a seasonally adjusted 3-month moving average.
From a structural perspective:
- Emerging market central banks, especially the People's Bank of China, still hold gold reserves that are significantly low relative to their reasonable long-term allocation targets;
- The motivation to diversify holdings of G7 reserve currencies—due to geopolitical risks and financial risks—is likely to continue;
- It is noteworthy that the focus on gold demand and reserve security is spreading beyond the realm of emerging market central banks. Although developed market central banks have historically held significant gold reserves and have been largely absent from the gold purchasing wave since 2022, current discussions have shifted from "whether to hold gold" to "where to store gold," reflecting broader concerns about reserve security and cross-border trust.
However, Goldman Sachs points out that central bank gold purchases can only provide structural support and are unlikely to drive substantial increases in gold prices alone in a high-interest-rate environment, which emphasizes the similarity of the current dynamics to those of 2022.
Current Dynamics Are Similar to 2022: Central Bank Support, High Rates Pressure
Goldman Sachs clearly compares the current gold market to that of 2022: central banks provide strong structural buying support, but high interest rates suppress investor positions, resulting in a moderate net price increase.
The historical experience of 2022 indicates that in such a pattern, gold prices do not decline unilaterally but exhibit characteristics of limited increases and increased volatility. The sustained buying by central banks provides a bottom support for gold prices, but high interest rates significantly suppress the willingness of Western investors to participate through gold ETFs and other channels.
The recent rebound in the bond market has brought market pricing closer to Goldman Sachs economists' predictions of the Federal Reserve's terminal rates. However, Goldman Sachs believes that the Federal Reserve's hawkish stance will continue to suppress the rebound of macro hedging demand, thus significantly constraining the upward potential for gold prices.
Interest Rate Cut Expectations in the Second Half of 2027 May Catalyze the Next Round of Gold Price Increases
Goldman Sachs economists expect the Federal Reserve to implement three interest rate cuts from the second half of 2027 to early 2028. Once the interest rate cut cycle begins, the constraints on gold prices from interest rates will be lifted, at which point:
- Inflows of interest rate-sensitive Western gold ETF funds are expected to be reactivated;
- Private investor demand will once again resonate with structural central bank gold purchasing demand;
- The combination of these two forces will translate more fully into upward momentum for gold prices.
Additionally, Goldman Sachs points out a potential bullish scenario: if concerns about fiscal sustainability in Western economies increase—possibly due to higher military spending and heavier debt burdens on energy-importing countries—and investors begin to question developed market central banks' willingness or ability to respond to inflation, macro policy hedging demand could make a comeback, pushing gold prices beyond the baseline forecast of $4800/ounce.
Demand for Bullish Options: A Key Mechanism Amplifying Gold Price Volatility
Goldman Sachs specifically analyzes the amplifying effect of bullish options demand on gold prices in the report, which has become increasingly important since mid-2025.
Goldman's simple gold model shows that for every additional 100 tons of net certainty demand (including Western ETF holdings, net managed fund positions, and central bank gold purchases), the gold price rises by about 2%. However, since mid-2025, the actual volatility of gold prices has exceeded what can be explained by this basic flow of capital, while demand for bullish options has surged sharply.
Goldman Sachs interprets this demand for bullish options as a reflection of macro policies or hedging against "currency depreciation": investors are paying a premium for the tail risk of nonlinear explosive increases in gold prices.
On a mechanistic level, bullish options positions can amplify gold price fluctuations in both directions:
- When the gold price approaches a key strike price, market makers who have sold bullish options must buy gold to hedge their exposures, thereby reinforcing the upward trend;
- When the gold price falls, market makers may close out their hedge positions, further amplifying the decline.
Goldman Sachs estimates that for every additional million outstanding GLD bullish options contracts, the gold price rises by about 5%.
Goldman Sachs indicates that it currently does not incorporate this options-driven amplifying effect into its baseline price predictions due to the short historical data on high bullish options demand and the uncertainty in estimating related effects.
However, Goldman Sachs emphasizes that once the Federal Reserve's interest rate hike cycle ends and interest rate constraints fade, this mechanism could play a critical role again. At that time, the return of macro policy hedging demand will push bullish options demand back to the high levels of early 2026, and market makers' hedging behavior will once again amplify basic demand into a more violent nonlinear uptrend.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


