Author: Nancy, PANews
The Arc mainnet launched with great fanfare, capturing the market’s attention but struggling to avoid the "one-day tour" phenomenon. In this brief on-chain celebration, Uniswap absorbed the traffic, emerging as a winner.
From Robinhood Chain to Arc, the growth dividends from new chain traffic have become an important driving force behind Uniswap's recent growth. Meanwhile, v4 is accelerating to catch up with v3, gradually becoming a significant force in expanding Uniswap's liquidity landscape.
Benefiting From Robinhood Chain, Uniswap Captures Arc Traffic
Over the past month, UNI has charted a strong performance, with a cumulative increase of 108.9%, rising from $3.2 to $6.9. Even amid the recent overall cryptocurrency market pullback, UNI has continued to rise against the trend. Behind the sustained price increase, besides a warming market sentiment, the continuously growing trading volume and protocol revenue for Uniswap have also become vital fundamental support.
According to DeFiLlama data, during the past month, Uniswap processed a cumulative trading volume exceeding $79.5 billion, surpassing the combined trading volumes of PancakeSwap, PumpSwap, and Aerodrome during the same period. In just the past 24 hours, Uniswap's trading volume has approached $3.86 billion, several times more than the second-place PancakeSwap.
The ongoing increase in trading volume has also directly driven up Uniswap's protocol revenue. DeFiLlama reports that in the last quarter, Uniswap's protocol revenue reached $23.15 million, while in the past 30 days, it achieved $5.26 million, ranking first among DEX revenues.
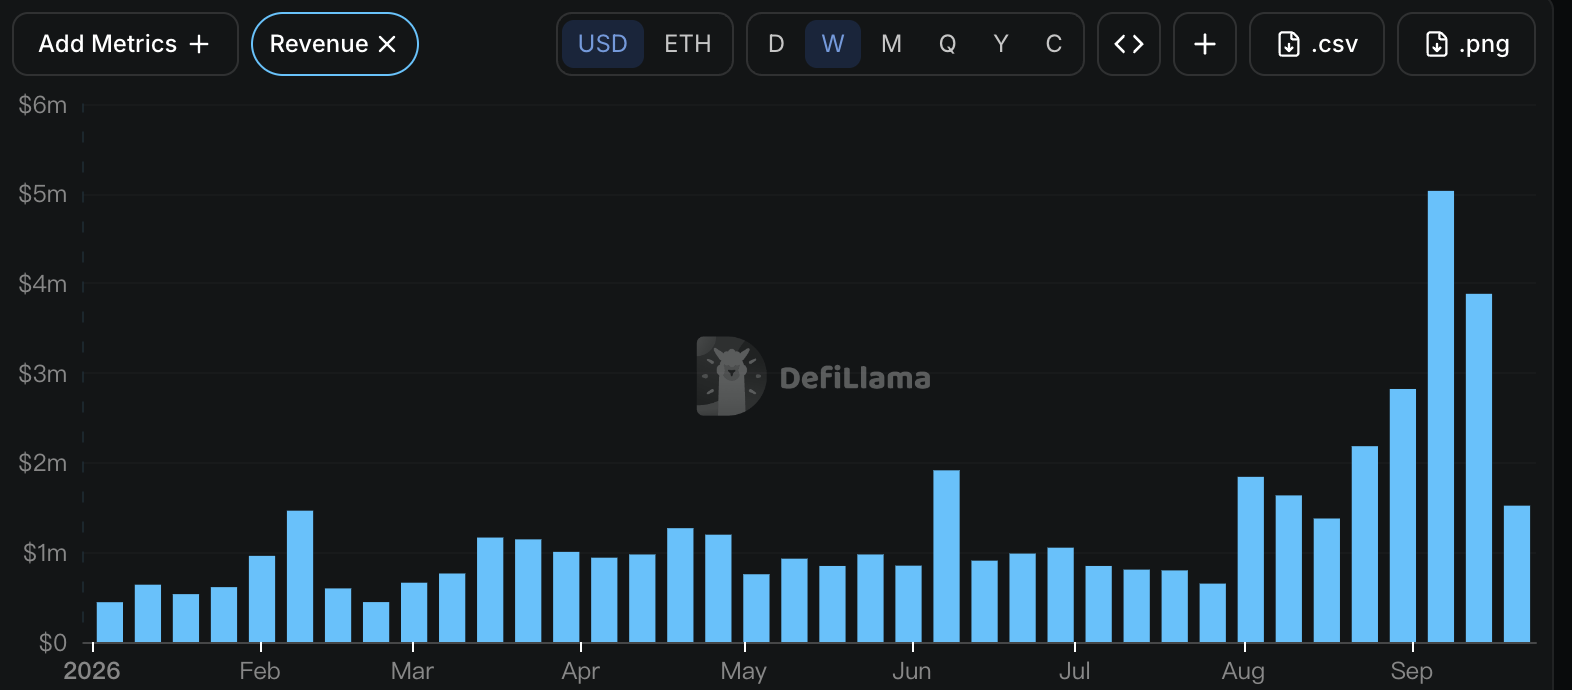
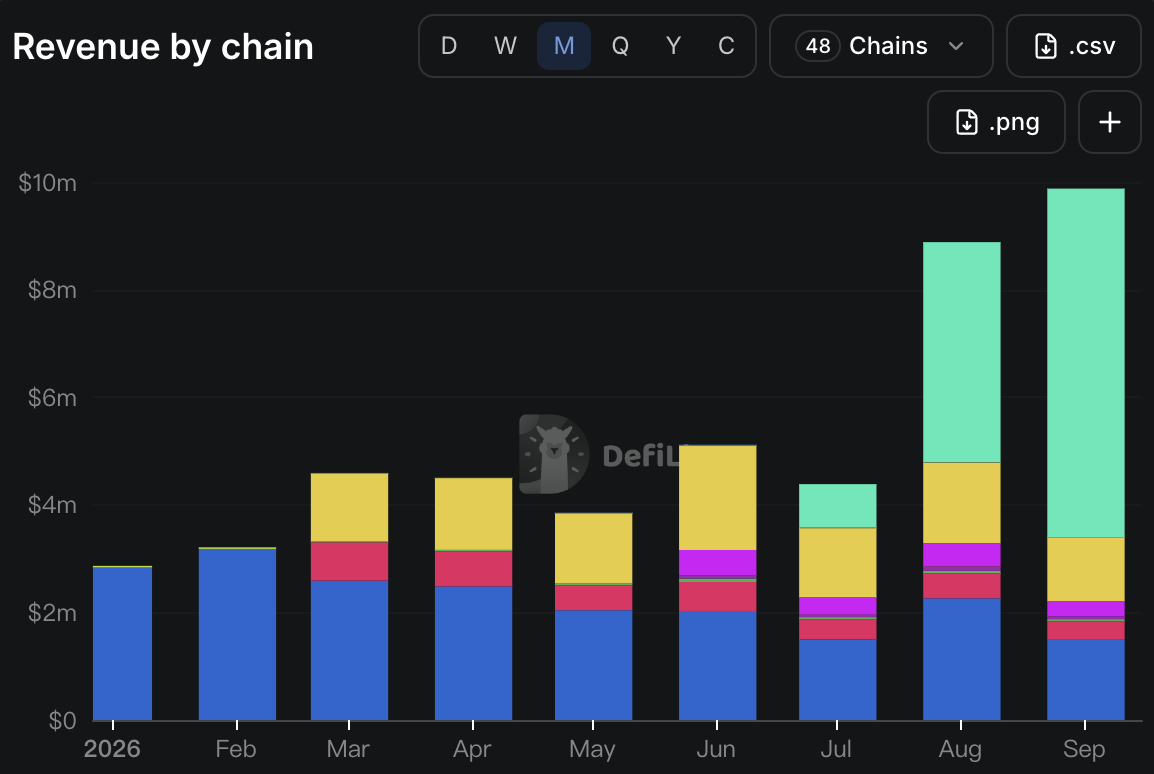
Currently, Robinhood Chain has emerged as the main contributor to Uniswap's recent revenue growth. For example, based on September data, this month Robinhood Chain contributed about $6.48 million to Uniswap's protocol revenue, accounting for 65.5% of total revenue during the same period. Although revenue from Robinhood Chain has decreased from previous peaks due to the cooling of the meme trading frenzy and the withdrawal of some high-fee pools, Uniswap's overall protocol revenue has not shown significant decline.
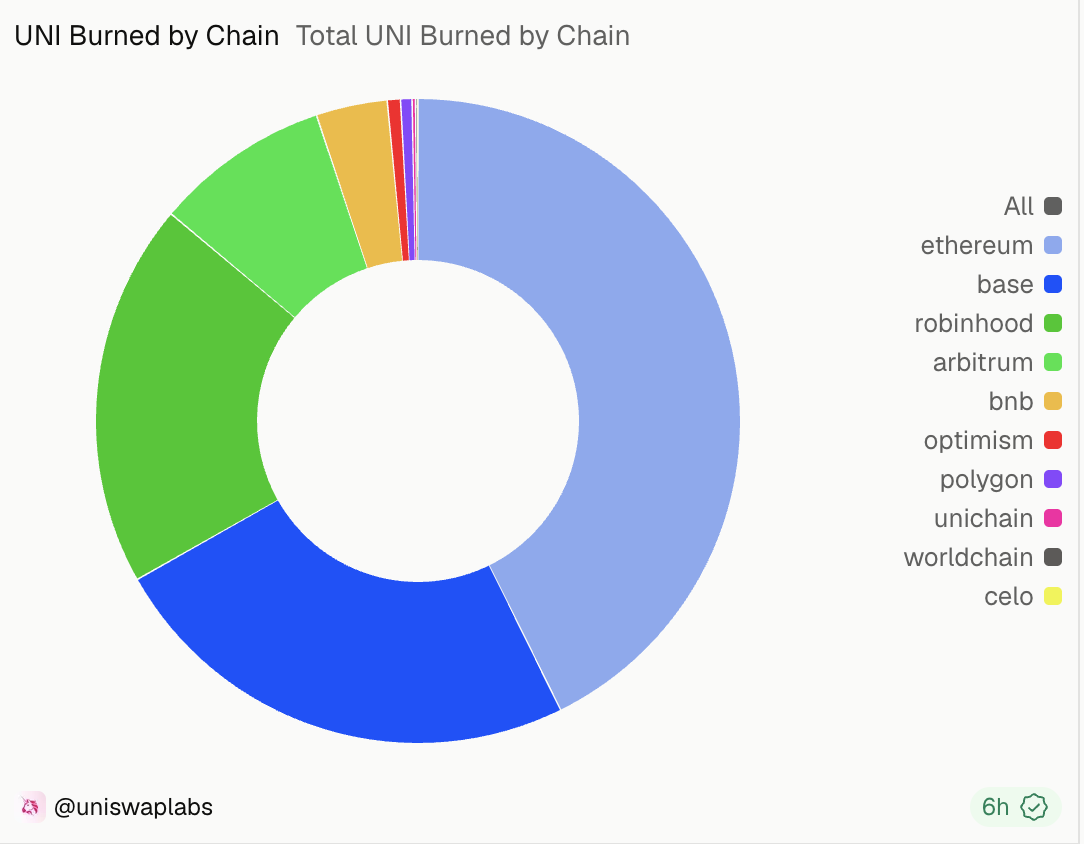
After the fee switch for Robinhood Chain was activated at the end of July, the scale of UNI burned has accelerated significantly. Dune data shows that in less than two months, the UNI burned from Robinhood Chain accounted for 19.3% of the total burn. Looking at the daily data, this proportion was even higher on September 17, with UNI burned from Robinhood Chain accounting for half of the total burned that day, significantly higher than other networks like Ethereum and Base.
With its leading DEX liquidity and user base, Uniswap has also become a preferred partner for new chains vying for traffic. On the first day of the Arc mainnet launch, Uniswap announced full integration with Arc and became its preferred DEX. As trading activity on Arc rapidly increased after its launch, Uniswap leveraged this to gain a new entry point for trading traffic.
Dune data shows that on September 16, Uniswap’s trading volume on Arc exceeded $410 million. In contrast, Uniswap's trading volume on the first day of Robinhood Chain's mainnet launch was around $70.5 million. Looking solely at the trading volume on the first day of the mainnet launch, the traffic brought to Uniswap by Arc was significantly higher than that from Robinhood Chain. However, this wave of trading excitement on Arc brings more incremental traffic to Uniswap; since Uniswap has not yet activated the fee switch on Arc, this portion of trading volume cannot currently be converted into UNI burned.
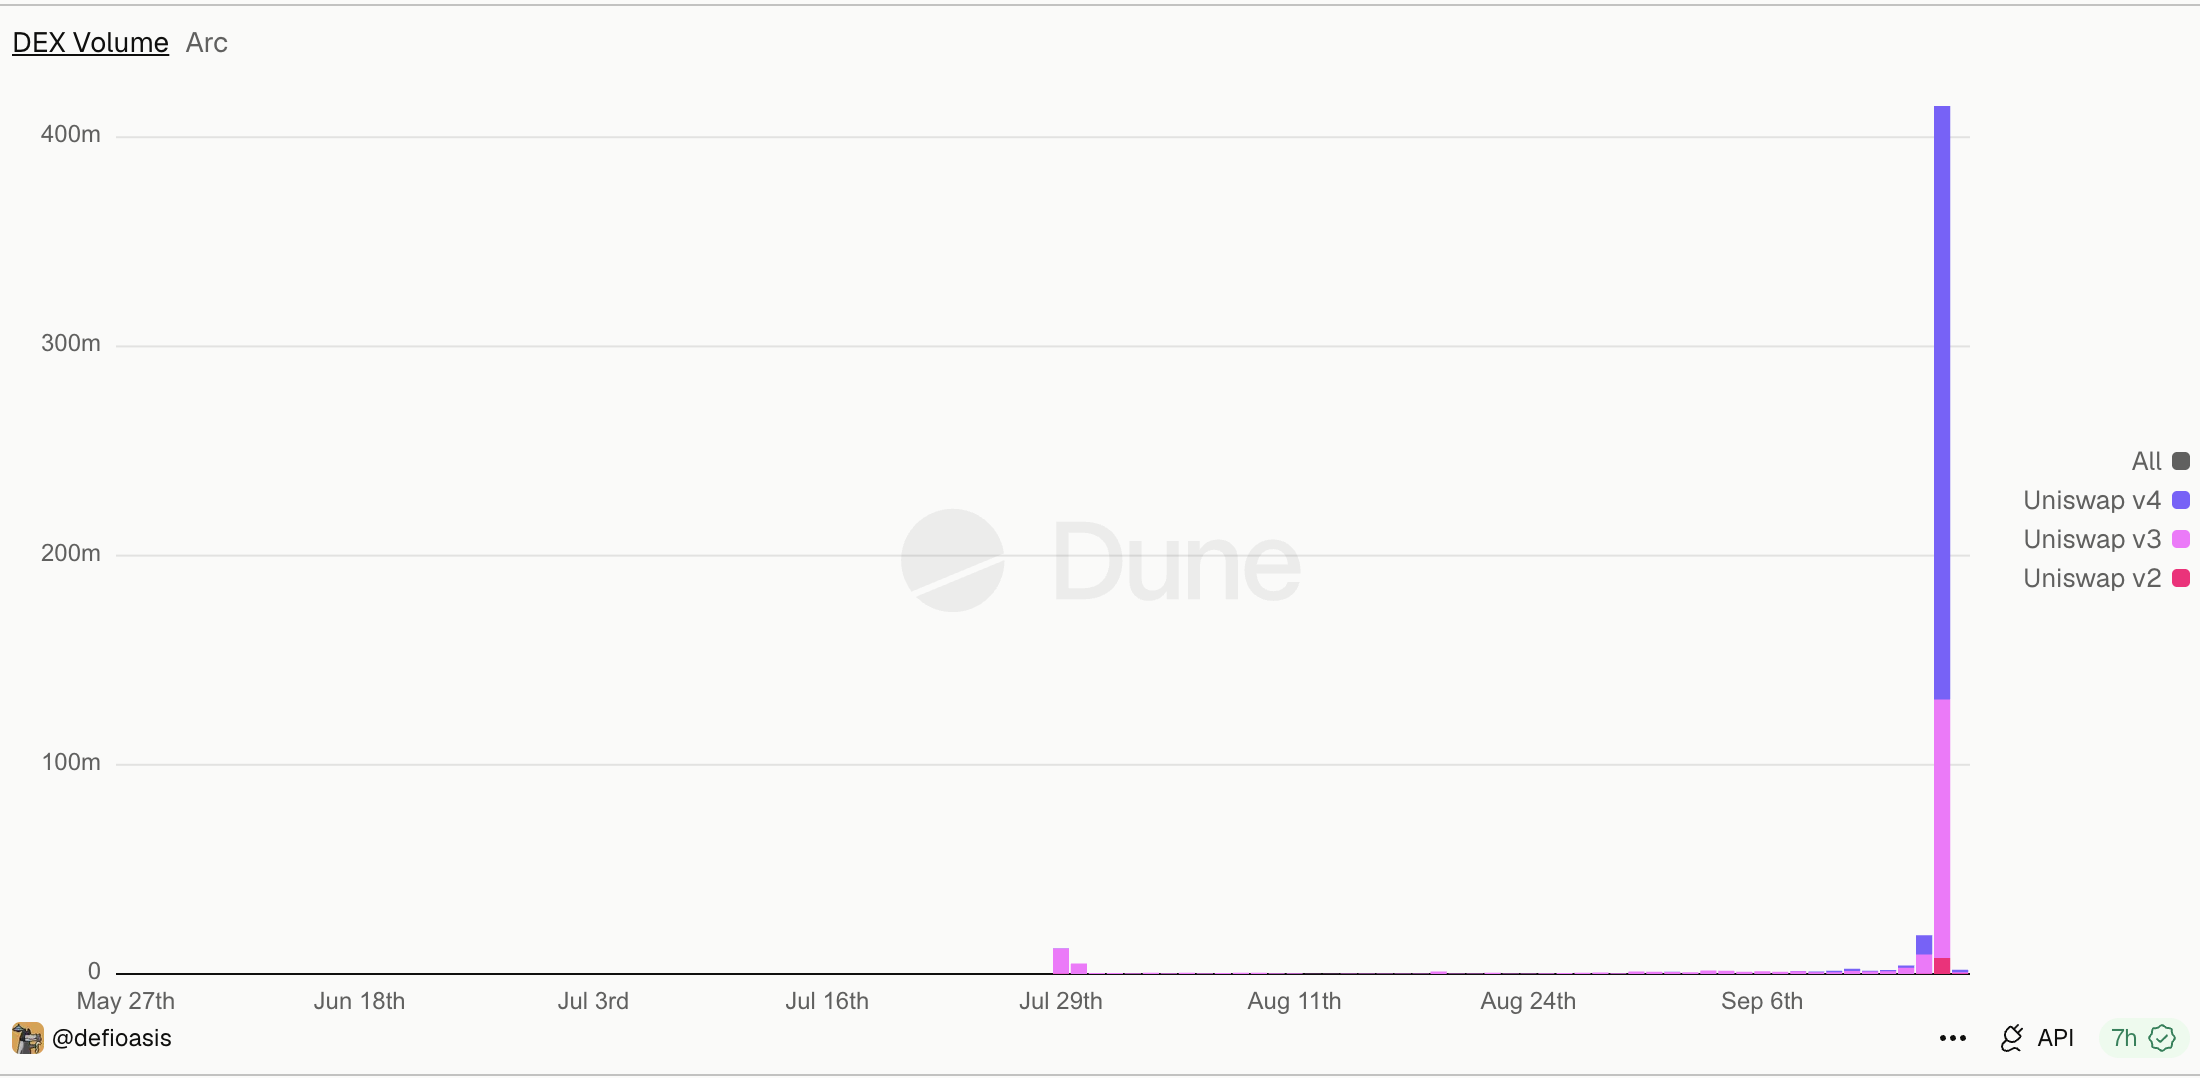
Meanwhile, as the ecosystem tokens of Arc generally experienced significant pullbacks, on-chain liquidity also declined, leaving the sustainability of the short-term trading frenzy uncertain. For Uniswap, whether Arc can further convert short-term traffic entry into stable trading volume and continuous revenue like Robinhood Chain still awaits validation from future market performance.
New Chain Traffic Supports V4 Growth, Hook Mechanics Exposed to Malicious Risks
Uniswap has returned to the center of on-chain liquidity competition, and the rise of V4 is becoming an undeniable driving force. Among them, Hook, as one of the core innovative mechanisms of V4, is gradually becoming an important growth point for Uniswap.
Blockworks data shows that Uniswap v4 is steadily narrowing the trading volume gap with v3, with its latest weekly trading volume accounting for 48%, close to v3's 52%. In terms of fee revenue, v4's weekly fee income has risen from 8% at the end of July to 25%, while v3's during the same period has dropped from 87% to 67%.
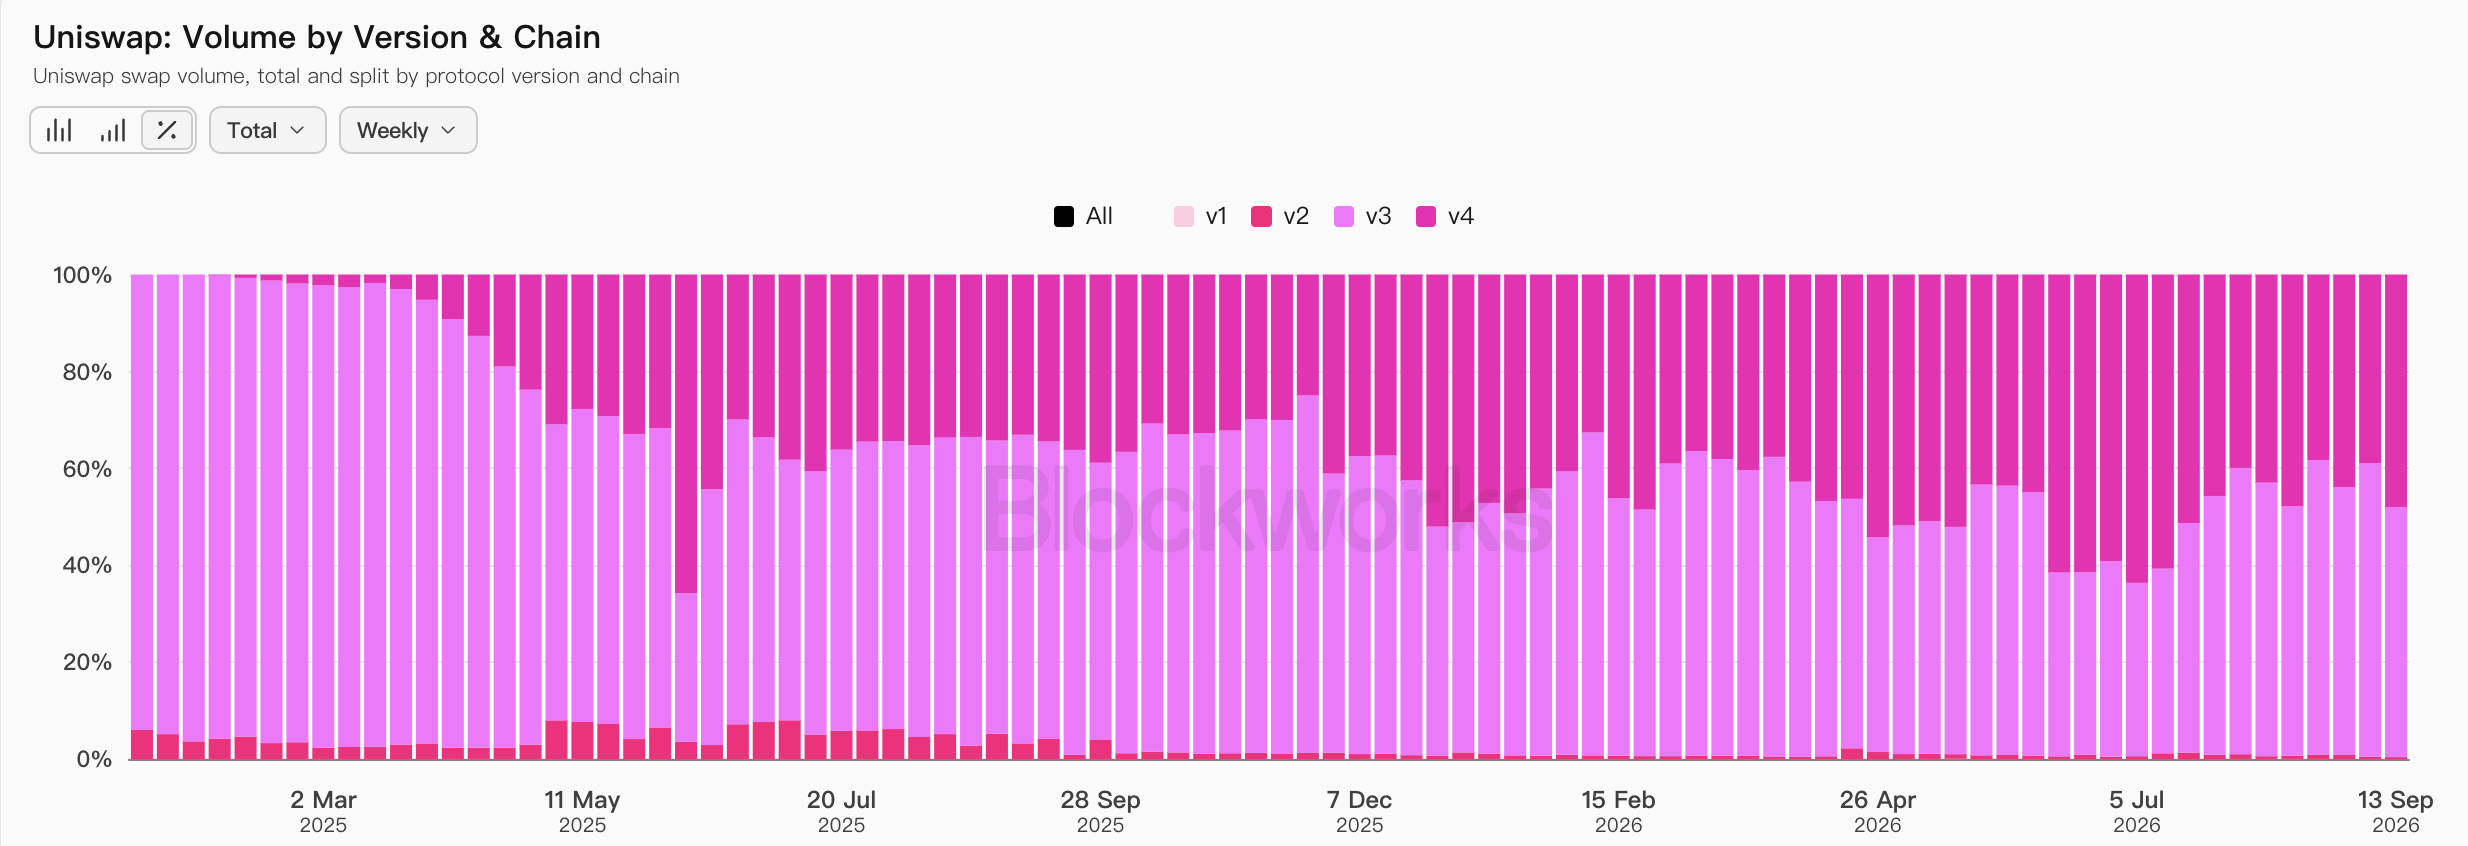
The penetration speed of V4 onto new chains is also noteworthy. On Robinhood Chain, the weekly trading volume share of v4 has reached 42%; on Base, this ratio is 11%, with both Arbitrum and Optimism at 18%. Even on the recently launched Arc, v4’s daily trading volume contribution has reached 29.7%.
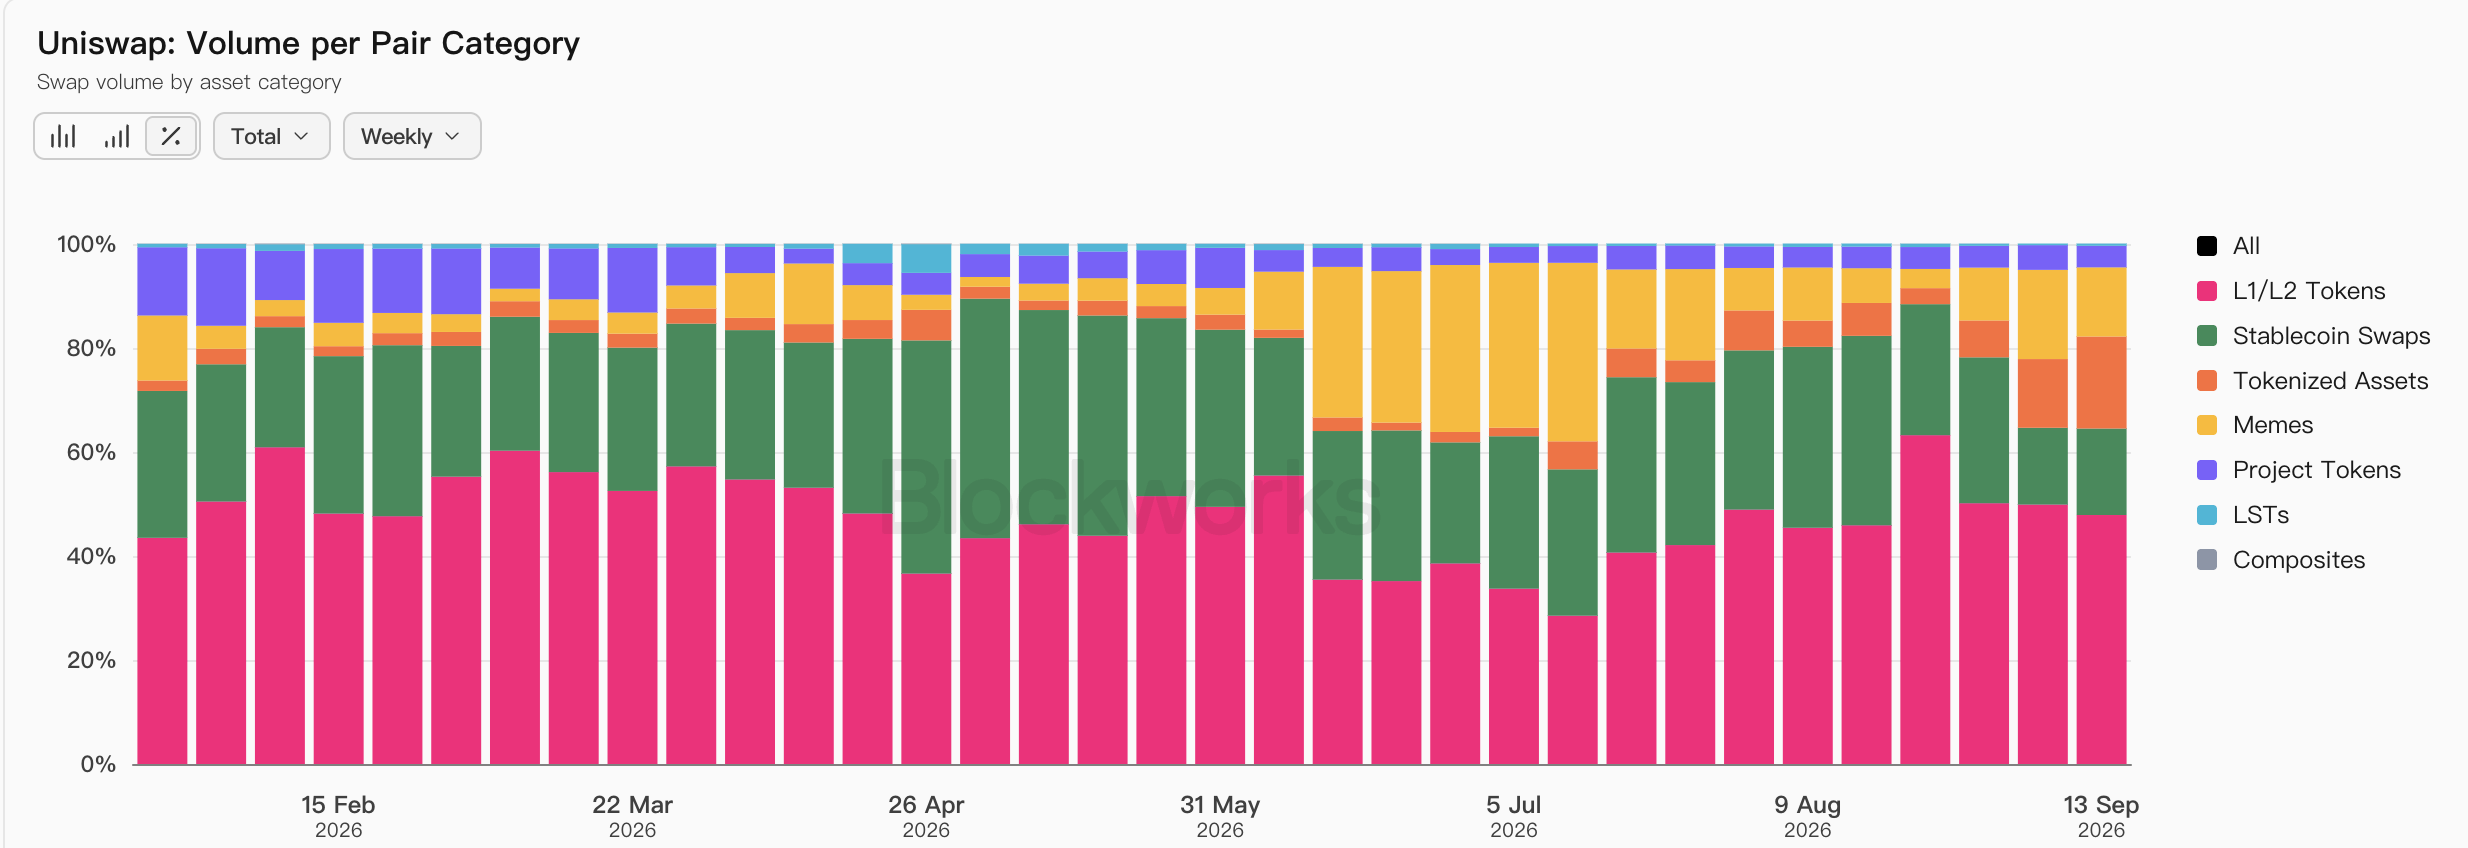
In addition to continuously increasing market share, v4's trading asset structure is also changing. In July, v4 trading was mainly focused on meme coins, stablecoins, and L1 and L2 tokens; by August, stablecoins, tokenized assets, and meme coins became the main trading types, with the share of meme coin transactions declining compared to the previous month. Stablecoins continue to hold an important position in v4 trading due to the underlying execution efficiency and fee structure of this version aligning better with the needs of stablecoin trading.
With the rapid expansion of the v4 version, Hook transactions are also accelerating in growth. Blockworks data reveals that the majority of trading activity in v4 still stems from regular liquidity pools, yet Hook-related transactions have been climbing steadily since August, currently accounting for 44%, whereas they were previously in the single digits.
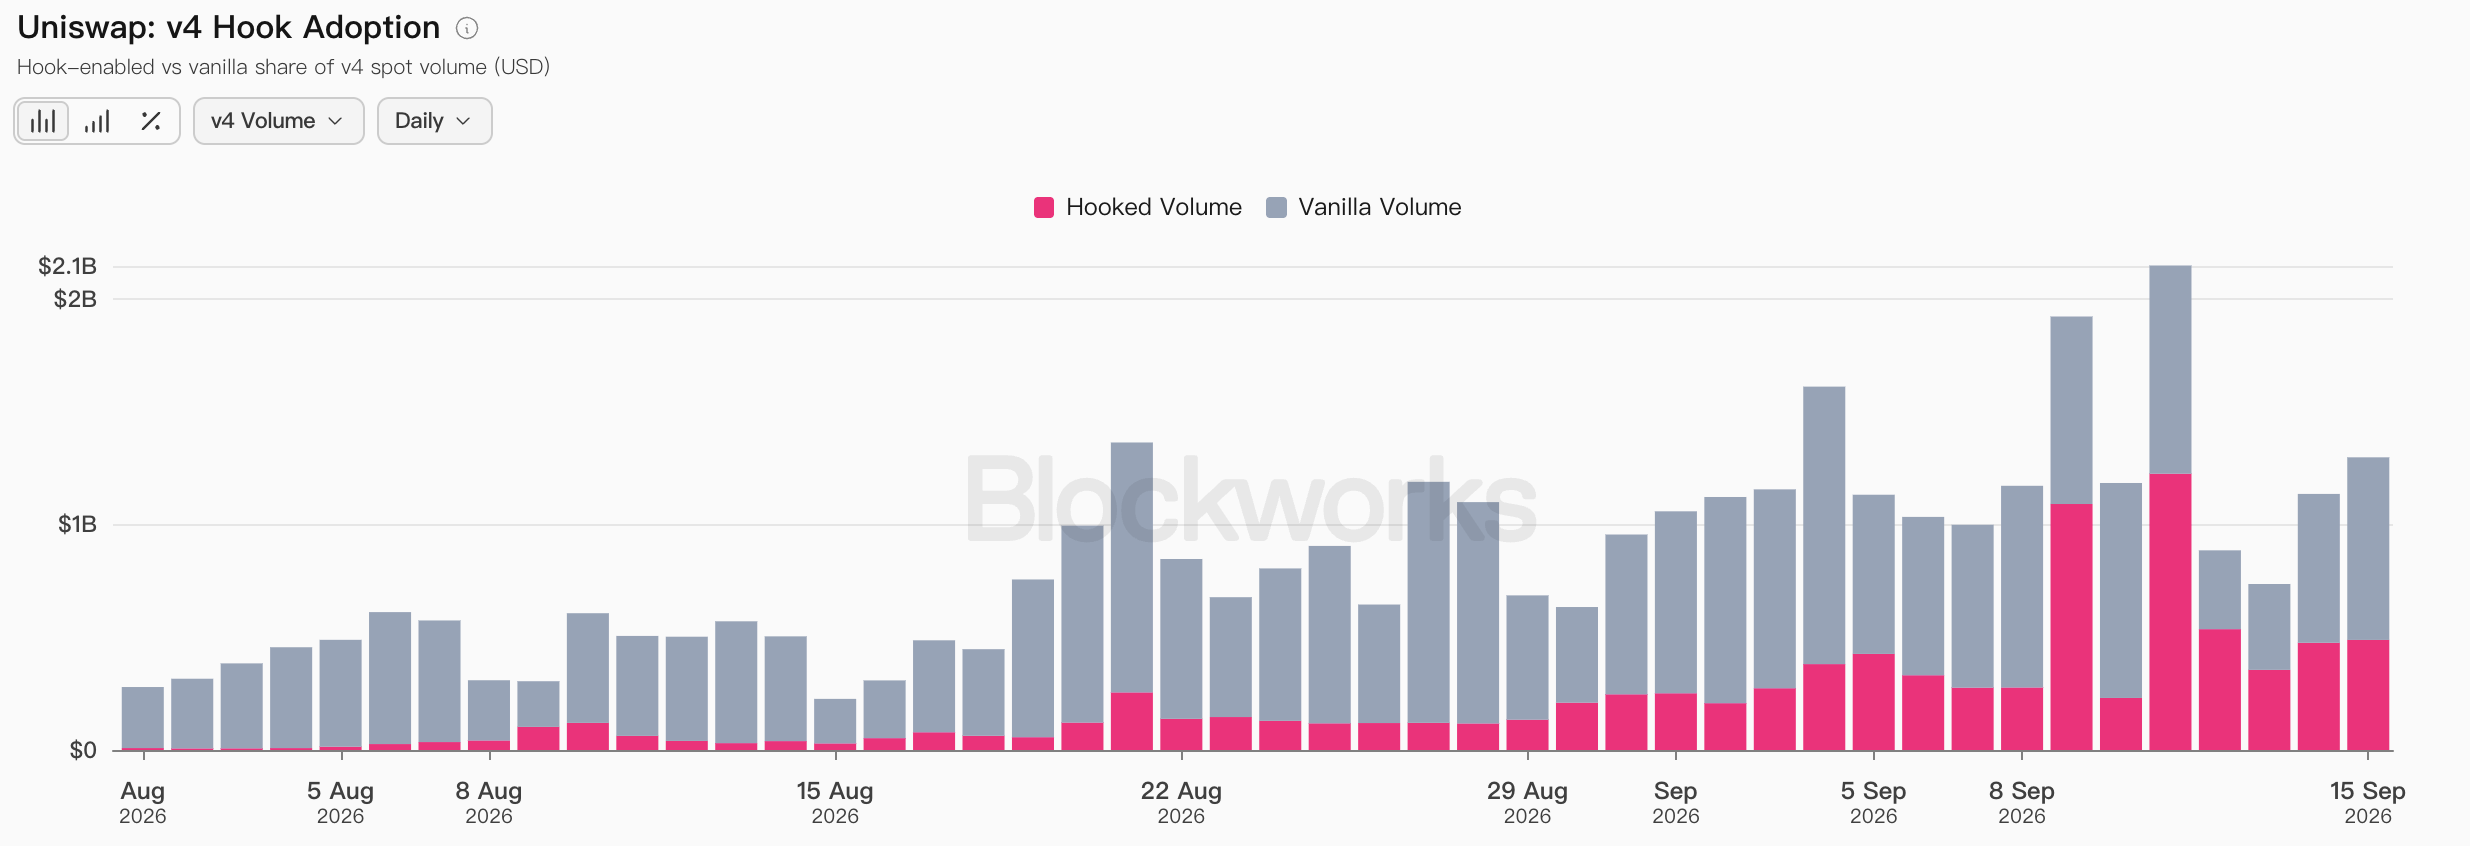
Hook allows developers to customize dynamic fees, token issuance mechanisms, RWA, and permissioned pools for liquidity pools based on different assets and trading scenarios. Compared with v3’s relatively fixed fee configurations, v4 offers more flexible trading mechanisms, enabling liquidity pools to be tailored to specific scenarios.
Robinhood Chain is an example. As an L2 focusing on tokenized stocks and other assets, its Uniswap v3 and v4 cumulative trading volumes reached $24.3 billion and $23.35 billion, respectively, nearing equivalent scales. In the latest weekly trading volume, v3 accounted for 58%, while v4 reached 42%, indicating the gap between the two has been narrowing since the initial launch. This suggests that v4's growth is not solely a migration of trading due to version updates but also related to the emergence of new chains, new assets, and customized trading demands. As more assets and trading scenarios enter the chain, the Hook mechanism will also provide Uniswap with more opportunities to expand liquidity scenarios.
However, as the application scale of v4 and Hook expands, associated security risks have begun to attract attention. The 0x protocol recently stated that it has observed a significant increase in malicious Uniswap v4 hooks. These types of hooks may show favorable prices during the quote request phase but alter the actual execution price during trade settlement, misleading aggregators, wallets, and trading applications, ultimately harming user interests.
0x reported that this year it has routed 81.92 million transactions, with a total trading volume of $42.67 billion, approximately 70% of which involved Uniswap liquidity. The protocol conducted static analysis, dynamic analysis, and transaction data observation on 84,163 hooks across six chains and determined that only 19.4% qualify as safe hooks, while 54.2% were categorized as malicious, and another 26.4% potentially exhibit malicious behavior.
The protocol also pointed out that some malicious hooks distinguish between quote requests and real trading scenarios by detecting the Ethereum Virtual Machine (EVM) environment or using mechanisms like random fees. This means that the price users see in the quote phase may not be realizable at settlement, with the actual asset value received potentially being up to 50% lower than the quoted price. In response to this issue, 0x stated that it has implemented advanced detection and liquidity pool review measures to prevent relevant pools from entering its routing system and reminded routers, applications, and users to verify that the quoted prices align with actual execution results.
In response, Uniswap founder Hayden Adams stated that the so-called "routing to bad hooks" issue falls under technical mismanagement, and the team could seek assistance to address it. He emphasized that Uniswap v4 hooks have unleashed significant innovative potential and recommended developers utilize the Uniswap API. He noted that the Uniswap API supports retrieving the best market prices, avoiding malicious hooks, and can access all Uniswap liquidity without charging additional routing fees. Furthermore, the API supports cross-chain swaps and integrates external liquidity through aggregator hooks, further expanding to be a complete aggregator.
From the rise in v4 trading share to the continuous increase in Hook trading share, Uniswap is expanding into new chain and asset markets through more flexible liquidity mechanisms. However, as the customization features continue to expand and asset boundaries broaden, the balance between innovation and security will become a challenge that Uniswap must address.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


