A debt settlement that has been forcibly delayed.
Written by: Eric, Foresight News
On November 14, 2026, users of X named punkquidity discovered that the annualized interest rate of stUSDS on Sky had risen to 13%, but there were no funds to withdraw.
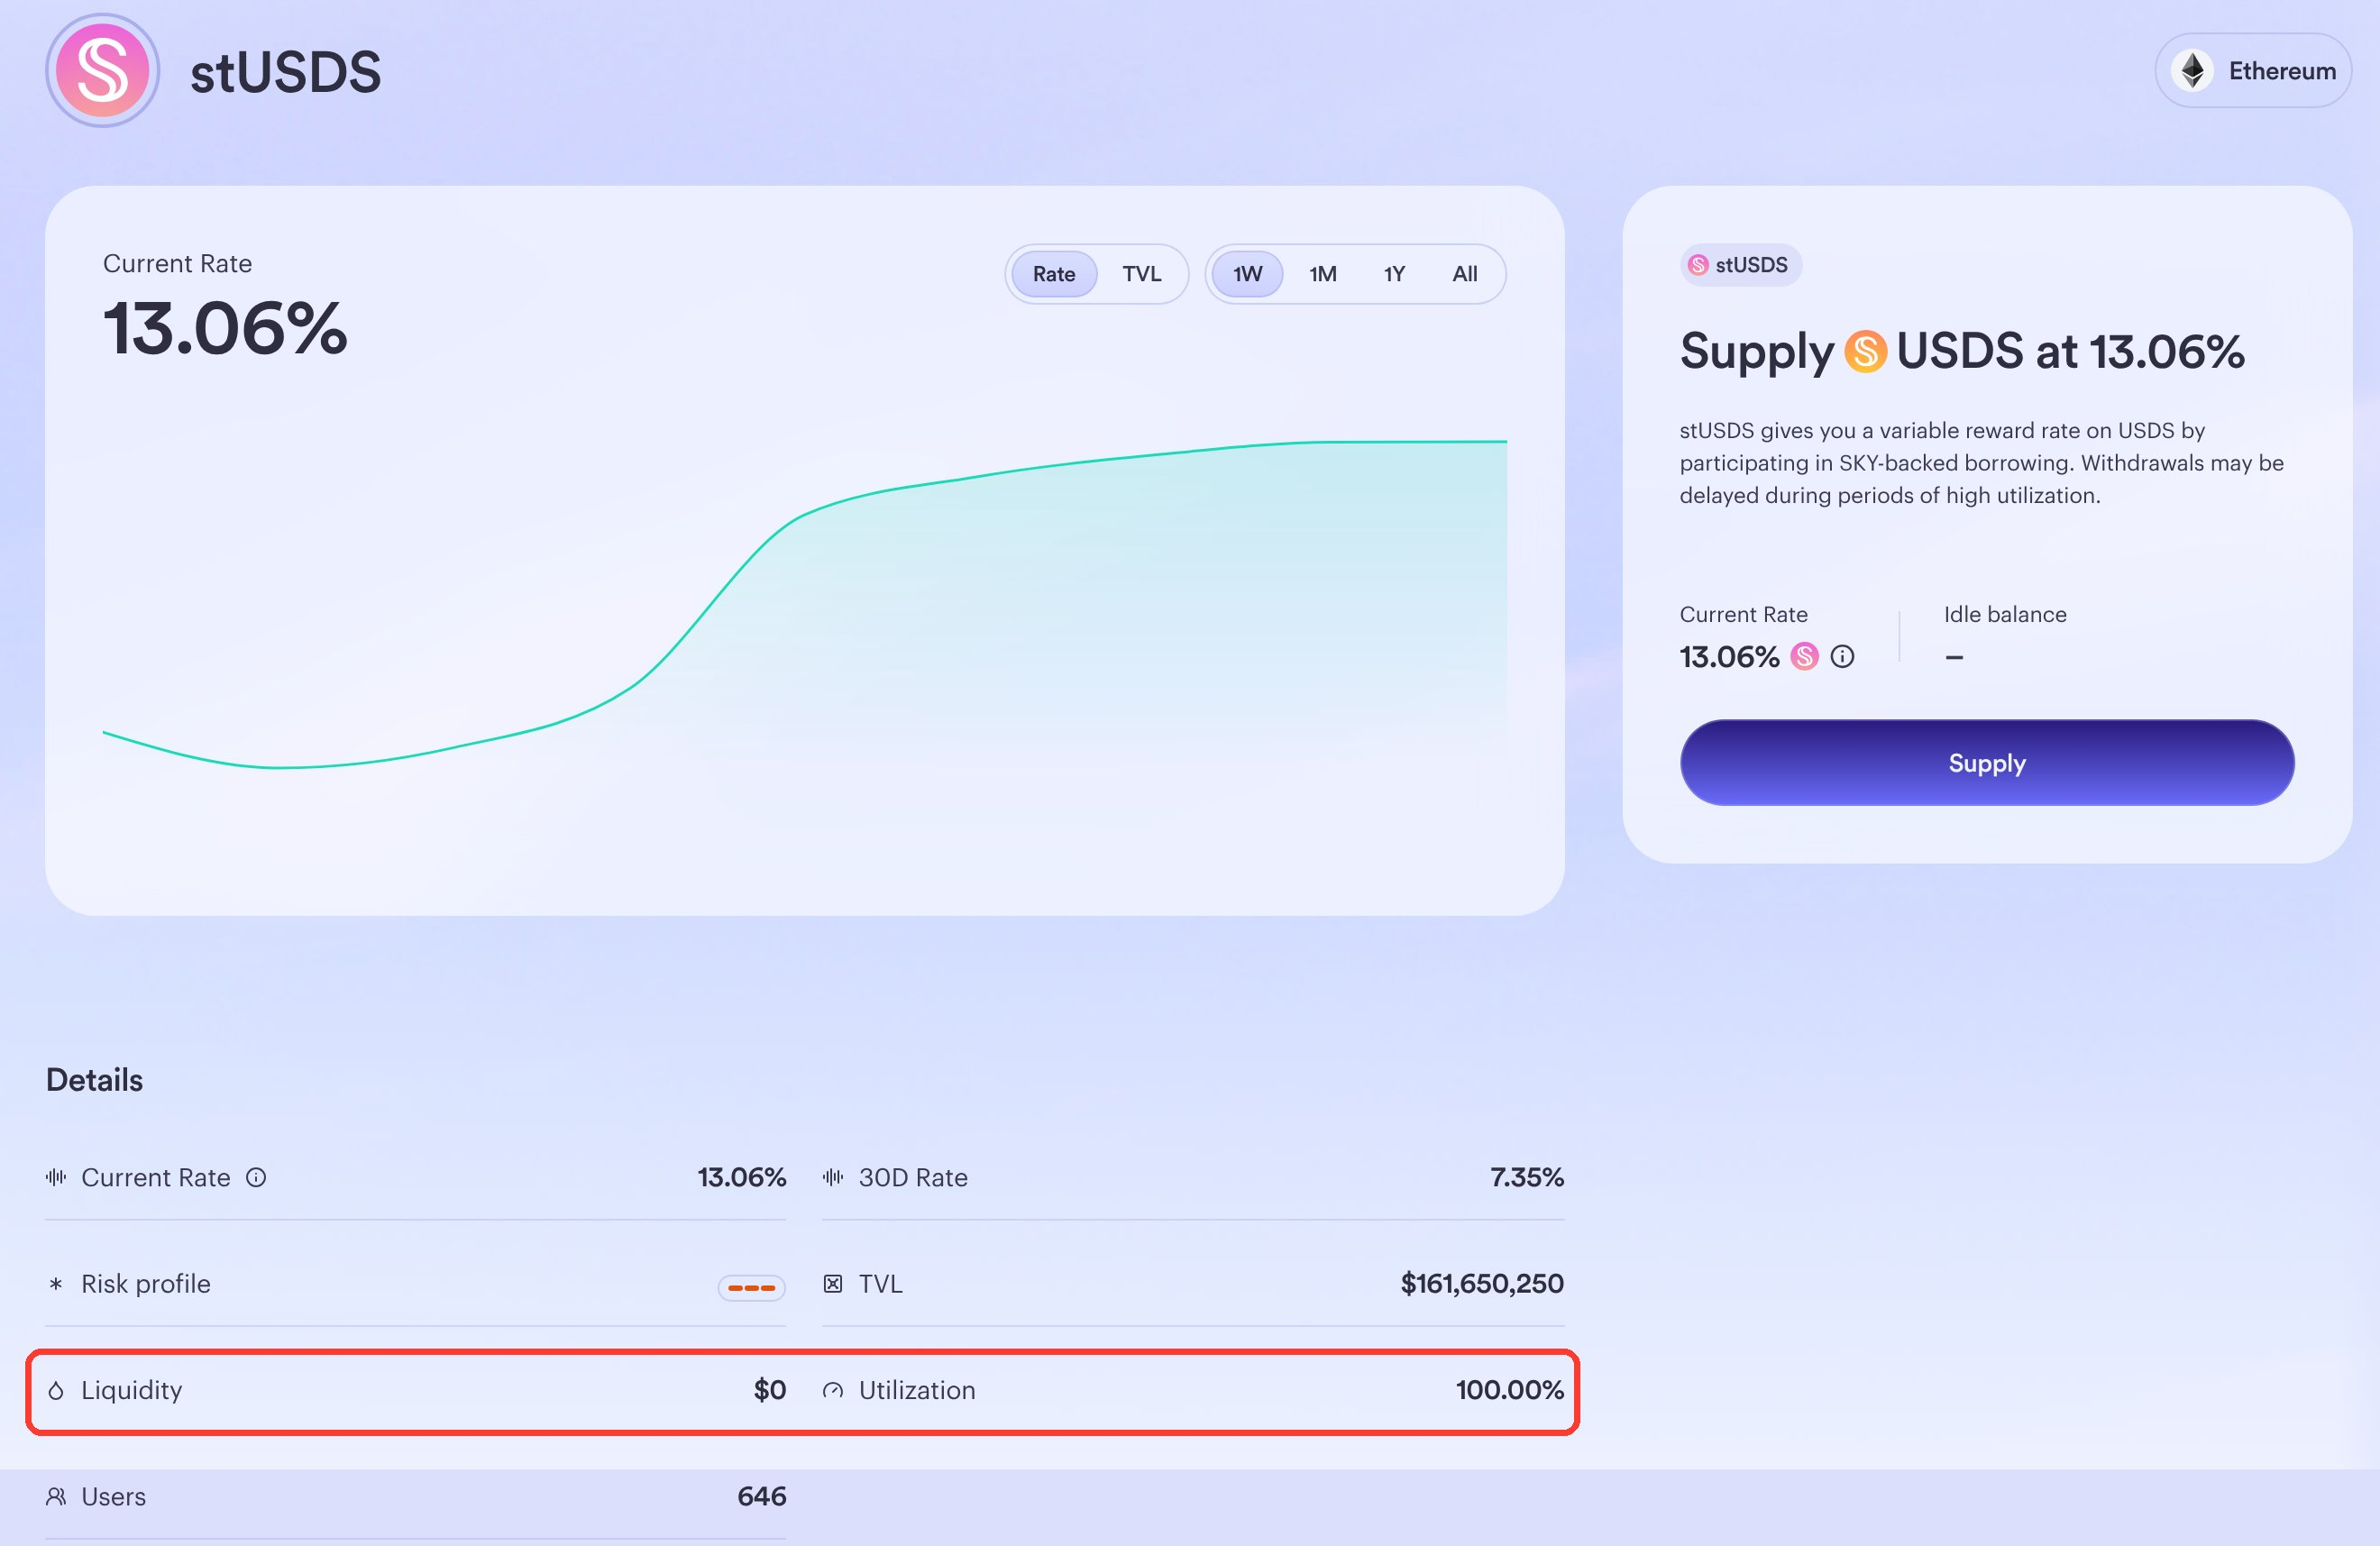
All the stUSDS in Sky were prepared to borrow USDS against collateralized SKY, allowing users to provide USDS and receive stUSDS as proof of earnings, while others could stake SKY to borrow USDS. Punkquidity further pointed out that on November 10, someone withdrew the last available USDS from the pool, and thereafter no one deposited USDS back into the pool.
One day later, punkquidity again reported that this emptied USDS pool had 48% of its debt, approximately 76.9 million USD, originating from the rune.eth address, which points to Sky co-founder Rune Christensen. A total of four borrowing positions had not made any repayments in six months, and three of them had already fallen below the liquidation threshold.
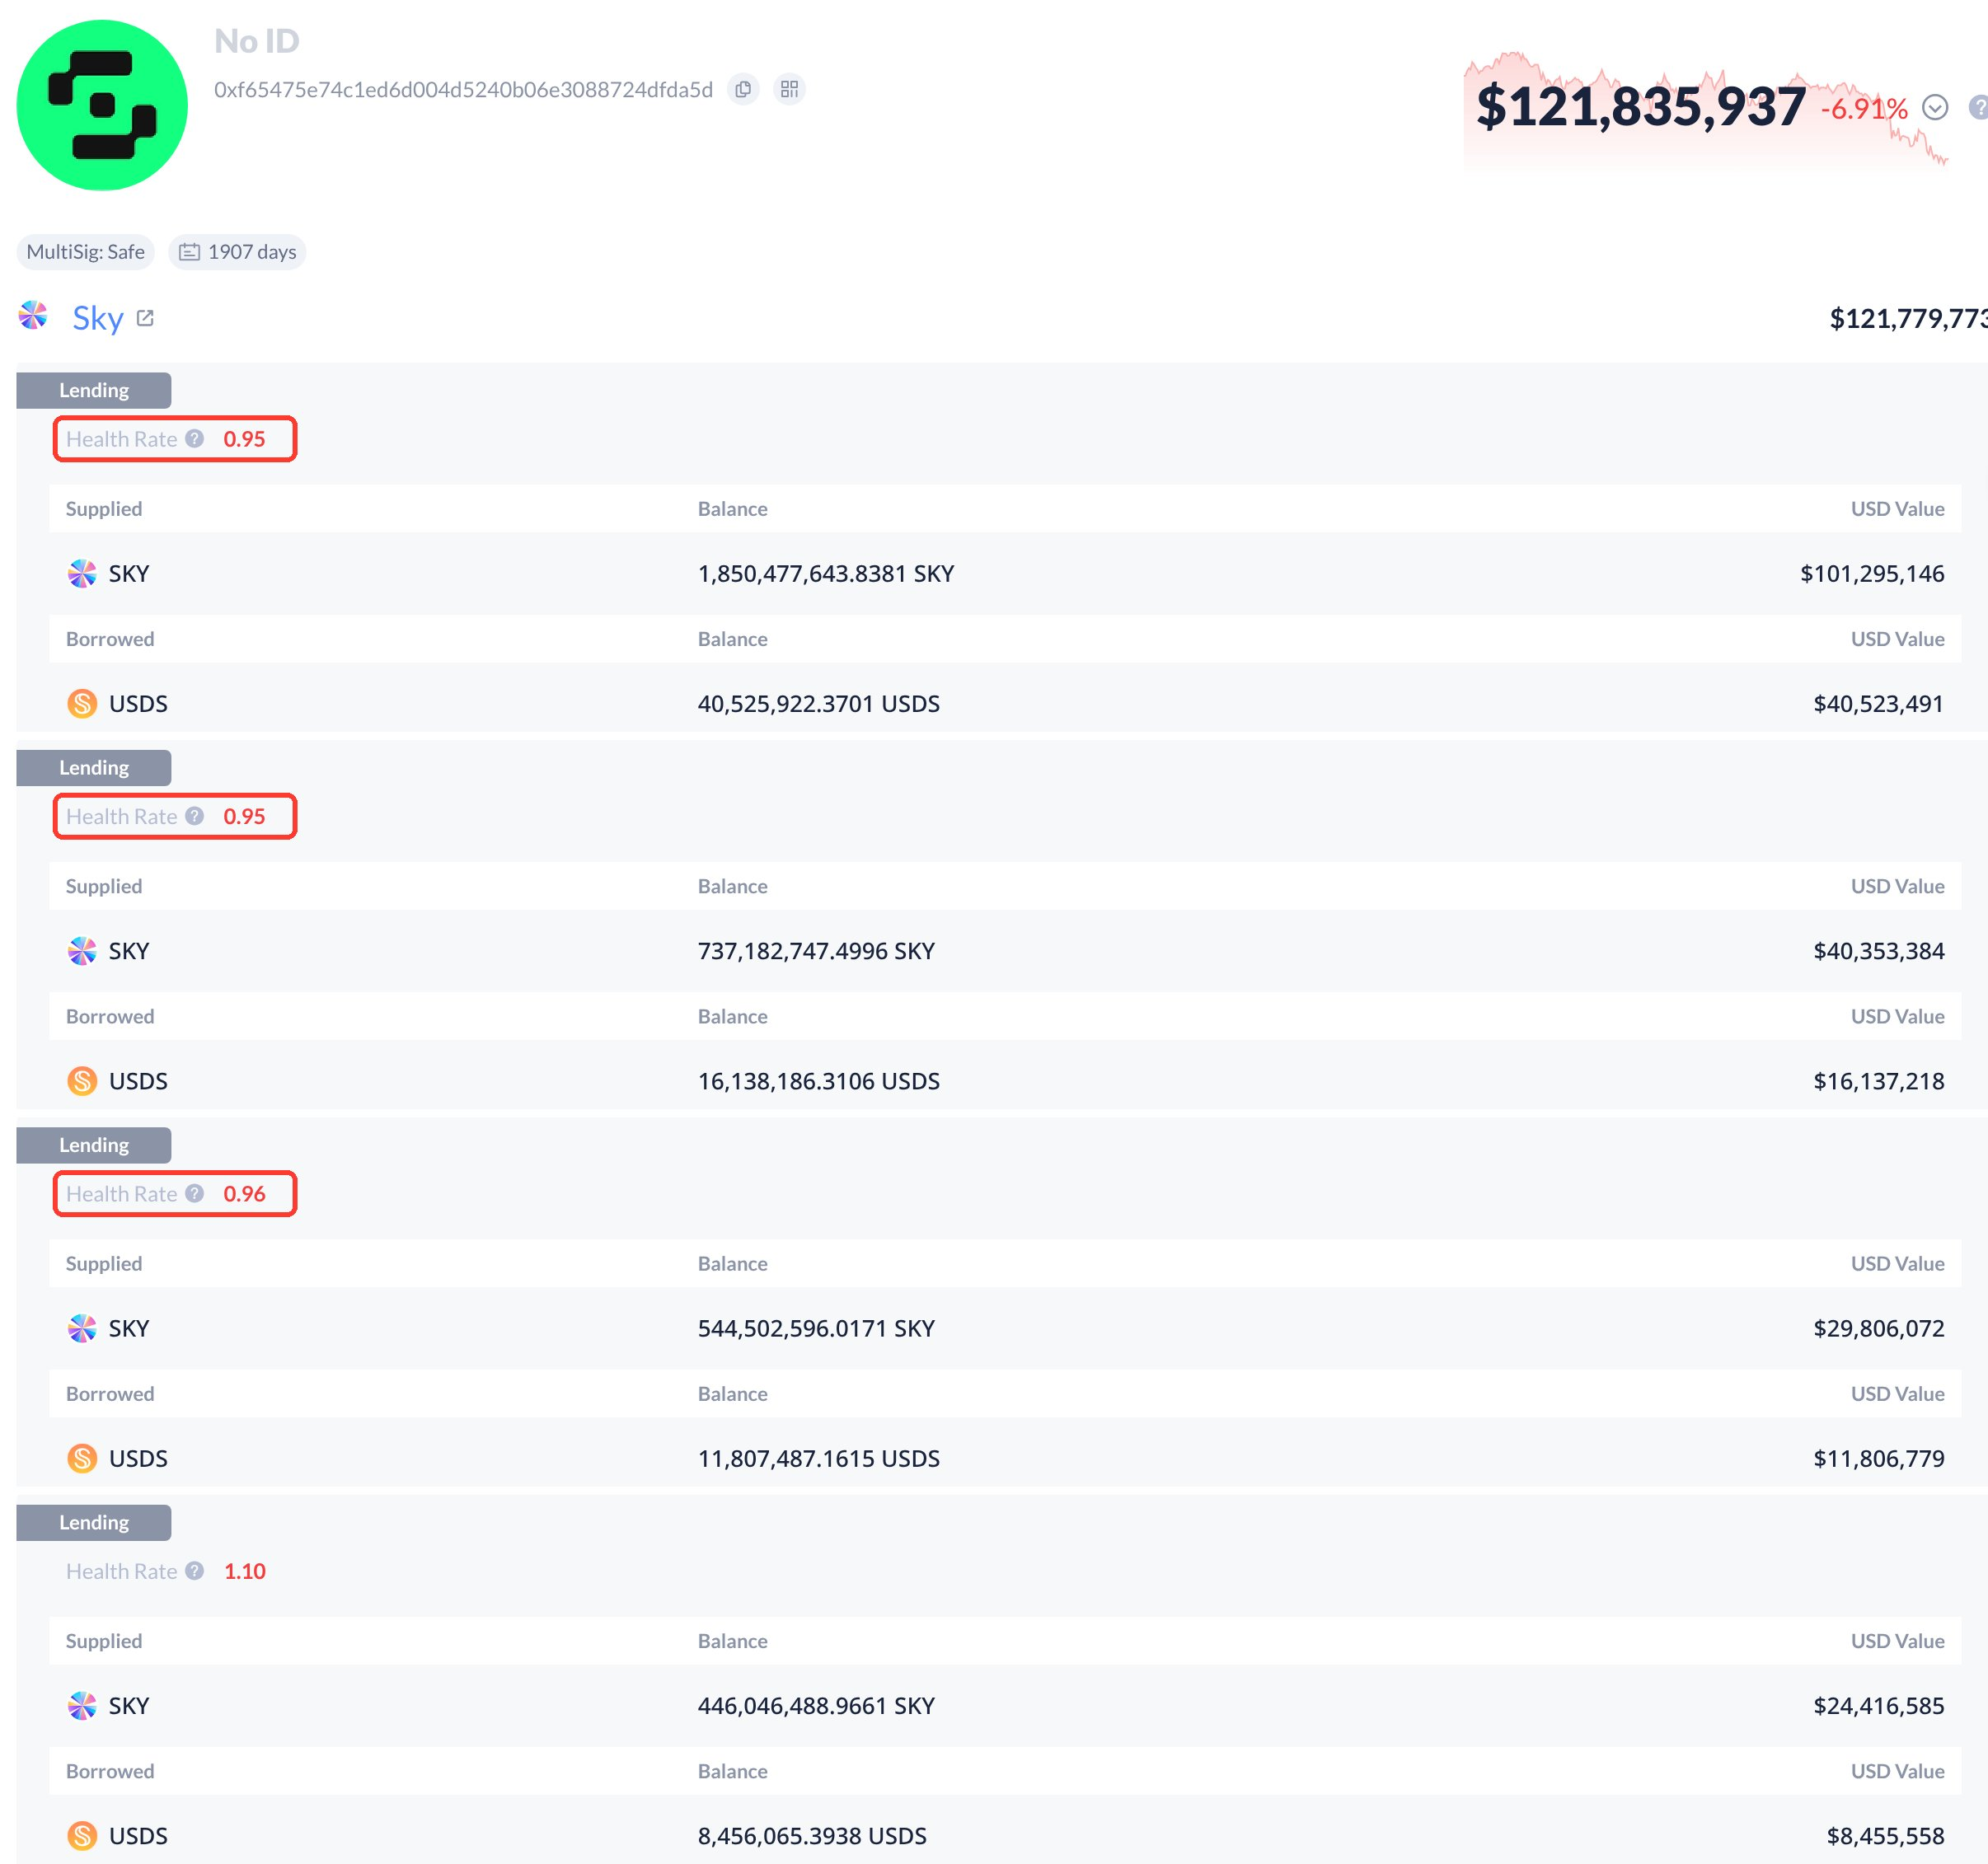
Upon verification, as of the time of writing, this borrowing pool still had no liquidity available to exit USDS, and the interest rate of stUSDS had risen to 19.75%.
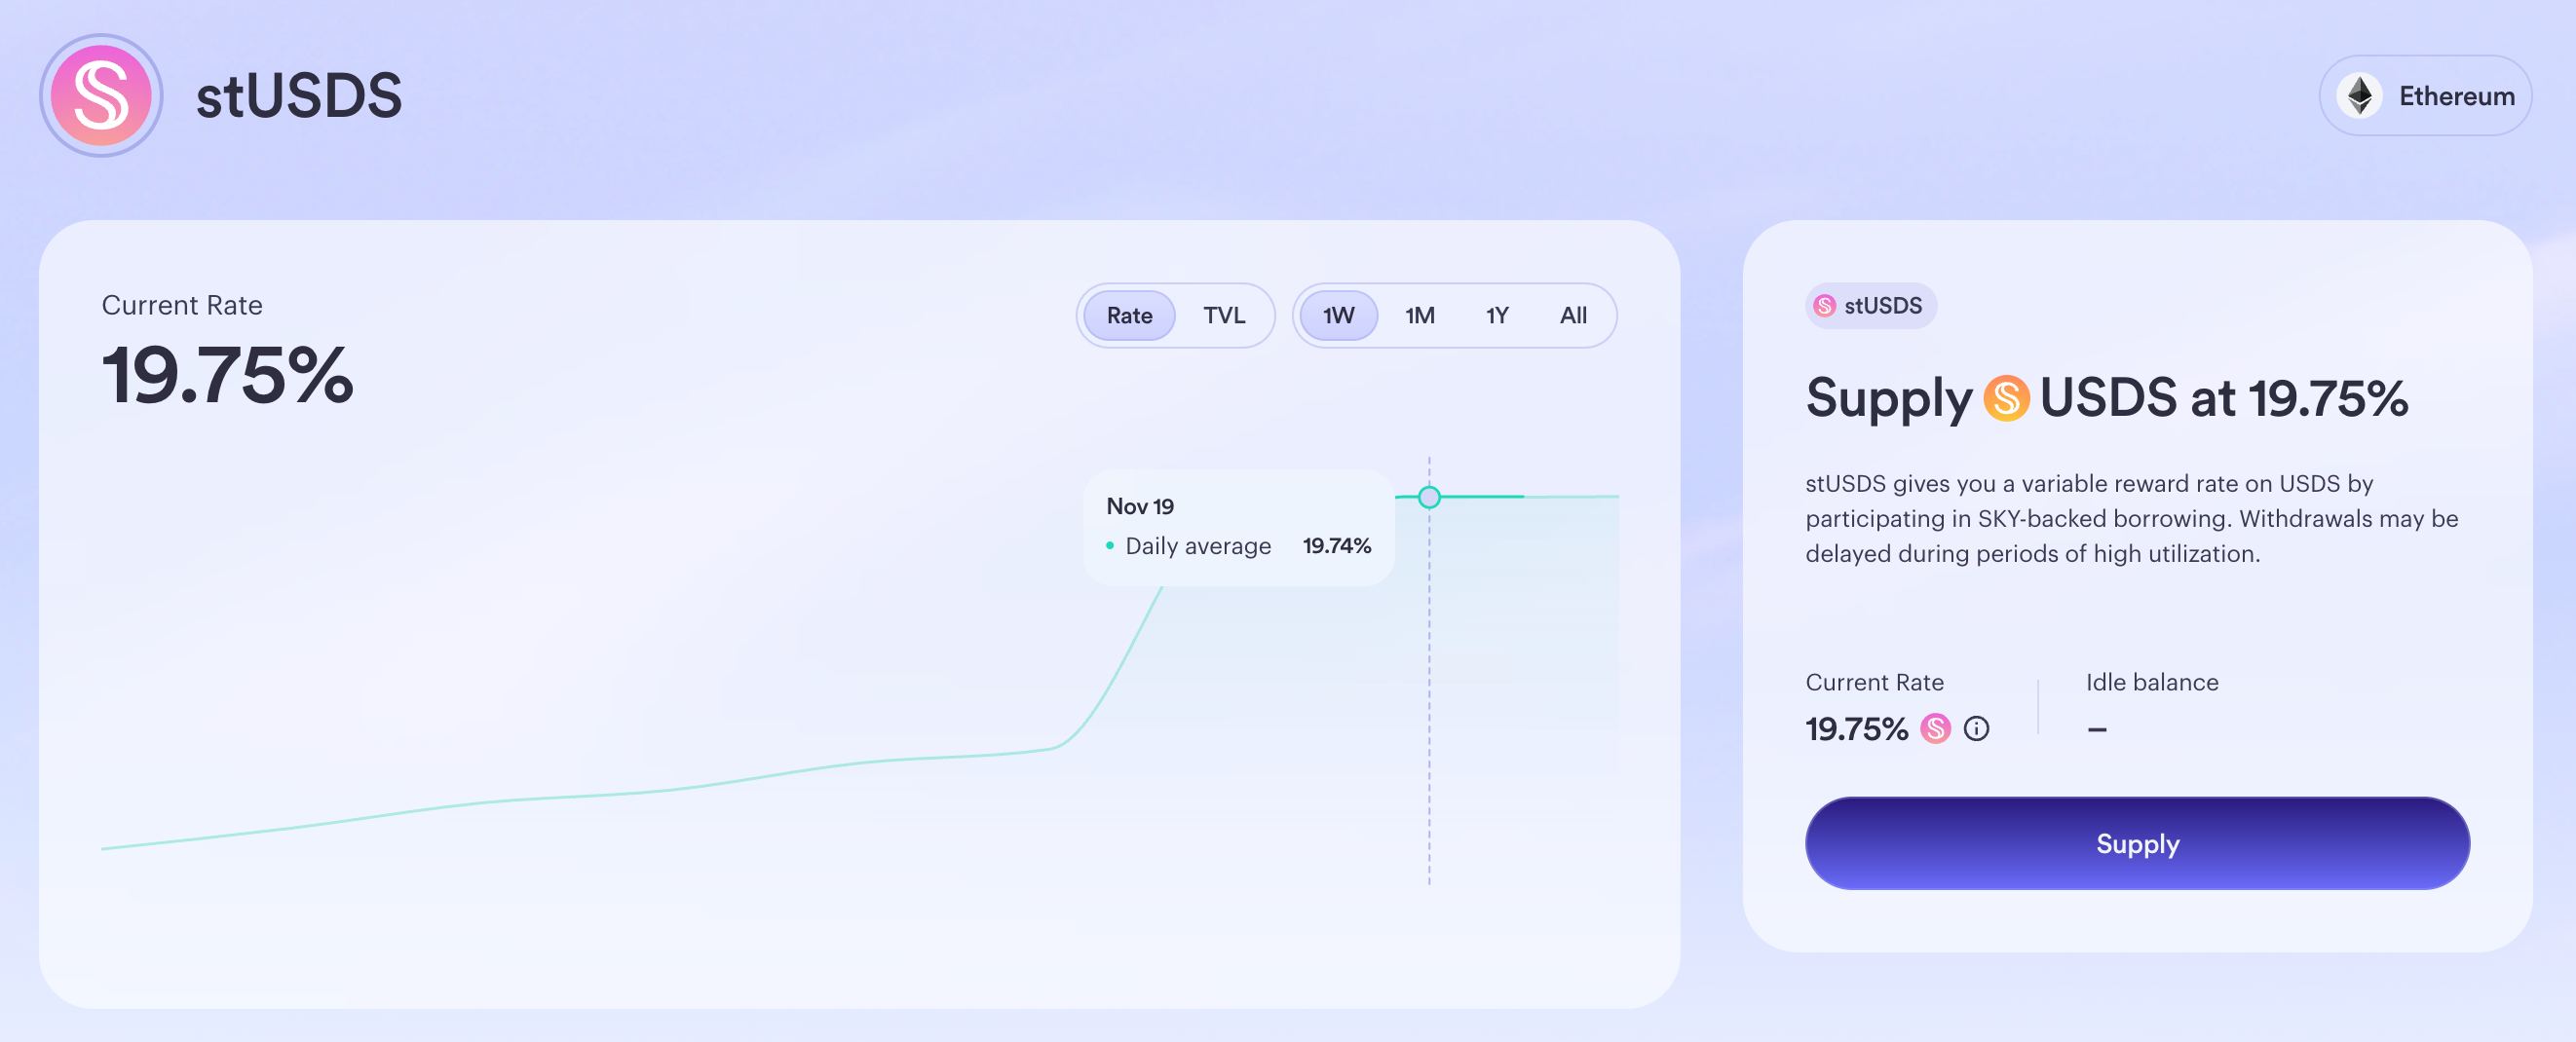
Discussions about this incident did not begin to heat up on X until November 18, with many believing that Sky likely had no liquidation of the founder's positions as a backdoor operation, but in fact, Sky had been preparing for this day since the second half of 2025.
In September 2025, Sky closed the automatic liquidation for the "stake SKY to borrow USDS" market, switching to manual liquidation. This action was taken to prevent a short-term liquidity vacuum when converting tokens from MKR to SKY, which could lead to token price manipulation and unnecessary liquidations.
By October 2025, as Sky's price began to decline along with the overall cryptocurrency market, Sky urgently conducted a series of operations.
In early October, Sky released the "Lockstake Capped OSM Wrapper," which aimed to set the Oracle price of Sky as the lesser of the market price and "a predetermined hard cap price," to prevent large loans while the SKY price was still relatively high, thereby increasing future liquidation risks.
On November 26, less than a month after the market experienced extreme liquidations, Sky adjusted the risk parameters again: lowering the liquidation threshold from 145% to 120% and adjusting the previous "hard cap price" down to 0.025 USD. This means that liquidation would only begin if the SKY token price fell below 0.03 USD.
Meanwhile, Sky planned to establish a Curve sUSDS/stUSDS pool, allowing depositors to exit at a discount even at 100% utilization. Subsequently, Sky also planned to expand liquidity sources through Morpho.
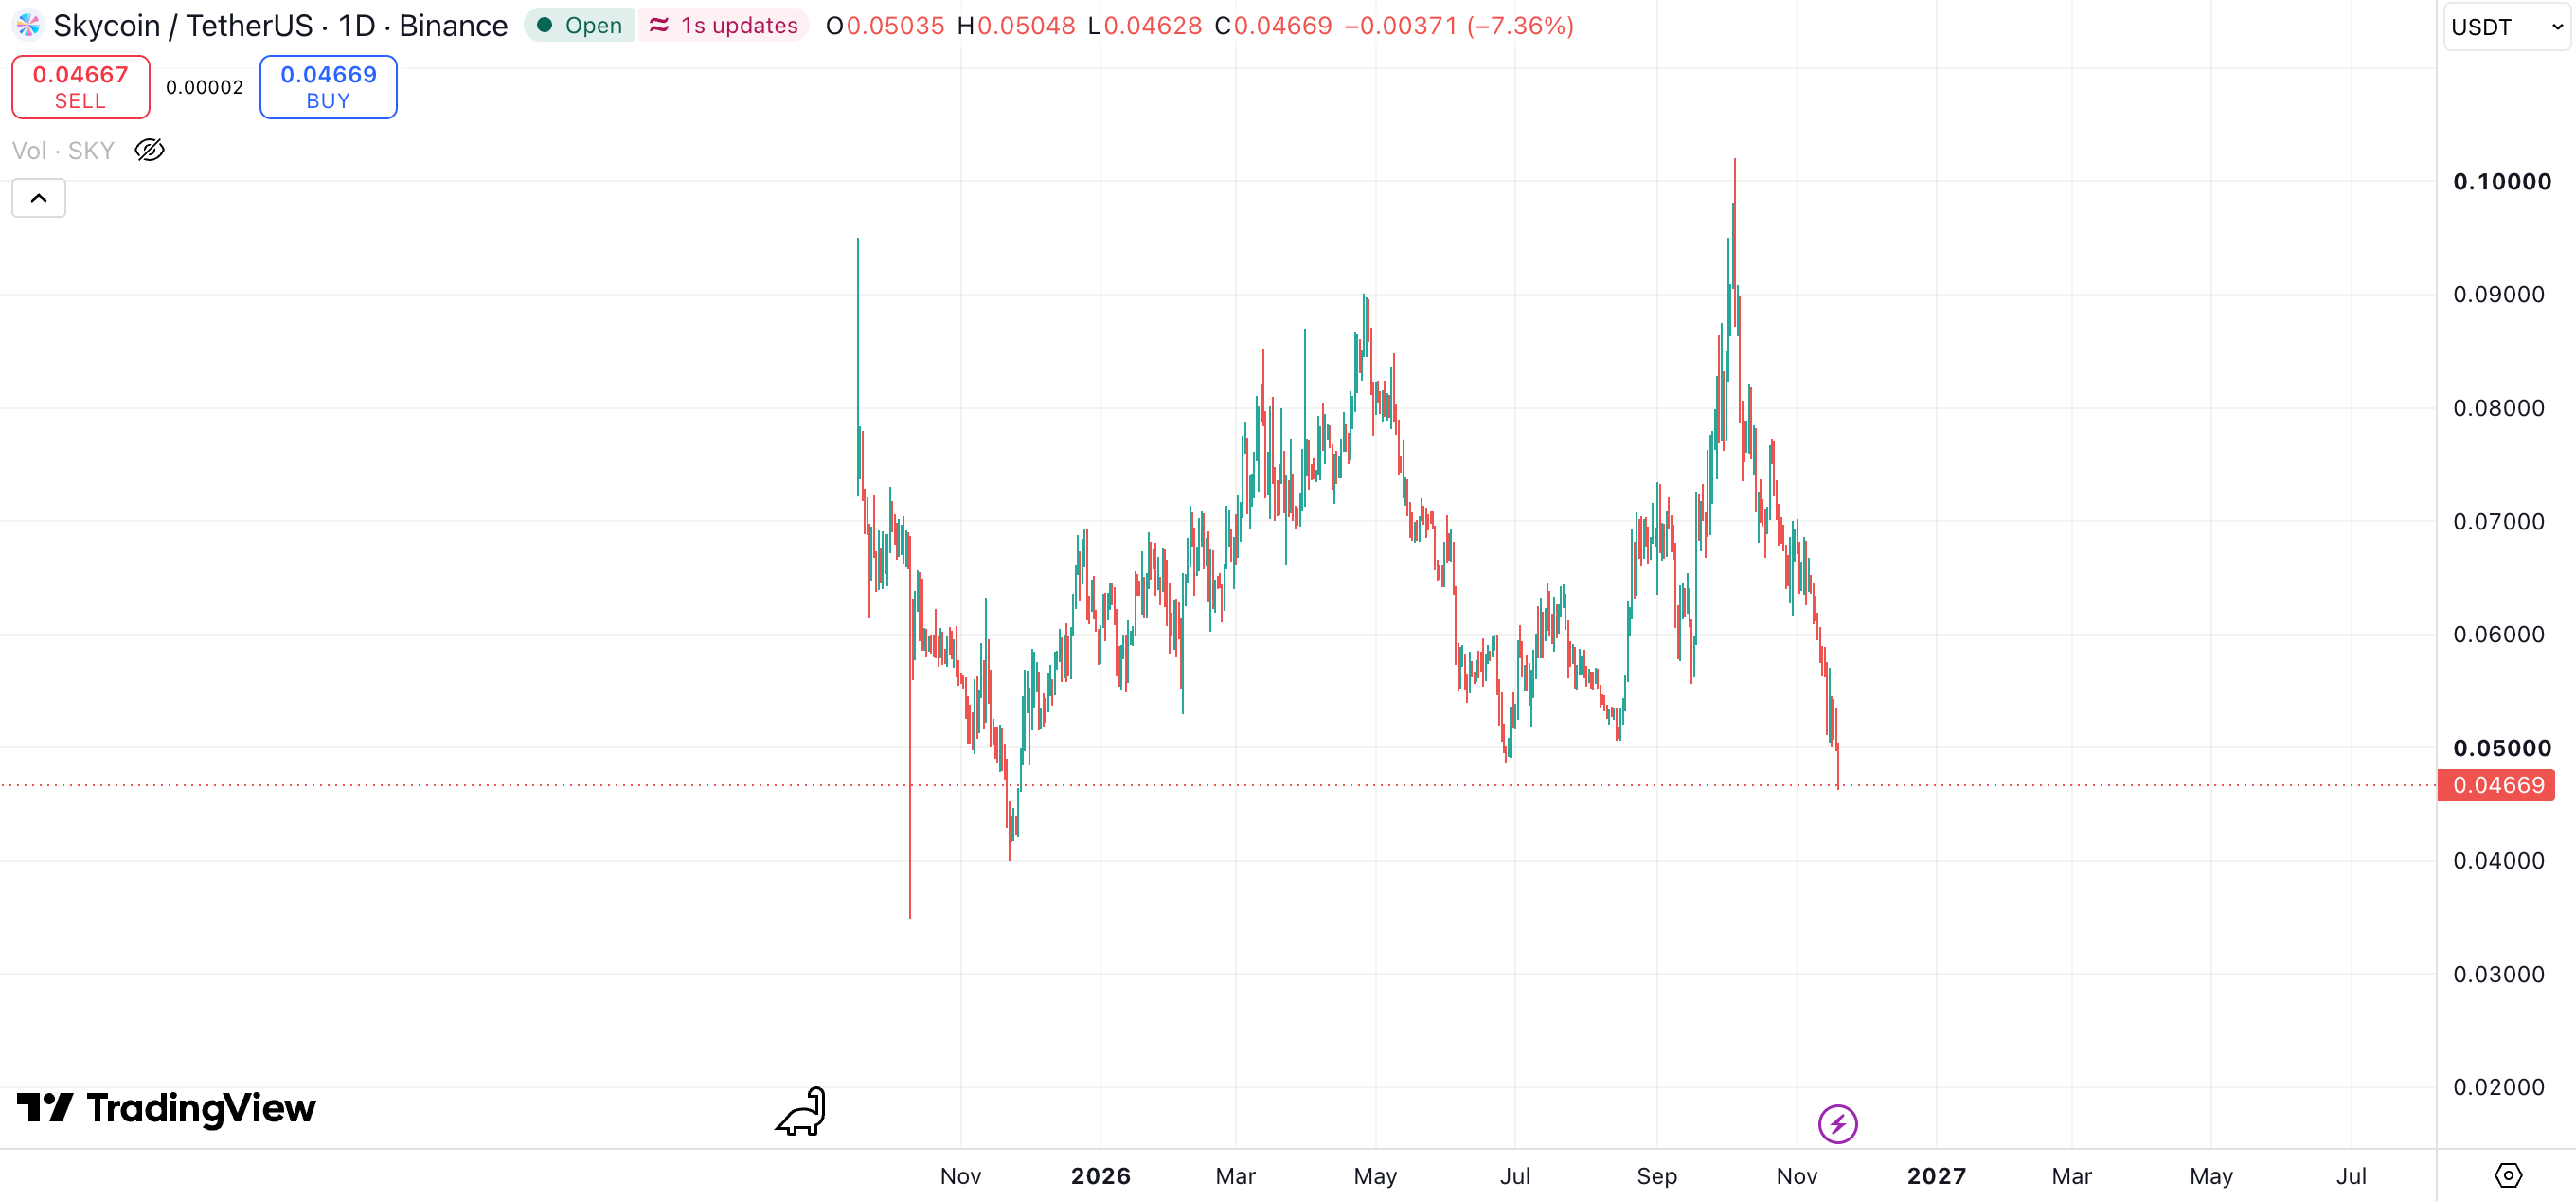
The timing of Sky converting tokens from MKR to SKY was right at the end of the bull market, which meant that SKY's liquidity was never good from the start. Currently, while Rune's positions are temporarily safe, if the cryptocurrency market continues to weaken, liquidation is inevitable.
DeBank might still use the 145% liquidation line, leading to some positions showing health metrics below 1. Overall, a series of operations in the latter half of last year made this SKY/USDS borrowing pool seem shaky; as long as SKY does not experience extreme price drops, this pool is unlikely to "explode."
However, another problem arises: whether rune.eth's significant cash-out using the rules is transferring risks onto the protocol and retail investors.
The USDS fund amount in the SKY/USDS borrowing pool exceeds 150 million USD. The withdrawal channels mentioned in last year's governance forum regarding Curve and Morpho now appear to be a drop in the bucket.
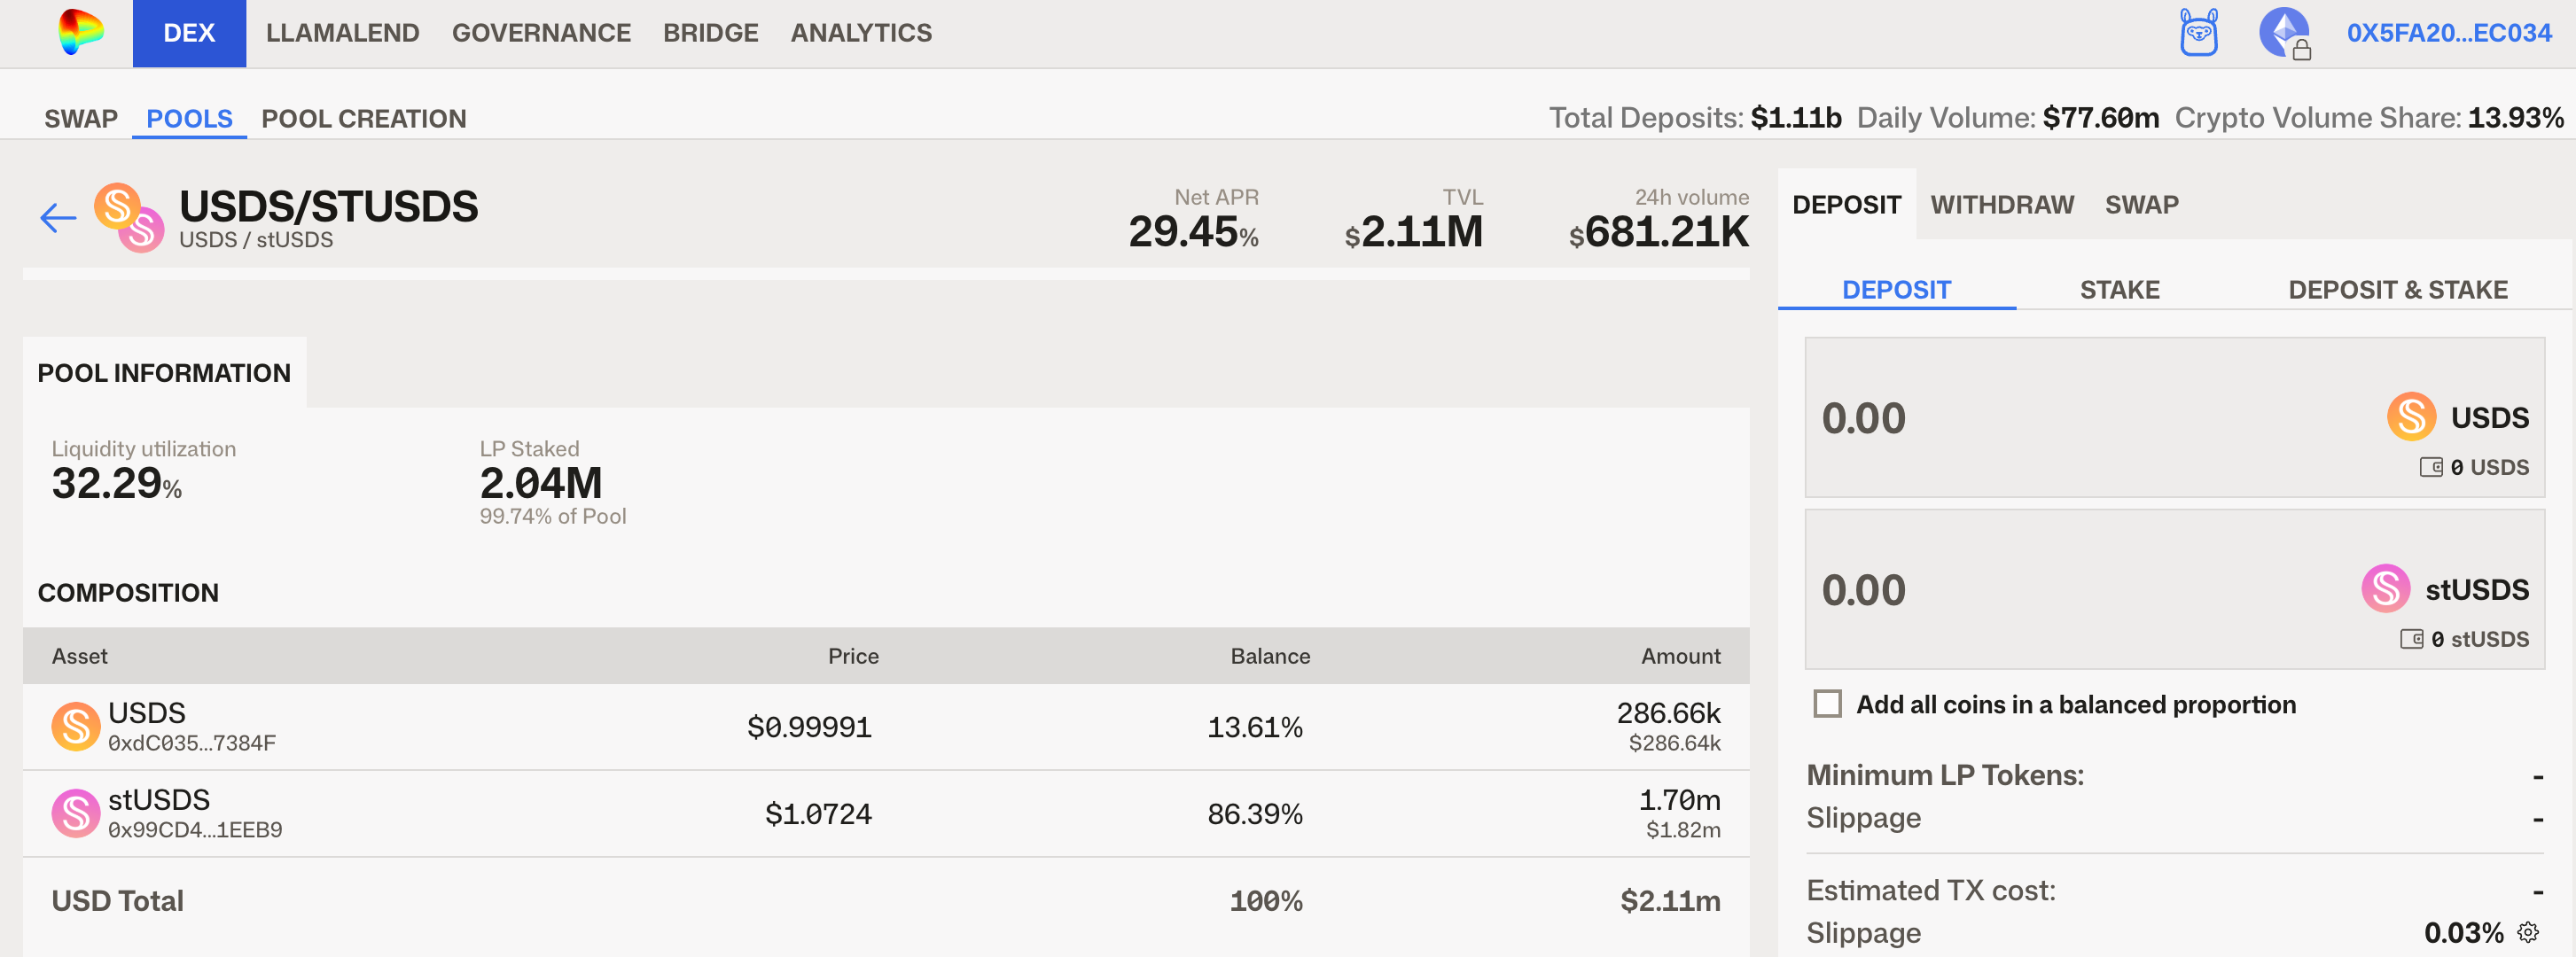
In the USDS/stUSDS liquidity pool on Curve, stUSDS accounts for over 80%, indicating that a large amount of USDS has been exchanged for stUSDS. On Morpho, the situation is even more apparent, as three liquidity pools of stUSDS exceeding 6.5 million USD have been completely drained.
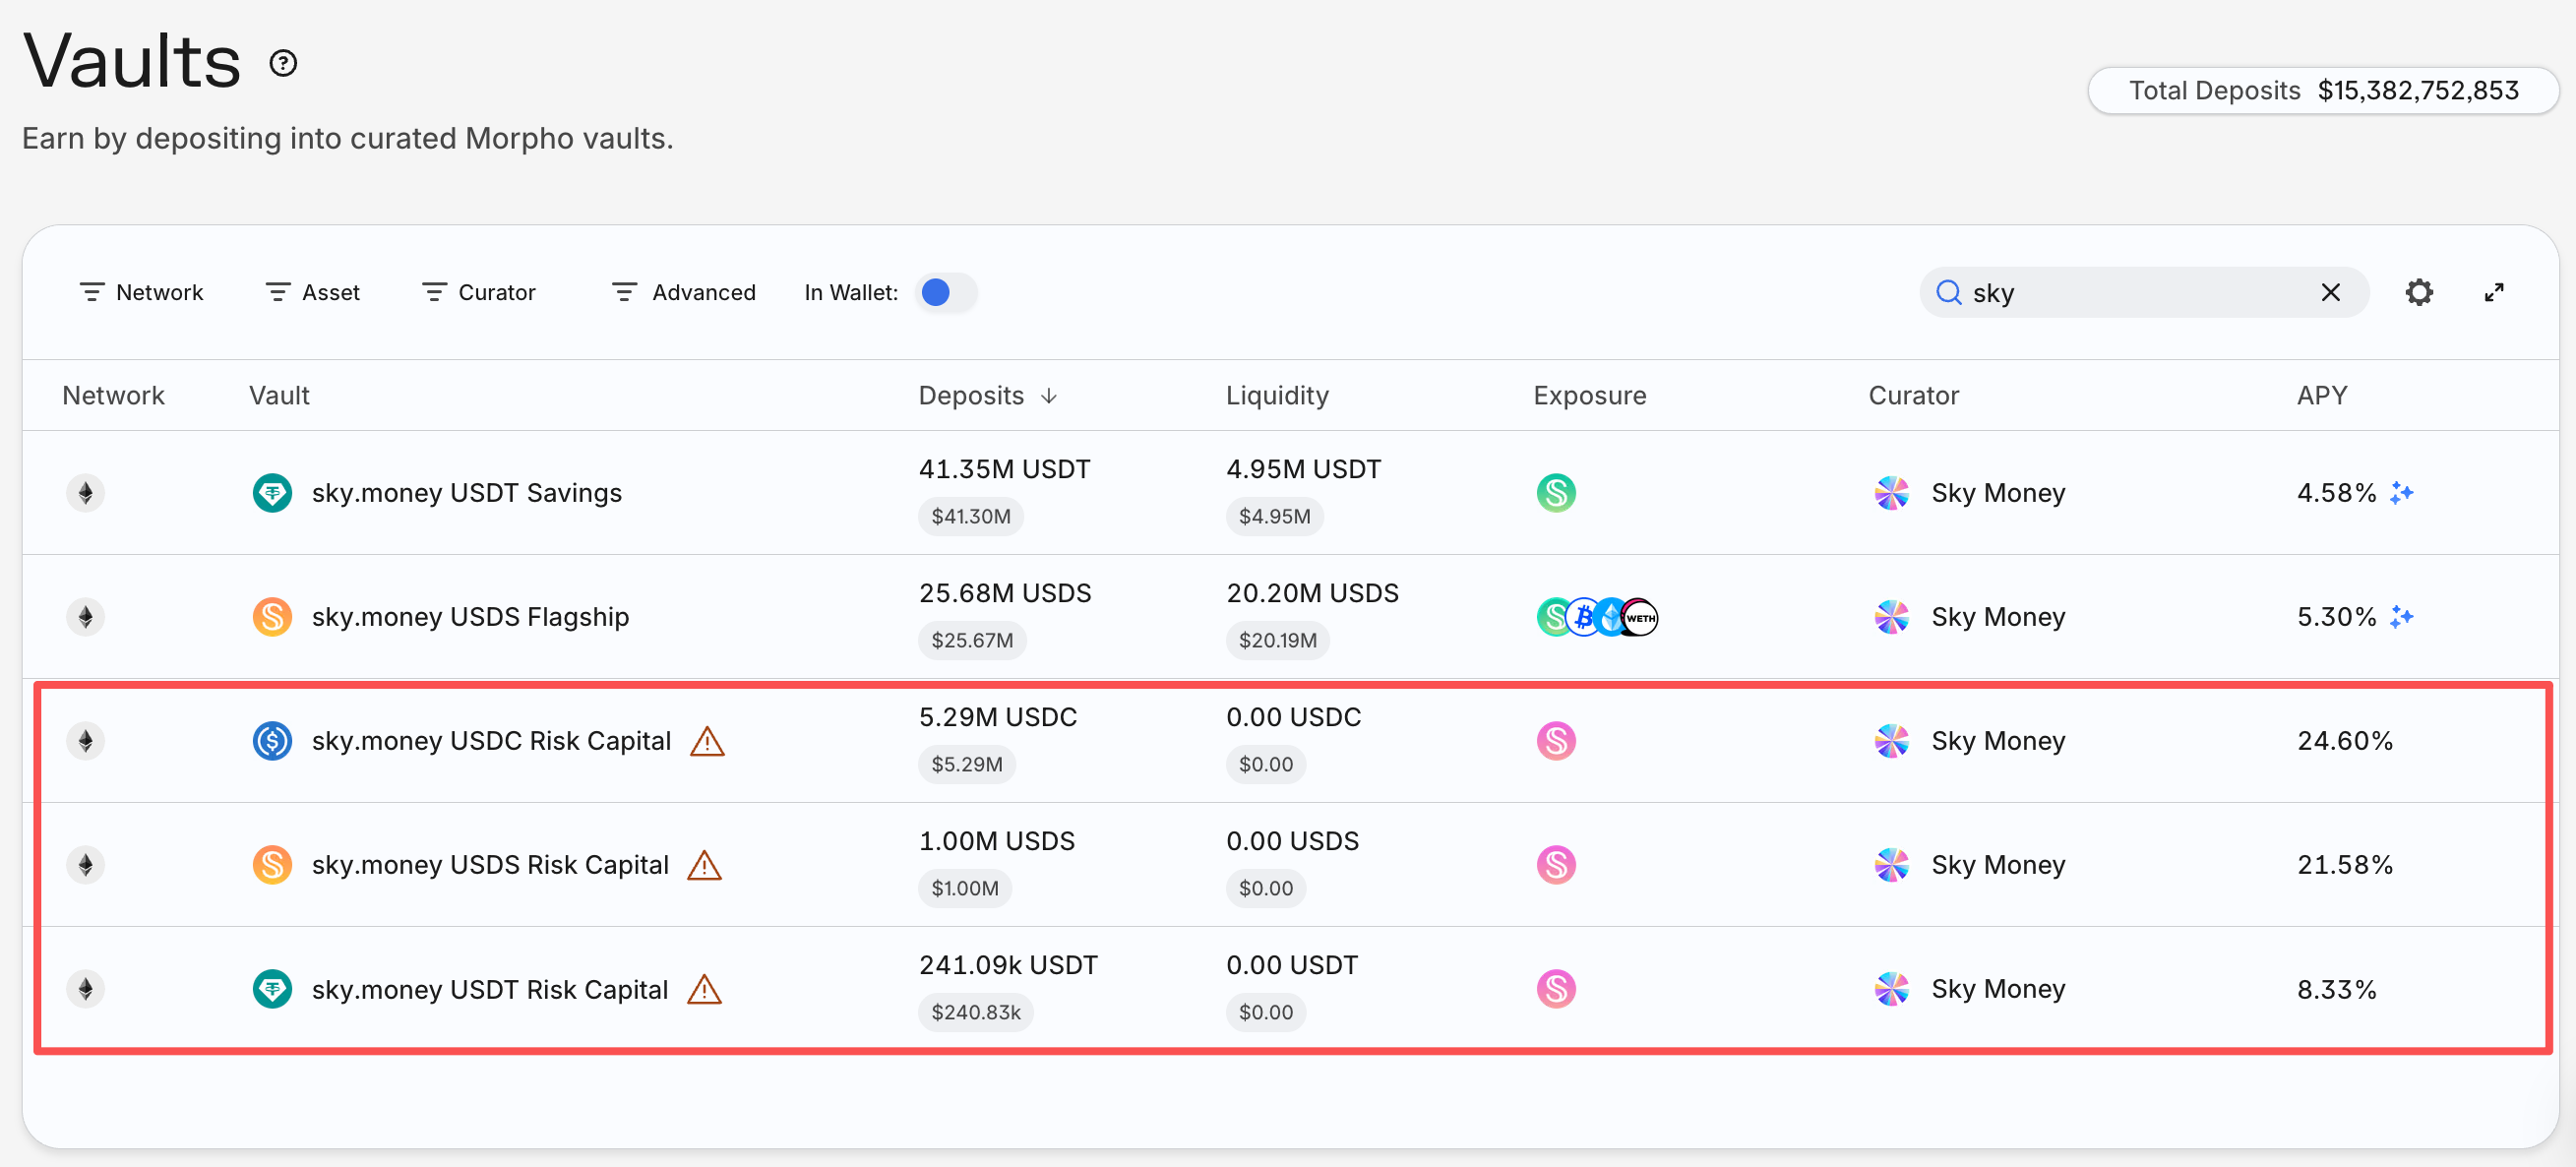
All in all, the liquidity value of these stUSDS exits is barely 9 million USD, less than 6% of the 150 million USD pool, and has already been "siphoned" by "smart people" ahead of time.
Based on the 0.04625 USD price of SKY at the time of writing, the amount of SKY collateralized by Rune is approximately 4 billion tokens. According to 1inch data, even if only 2.5% of the 4 billion tokens (100 million tokens) are traded, slippage exceeds 20%.
This means that if the SKY price continues to fall, dropping below 0.03 or even 0.025 USD, even with gradual manual liquidation, the bad debts of this pool cannot be avoided. Additionally, based on the liquidity of SKY on Ethereum, unless the Sky protocol intervenes to take over these SKY tokens, the scale of bad debts is likely to exceed 100 million USD.
A significant number of Web3 practitioners on X pointed out that this could likely be a repeat of the incident where the Curve founder collateralized CRV to borrow stablecoins.
According to DefiLlama data, USDS is currently the third-largest stablecoin after USDT and USDC, with the largest issuance among crypto native stablecoins, exceeding 5.2 billion USD and surpassing USDe's approximately 4.9 billion USD. Sky ranks 10th in total value locked (TVL) among all DeFi protocols. The scale of the Sky protocol and its position in the DeFi space remain unquestionable.
Furthermore, as of the time of writing, neither Sky nor its founder Rune has responded to the matter, and there is currently not enough on-chain evidence to point to rune.eth being necessarily controlled by Rune Christensen. However, given the behavior of such whitelisted holders cashing out through lending protocols during periods of low liquidity, converting personal risks into systemic risks, it is still worth DeFi lending protocols' consideration to think and provide targeted solutions.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


