Author: Noveleader, Castle Labs research analyst
Compiled by: Gu Yu, ChainCatcher
Funds in the cryptocurrency field are highly concentrated.
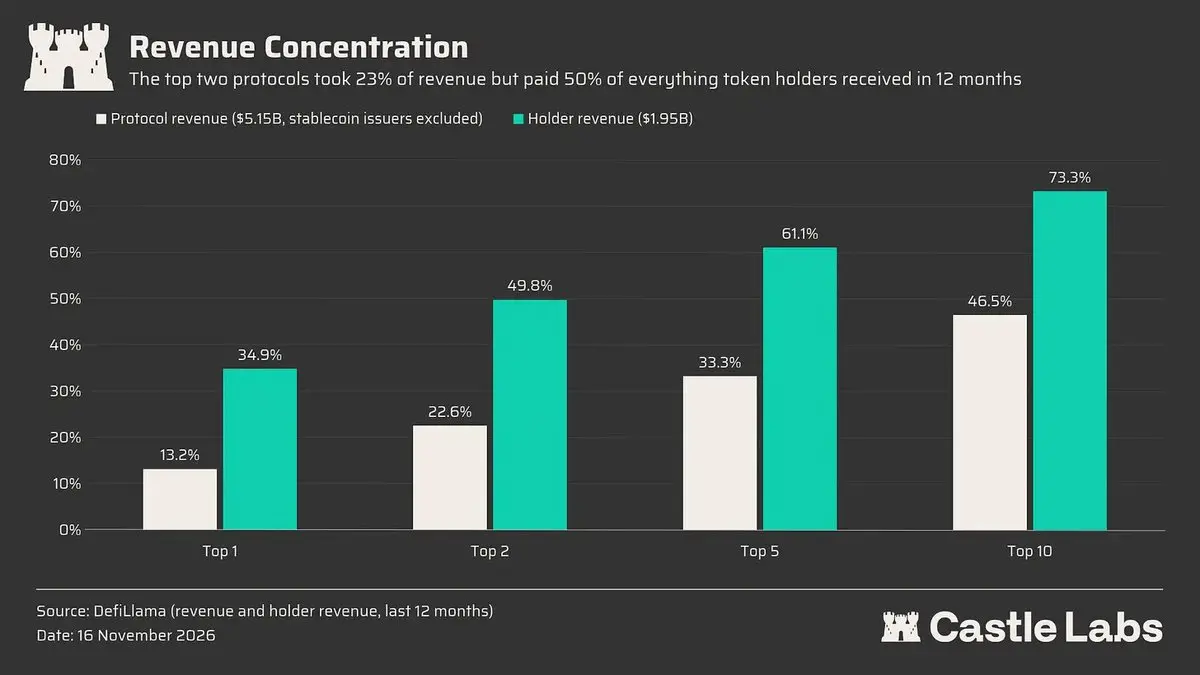
If we exclude stablecoin issuers, the top 10 protocols accounted for 47% of the total revenue from all protocols over the past 12 months.
Returns for token holders are even more concentrated, with the top 10 protocols contributing 73% to this revenue.
Protocols that generate revenue often become better investment targets due to high cash flow.
This article aims to explore whether being a leader in a category is a good indicator for token performance. If not, what are the significant differences between top projects that excel in token performance and those that perform mediocrely?
This is the third article in our series of studies. In "A New Crypto Era: From Speculation to Investment", we discussed revenue in the crypto space. In the second article, "The Broken Link Between Protocol Revenue and Tokens", we analyzed how token emissions dilute value and why emissions should be considered together with revenue.
In this article, we correlate the income flowing to token holders with the actual performance of the tokens and introduce two key factors that income alone cannot explain: how large the potential market size of the protocol can expand and the narrative surrounding the product itself.
Two-headed Monopoly of Crypto Income
Leaders in various segments of the crypto market capture the vast majority of cash flows. In the past 12 months, various categories of crypto protocols have generated $13.7 billion in revenue.
In each category, the top 2 protocols have captured at least 52% of the fees; in certain categories like stablecoin issuers, prediction markets, basis trading, and options, the top two even took over 90% of the total fees.
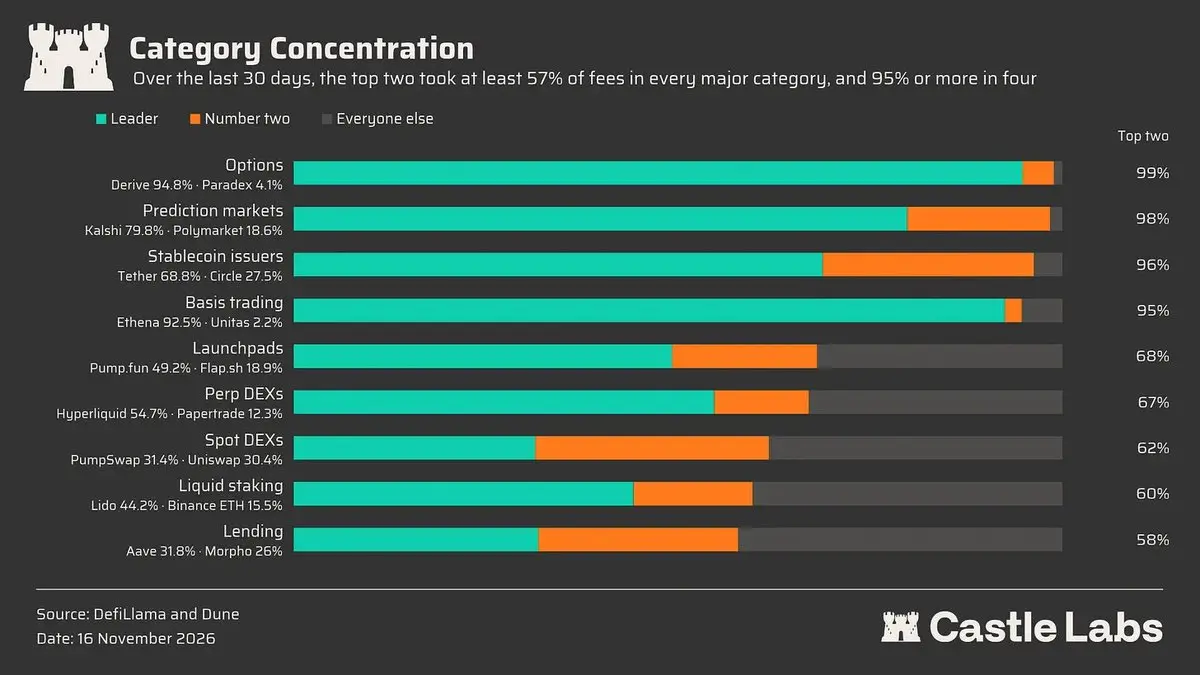
However, this concentration bias does not apply to all categories. When switching costs are low or competition is fierce, the leading position can easily be challenged.
For example, the concentration in Launchpad and spot DEX is not as high because users have very low switching costs and competition is intense.
For DEX traders, the most important factor is obtaining the best path and lowest cost trading venue, and aggregators choose routes based on liquidity. Competition is very fierce for DEX; no single platform can provide the deepest liquidity pools and optimal prices for all assets, so order flow is dispersed across multiple platforms.
On the other hand, the business for Launchpad is cyclical, dependent on whether the platform can fully capture traffic in emerging or developing ecosystems. Pons emerged prominently during the meme coin craze on Robinhood, capturing the bulk of revenue at that time, but its activity seems to be waning now.
Borrowing and perpetual contract DEX are even more dependent on incentives and liquidity drives. Therefore, capital flow relies on the combination of both: better incentives attract value, while better liquidity helps maintain value. Liquidity helps leading protocols solidify and expand their advantageous position against competitors, while some capital flows can be diverted by more attractive incentives.
Additionally, for categories with more pronounced two-headed monopolies (such as stablecoins and prediction markets), there is currently a lack of direct investment channels from the perspective of token investment. The only publicly tradable stock is Circle, with the ticker $CRCL.
Therefore, investment opportunities naturally flow back to categories with lower concentration. But even if funds flow into these leading projects, your portfolio's performance may not be stellar, as the performance of most of these tokens has lagged behind BTC.
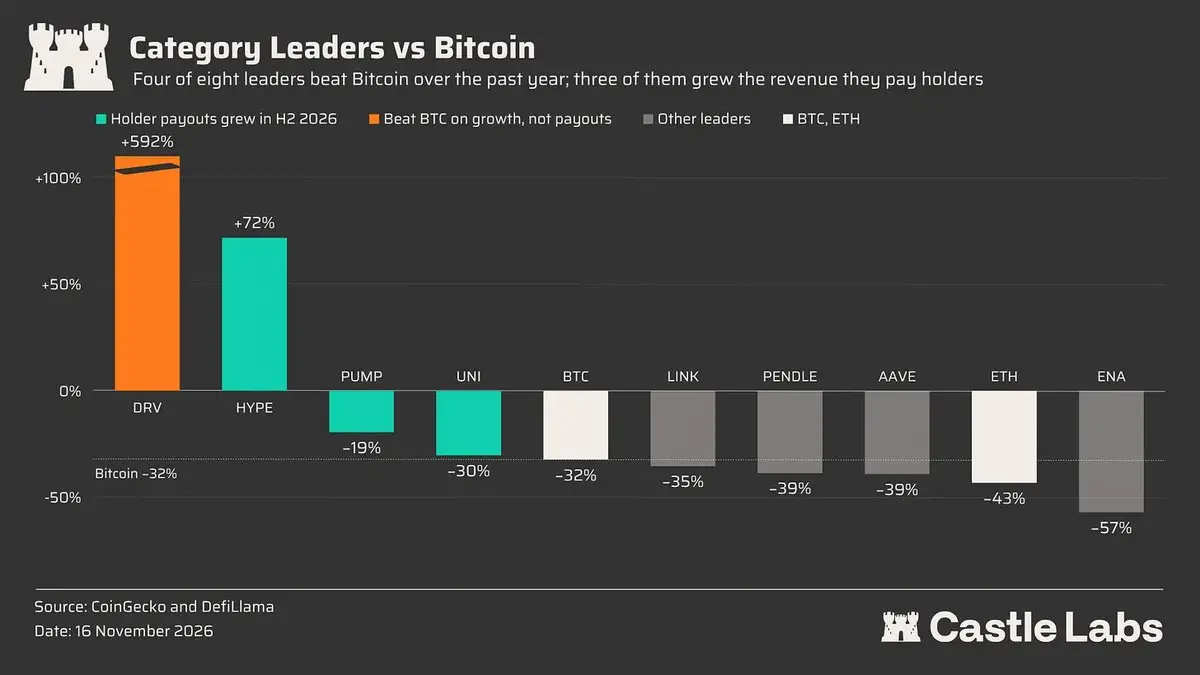
So, why do the protocols behind these tokens, which are clearly leaders in their respective segments, still see their tokens underperform?
Some of the answer is hidden in the revenue data and the share of the revenue that token holders receive.
Hyperliquid's monthly revenue jumped from $38 million in July to $69 million in October, thanks to the protocol and its tokens capturing value from growth of the project itself and Circle's reserve earnings.
Uniswap's fee mechanism and the UNIfication proposal came into effect at the beginning of the year, and the protocol has been continuously repurchasing tokens using revenue.
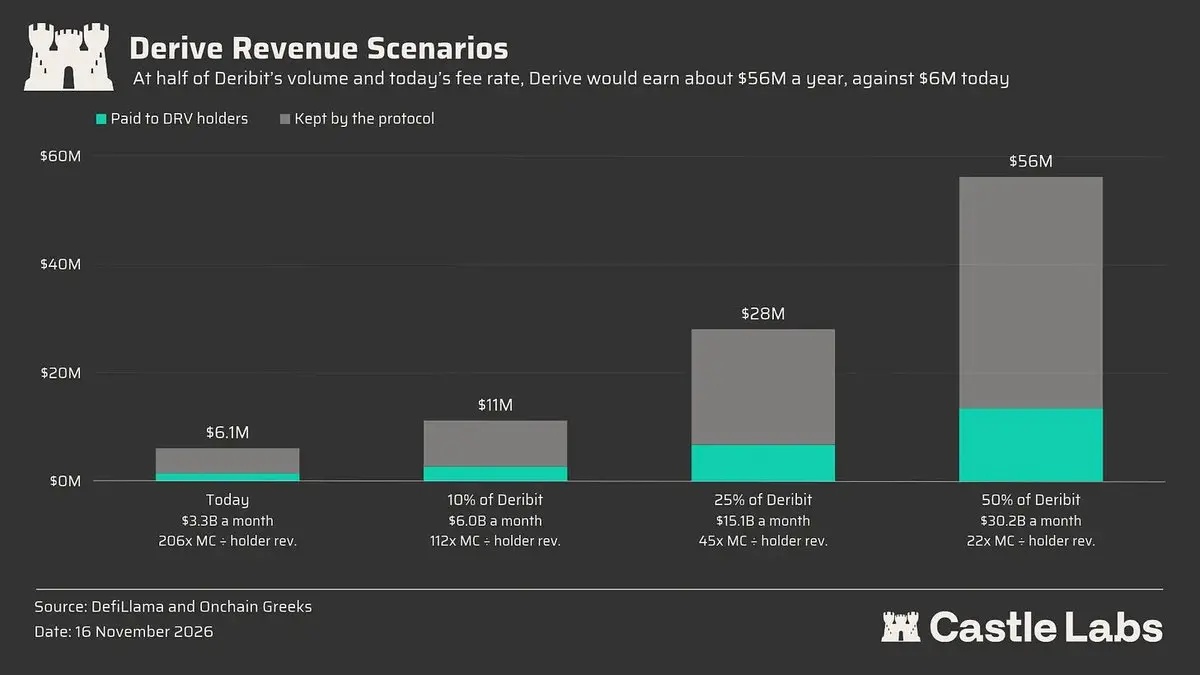
Derive's increase reached 592%, surpassing all other leading projects, yet Derive allocated about $1.3 million to its holders last year. Its price is not solely supported by holder revenue but depends on how much the on-chain options market can expand, which we will discuss in the next section.
Meanwhile, Aave paused buybacks after the KelpDAO incident, while Pendle's monthly revenue plummeted from $4 million to $500,000 over a year (from October 2025 to October 2026).
To examine whether the market has already digested these changes, we divide market capitalization by the past 12 months' holder income to reflect the premium the market pays for every dollar flowing to holders. Comparing this over a one-year span can reveal market trends and whether tokens have become more expensive or cheaper.
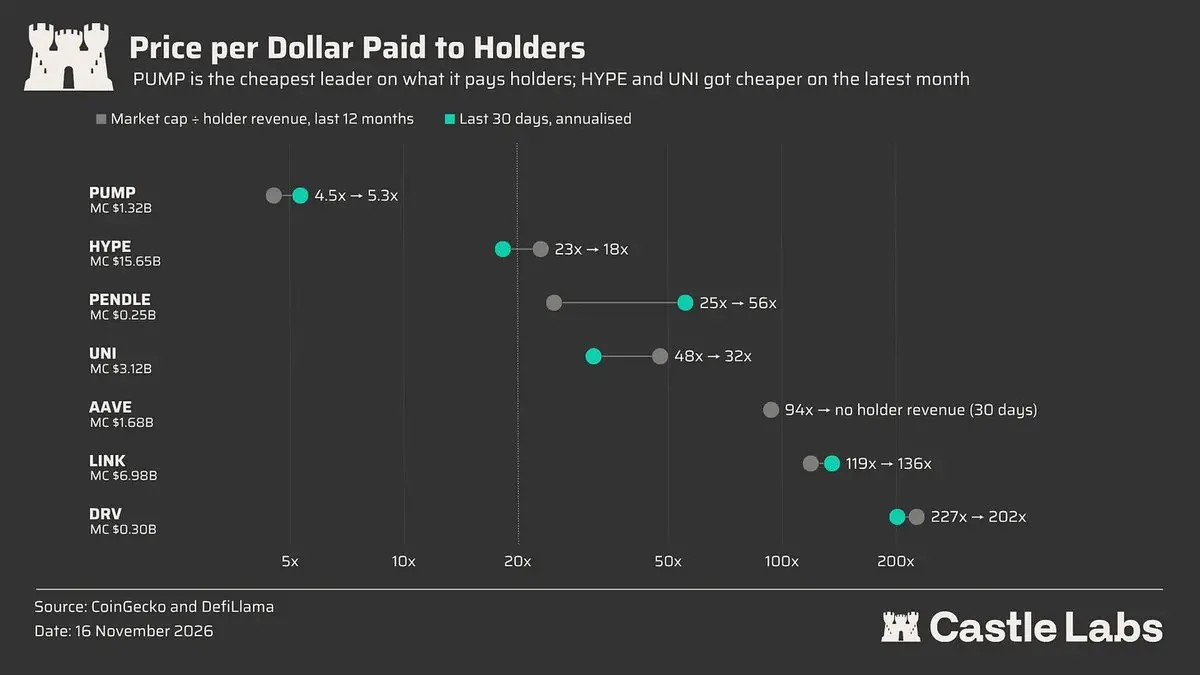
Over the past 12 months, Uniswap and Hyperliquid have become cheaper, while all other tokens have become more expensive, which also explains why these two tokens performed better than other assets.
Derive is the most expensive token in terms of valuation, clearly indicating that its price is driven more by growth expectations rather than current holder income.
Pump is the cheapest among all assets and has continuous cash flow and value accumulation flowing to its tokens. However, market sentiment surrounding this product has yet to improve, as it is a Launchpad whose revenue relies on speculative meme coin trading activities, placing it within the zero-sum game category of the entire industry.
Furthermore, the protocol has yet to distribute airdrops to its users, creating uncertainty that deters more investors.
The growth of DRV and PUMP lacks sustainability, indicating that relying solely on protocol revenue and holder income is not a sufficient judgment metric.
Other important dimensions worth noting include narrative evolution and forward-looking investments, which determine the success or failure of token fund flows. We will briefly discuss this in the next section and introduce some interesting tokens that may not have outstanding revenue but possess extremely strong narratives.
True Escape Velocity
The target market size for DeFi and tokenization is measured in trillions of dollars; therefore, for leaders in each track, the current revenue scale is just a drop in the bucket relative to their total addressable market (TAM).
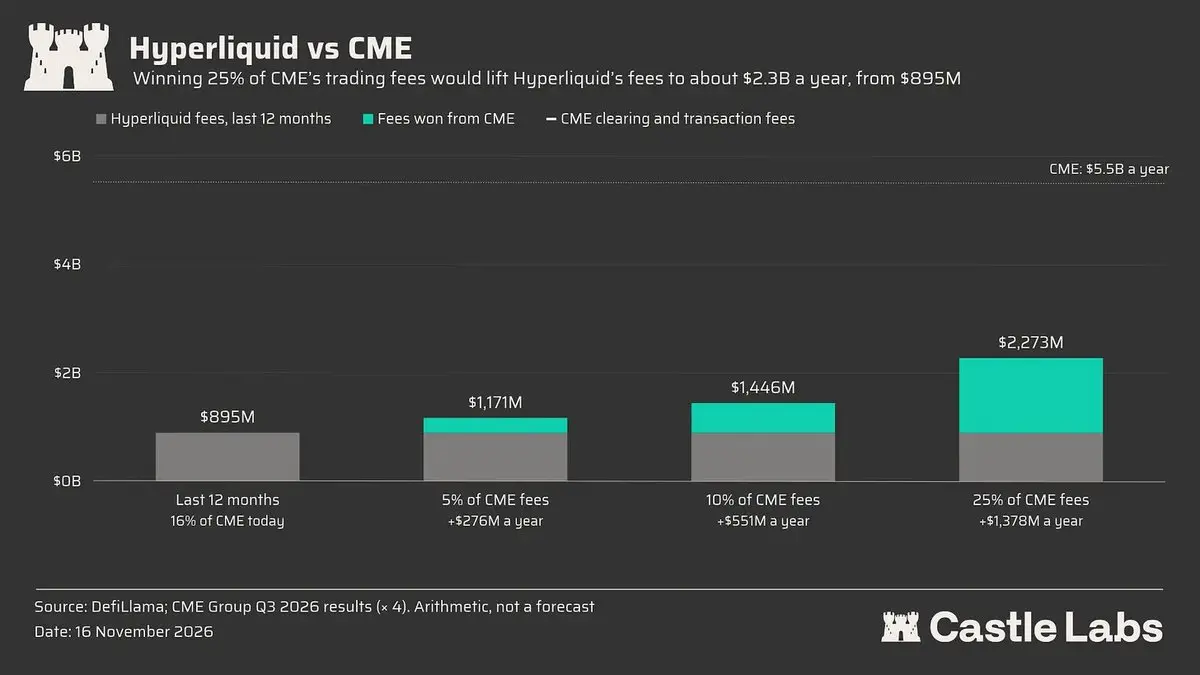
First, let us look at Hyperliquid. The protocol's annual fee income has reached $895 million, about 16% of the annualized revenue from the CME's clearing and trading fees (approximately $5.5 billion in Q3 2026 data). Hyperliquid achieved this result without any American users due to regulatory restrictions, but this situation is changing.
Recently, the parent company of the New York Stock Exchange (NYSE), Intercontinental Exchange (ICE), has partnered with TradeXYZ to bring Hyperliquid-based perpetual markets onshore, aiming to launch perpetual contracts covering cryptocurrencies, stocks, commodities, and foreign exchange in the US. Kraken's parent company, Payward, has also become the first HIP-3 deployment under the jurisdiction of the US Commodity Futures Trading Commission (CFTC) through its Bitnomial Exchange and NinjaTrader Clearing.
Although both are still awaiting regulatory approval, this clearly demonstrates the enormous market potential that Hyperliquid can leverage after opening up to the American market.
Derive in on-chain options is comparable to Hyperliquid in on-chain perpetual contracts.
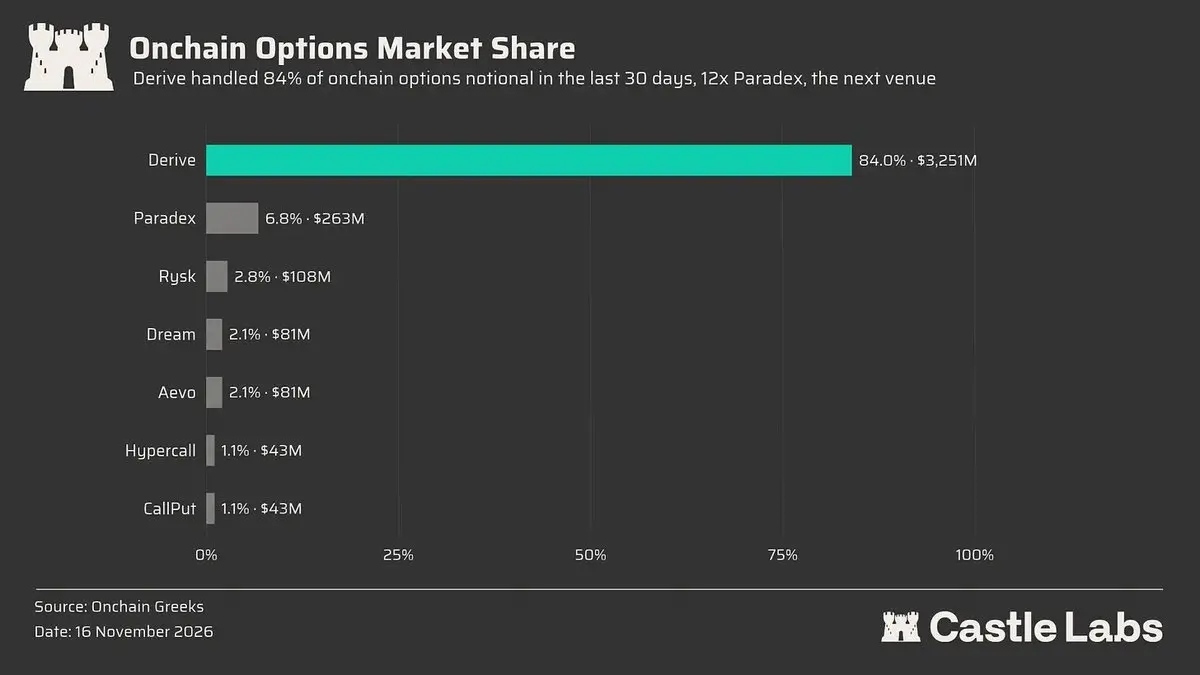
In the past 30 days, Derive has processed about 73% of on-chain options trading volume and holds 93% of open interest. Since the start of this year, the platform has settled about $14.2 billion in notional trading volume, nearly three times that of its entire 2025 volume.
To further expand the protocol's scale, they developed Derive V3, introducing multi-currency margin, vaults, and institutional-grade support. Particularly, vaults and various integrations provide a new distribution channel, similar to Hyperliquid's HIP-3 and Builder Code, and have been proven to yield remarkable results for its ecosystem.
These new distribution channels not only make the product more user-friendly for retail investors but also institutional-level support helps attract larger-scale capital flows.
Ultimately, the real territory to conquer is the traditional options market, and Derive has already taken the first step with its forthcoming RWA options.
Its currently largest off-chain options competitor, Deribit, has reached an options notional trading volume of $60.4 billion in the past 30 days, which is 13.6 times the total of all on-chain trading platforms.
With the continued expansion and steady growth of the on-chain options market, if Derive's notional trading volume can reach 10% of Deribit, its annual revenue is expected to exceed $10 million.
Uniswap leads the spot DEX segment, accounting for 25% of transaction volume in the past 30 days and 31% of net fees over the past 12 months. Its revenue has significantly increased in the second half of 2026, mainly benefiting from the combination of tokenization trends and Robinhood trading activities.
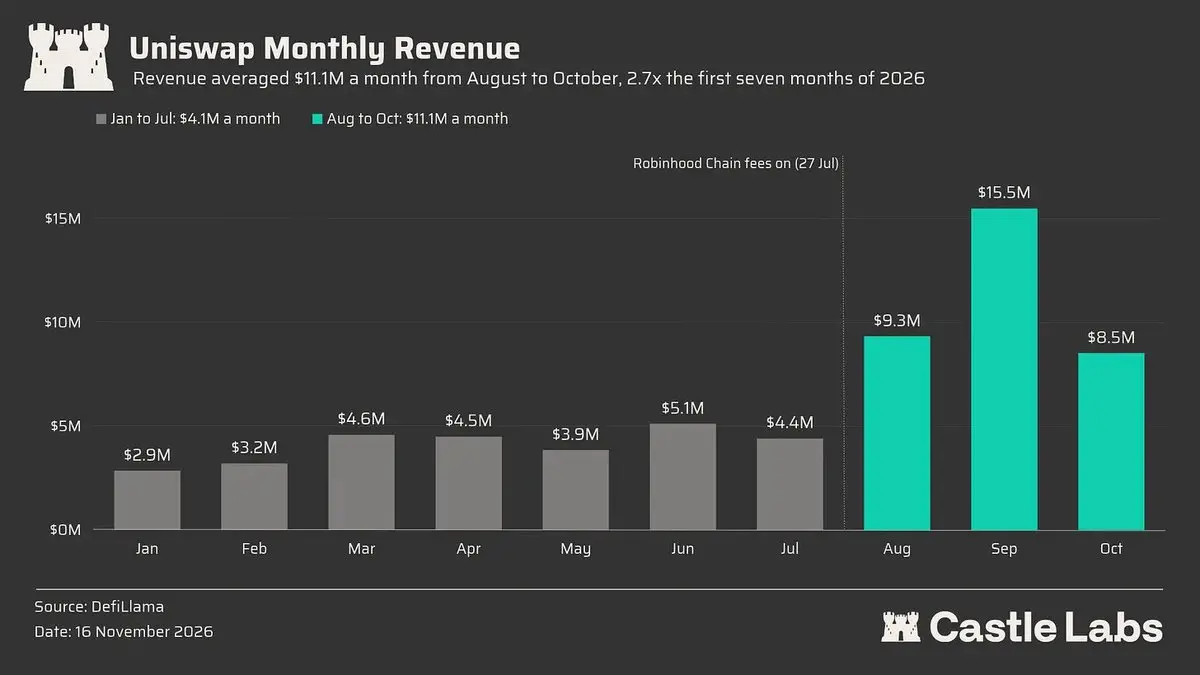
Although Robinhood's activity may be classified as a one-time pulse (even though we expect a rebound later), the bigger imaginative space lies in the rapid development of the tokenization wave: the scale of RWA assets has grown from $25 billion at the beginning of the year to approximately $40 billion now. In discussing the future potential of tokenization, McKinsey predicts that its market size will reach $2 trillion by 2030.
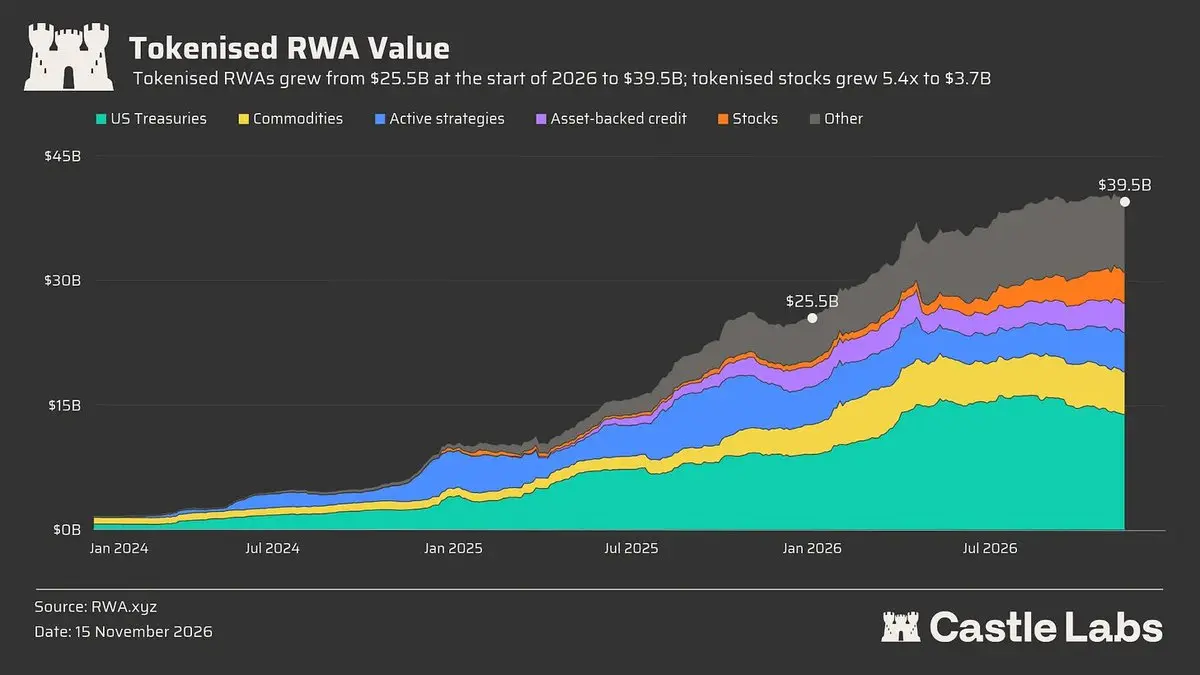
All these tokenized assets will be traded on DEX, which can provide 24/7 liquidity, creating a direct growth connection for any on-chain DEX.
The core advantage of Uniswap's architecture lies in its V4 Hooks, allowing anyone to create permissioned pools, which brings significant advantages for compliant assets that are restricted in transfers. Not only that, but V4 can also support trading in restricted regions; OKXICE is a recent representative case.
Another protocol benefiting from the tokenization wave is Pendle.
As of the end of Q3 2026, the dollar market with RWA as the underlying asset has accounted for 82% of Pendle's TVL, with its TVL growing by 43% in that quarter alone. These markets include treasury-supported dollars from Agora and Global Dollar, reinsurance from Re Protocol, and GPU mortgages issued through USDAi.
Every brand-new income-generating RWA asset needs to utilize the Pendle market for better liquidity distribution and DeFi composability; it is increasingly becoming an indispensable part of the go-to-market (GTM) strategy for tokenized asset markets and will directly benefit as these assets grow in size.
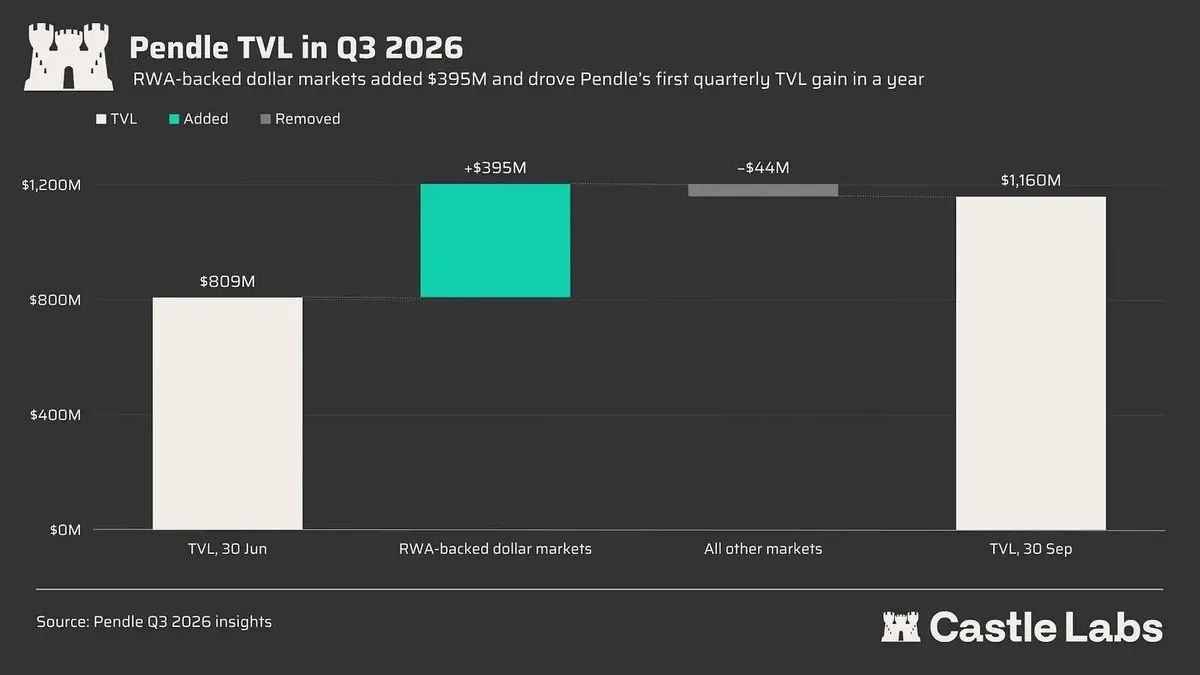
So, how high is Pendle's ceiling?
Pendle's current TVL is about $1 billion, covering both crypto assets and RWA assets. However, as the RWA market expands, Pendle's RWA TVL will also grow. Once its market share reaches 10% of the expanding RWA market, Pendle could distribute over $43 million in earnings to its holders annually.
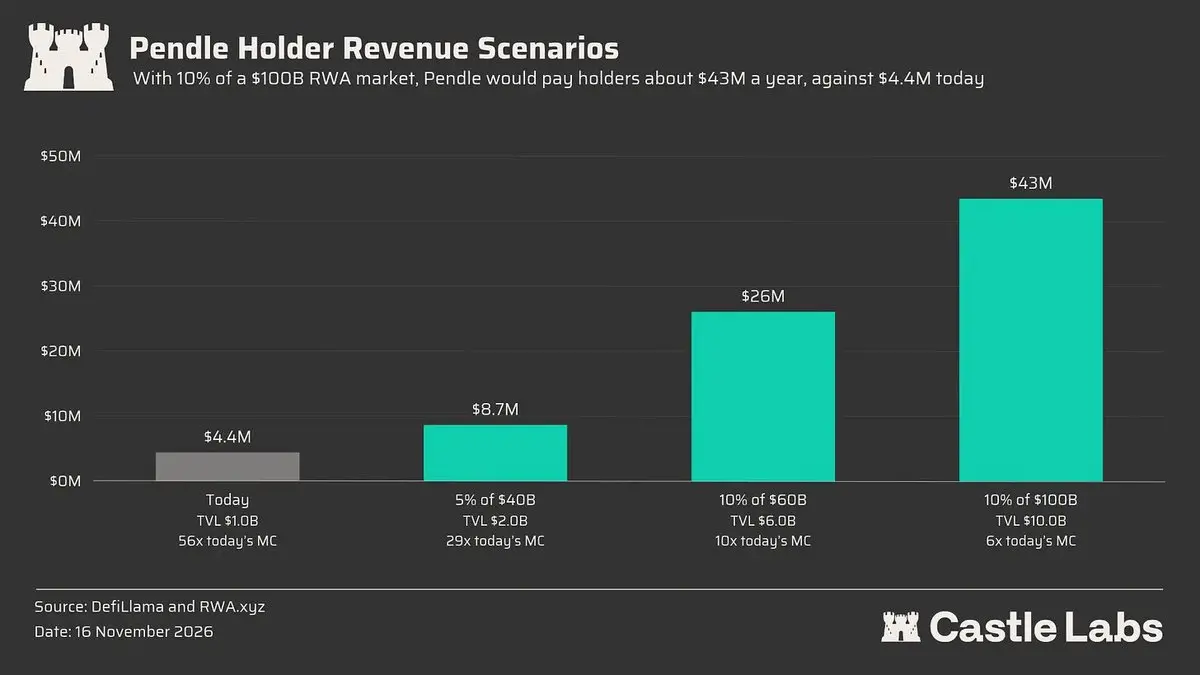
Although Aave's token price performance has been mediocre, it precisely sits at the intersection of tokenization, consumer adoption, and core DeFi.
The growth of tokenized assets is closely related to Aave and Pendle because Pendle's PT assets are stored on lending platforms as collateral for leveraged loops. The tokenized stock scale on the Base chain has been continuously growing, with net deposits surpassing $18 million driven by incentive measures and arbitrage trades from collaborations like SuperForm and Dialectic Group Vaults.
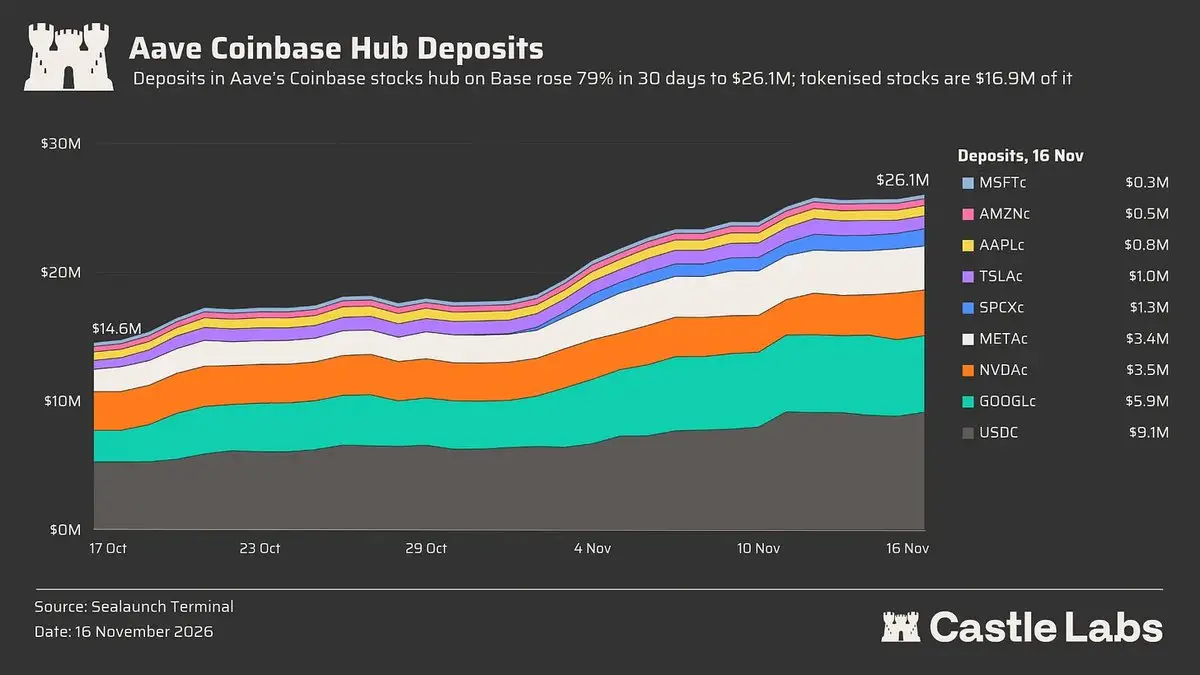
The Aave app allows users to earn DeFi-native yields higher than US Treasury rates, with up to $1 million in fund balance protection (four times the $250,000 FDIC insurance standard for US banking). The next-generation digital bank EtherFi also deployed its core hub on Aave V4, with deposits around $350 million, and supports users to lend directly in-app, injecting new incremental capital flow into Aave, shaping it as an underlying infrastructure provider for consumer-focused users.
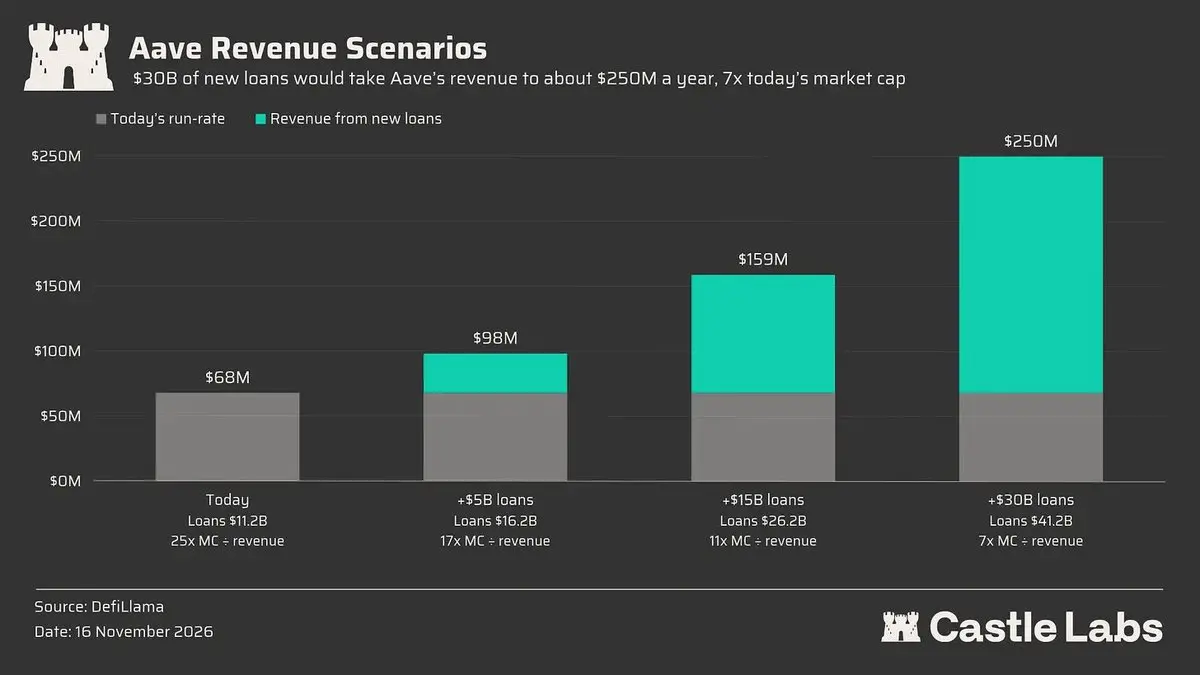
Diversified distribution channels and growth engines introduce more lending demand into the system, thereby driving revenue increases. The platform currently holds approximately $12 billion in active loans, generating $61 million in revenue this year. As the lending scale further expands, we expect its revenue will show linear growth.
Although Aave has all the necessary growth levers, it has stopped distributing value to token holders since April this year. Once this function is reinstated, we will witness this growth truly translate into tangible returns.
The aforementioned projects are all core DeFi protocols with significant attention, but we also hope to focus on benchmark products such as Pearl and Venice AI, which are rising as “AI currencies,” and Zcash, which is becoming known as a “privacy currency.”
Let's start with Venice, as this project has already generated actual revenue, not merely relying on future expectations.
Venice provides its users with a privacy-focused, censorship-resistant model access channel, serving as a decentralized alternative to Claude and ChatGPT.
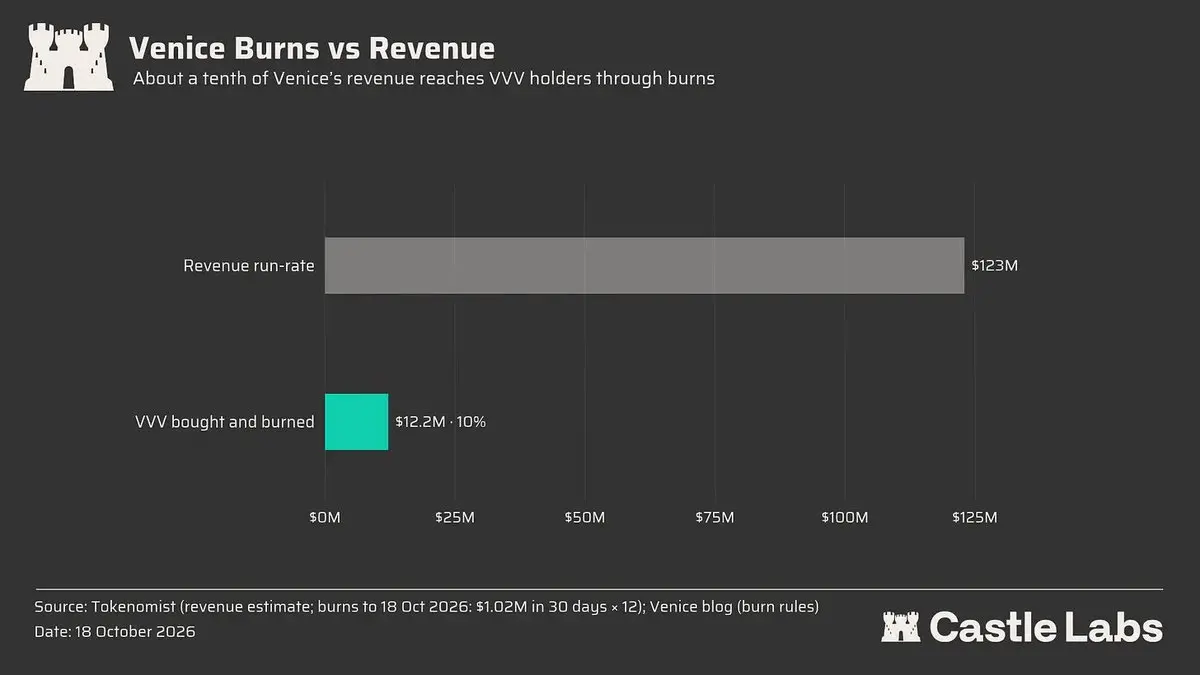
Its annual revenue reaches $123 million, corresponding to a P/S ratio of around 8 times for $VVV (based on circulating market cap) or about 12 times (based on fully diluted valuation FDV). However, $VVV has not captured all the value, as Venice's equity also participates in profit-sharing, leading to a disconnect between token holders and equity holders, raising questions about who can capture the maximum value once the project succeeds.
To alleviate concerns surrounding the token and ensure aligned interests, Venice has implemented a self-discretionary and automatic buyback mechanism for $VVV (returning part of sales to the token). In the past 30 days, these burn amounts have accumulated to $1.02 million, equivalent to an annualized figure of about $12.19 million, making the buyback account for 10% of the revenue.
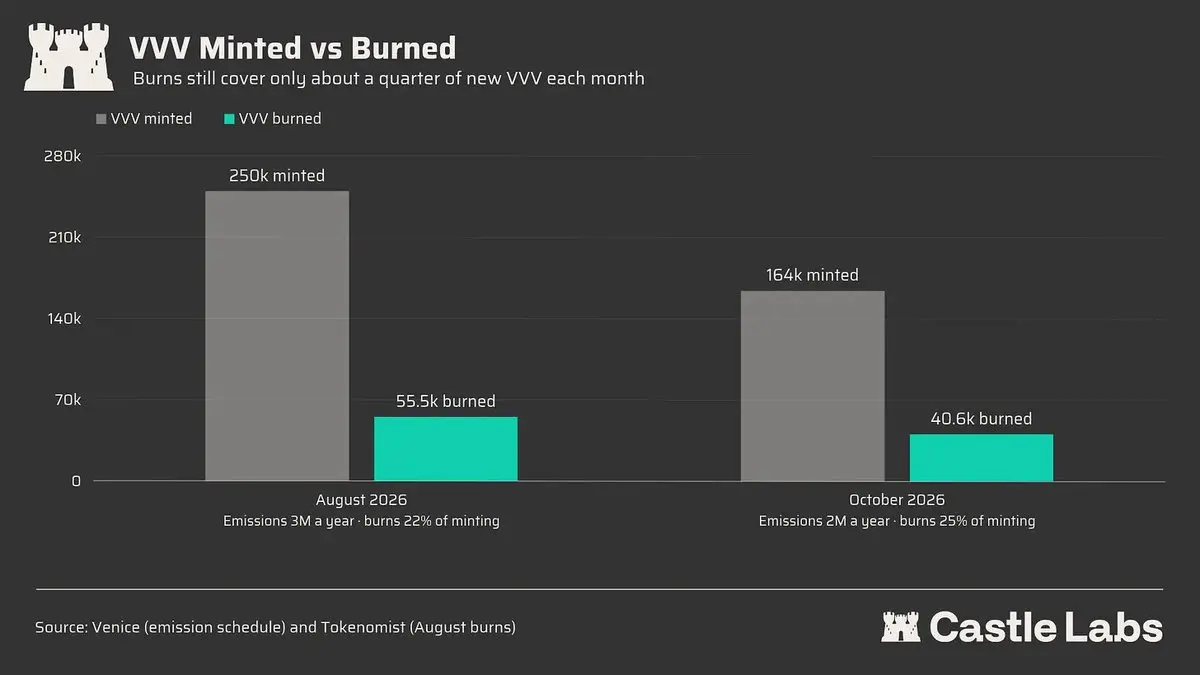
This month, the team also reduced the annual token emission from 2.5 million to 2 million, mitigating the new selling pressure on the token. At the current pace, repurchasing and burning would only remove 500,000 VVV tokens from supply, accounting for only 25% of new emission supply, keeping the token in a state of inflation. As the network expands, we expect its revenue to grow further while token emissions decrease, driving the token towards a deflationary path.
The second token is $PRL, which has attracted wide attention due to its clever mechanism design. On the Pearl network, miners run matrix multiplication calculations using their GPUs—this is the core computational process behind all chatbots, known as "Proof of Useful Work (PoUW)."
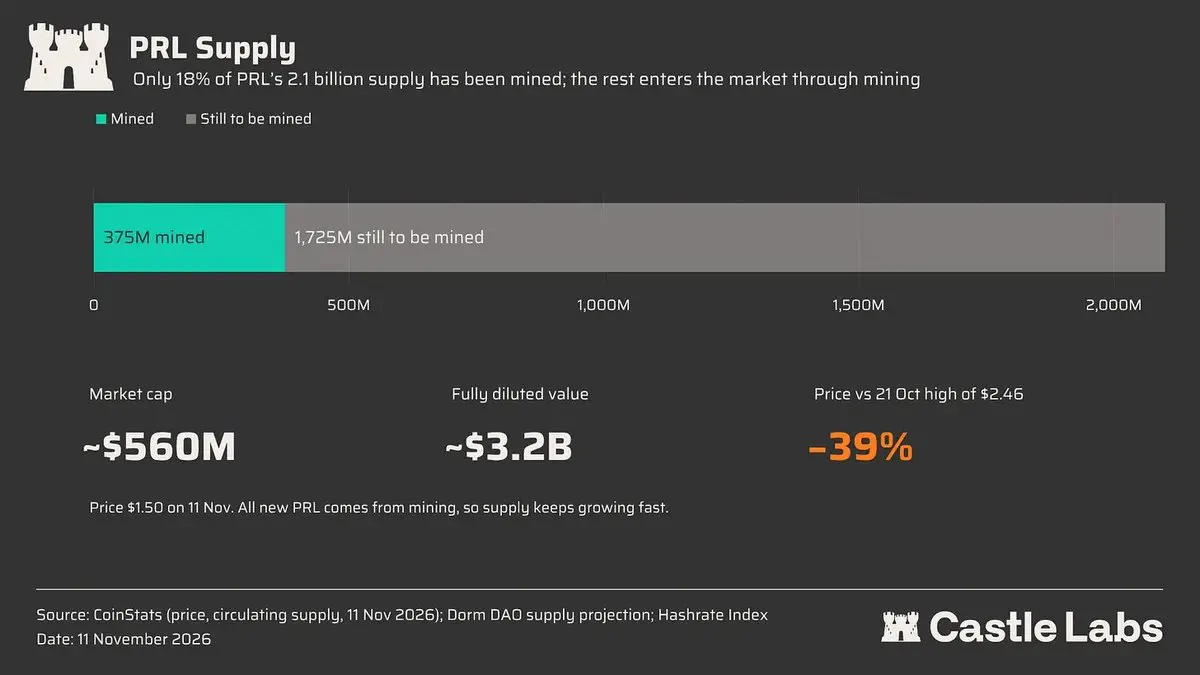
The network's mainnet went live at the end of April, and after peaking in October, $PEARL currently trades at a market cap of around $500 million. We have previously detailed Pearl, its operational mechanism, and the target market it aims to penetrate.
It is also important to note that, in the current network, much of the mining power has not been converted into paid revenue from inference demand; currently, only one partner Together AI is subsidy funding for its own services using that computing power.
While this is concerning, the application's prospects are far broader than many expect. If multiple clients begin to access inference services and pay for them in the future, this would further boost miner income through the token burn mechanism, as users could settle fees using $PRL.
Moreover, when discussing $PRL, one cannot overlook its fair launch mechanism: anyone can mine tokens through participating in network mining or purchase them directly on exchanges, with only 18% of the total token supply being mined.
Zcash is another representative forward-looking investment case, gradually transforming into a store of value (SOV) asset. Zcash itself generates minimal income, yet it is one of the best-performing high-market-cap tokens this year.
Wall Street gained compliant investment access through Grayscale's Zcash ETF (ZCSH), which began trading on August 25 and has attracted over $1 billion in deposits, ranking in the top 1% of best-performing ETFs issued in the past decade.
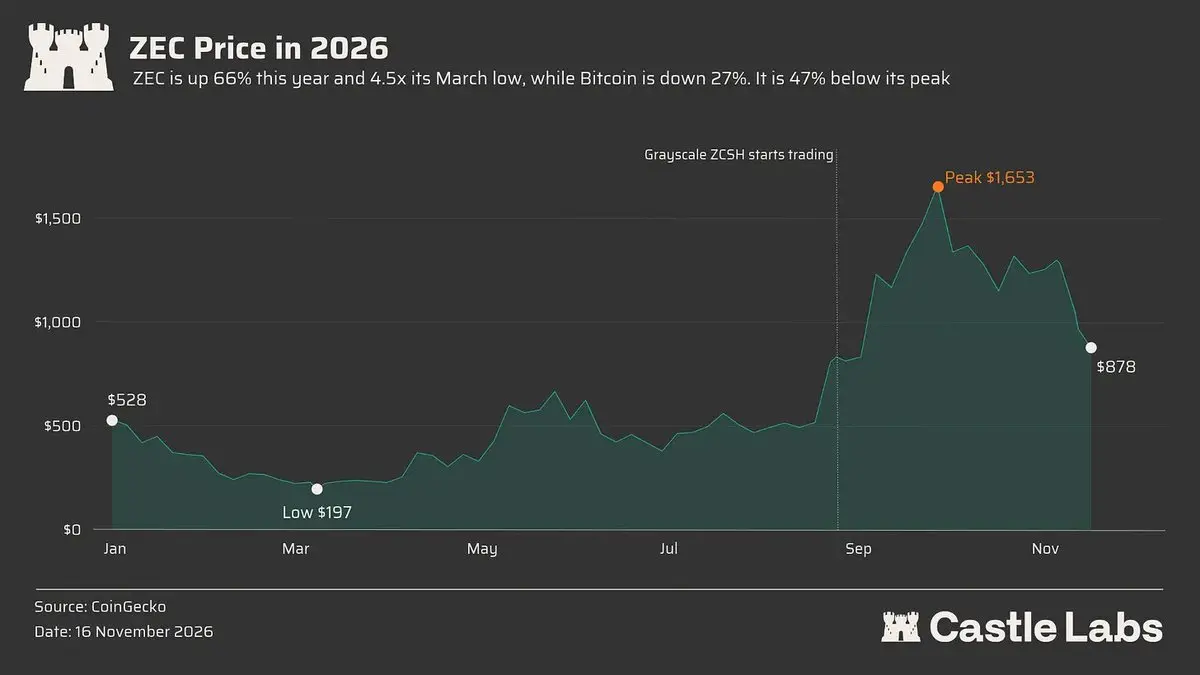
Zcash is essentially a privacy version of Bitcoin: a supply cap of 21 million, halving every four years, and the optional zero-knowledge masking feature bestowing it with privacy attributes. Privacy is not just a feature that sounds good on the surface; it has been increasingly used practically, with the shielding of ZEC rising from 8% to 29.2% in three years.
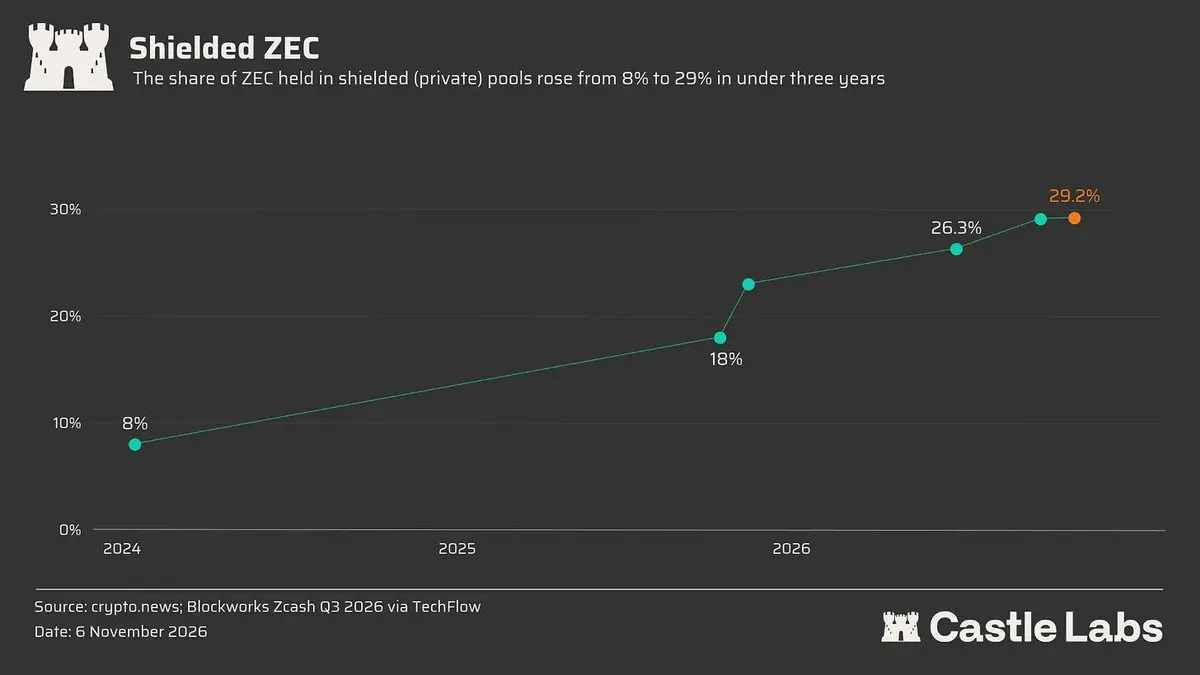
The privacy feature is part of what makes Zcash interesting; it recently surged following the Democrats' win in the midterm elections, as if they come to power in the US, we can expect a tightening of censorship and increased demand for financial privacy, which Zcash can provide and should be viewed accordingly.
In this section, we discussed two types of tokens: one type generates continuous income that can return value to token holders and is expected to penetrate much larger markets through tokenization; the other is more forward-looking with a stronger narrative.
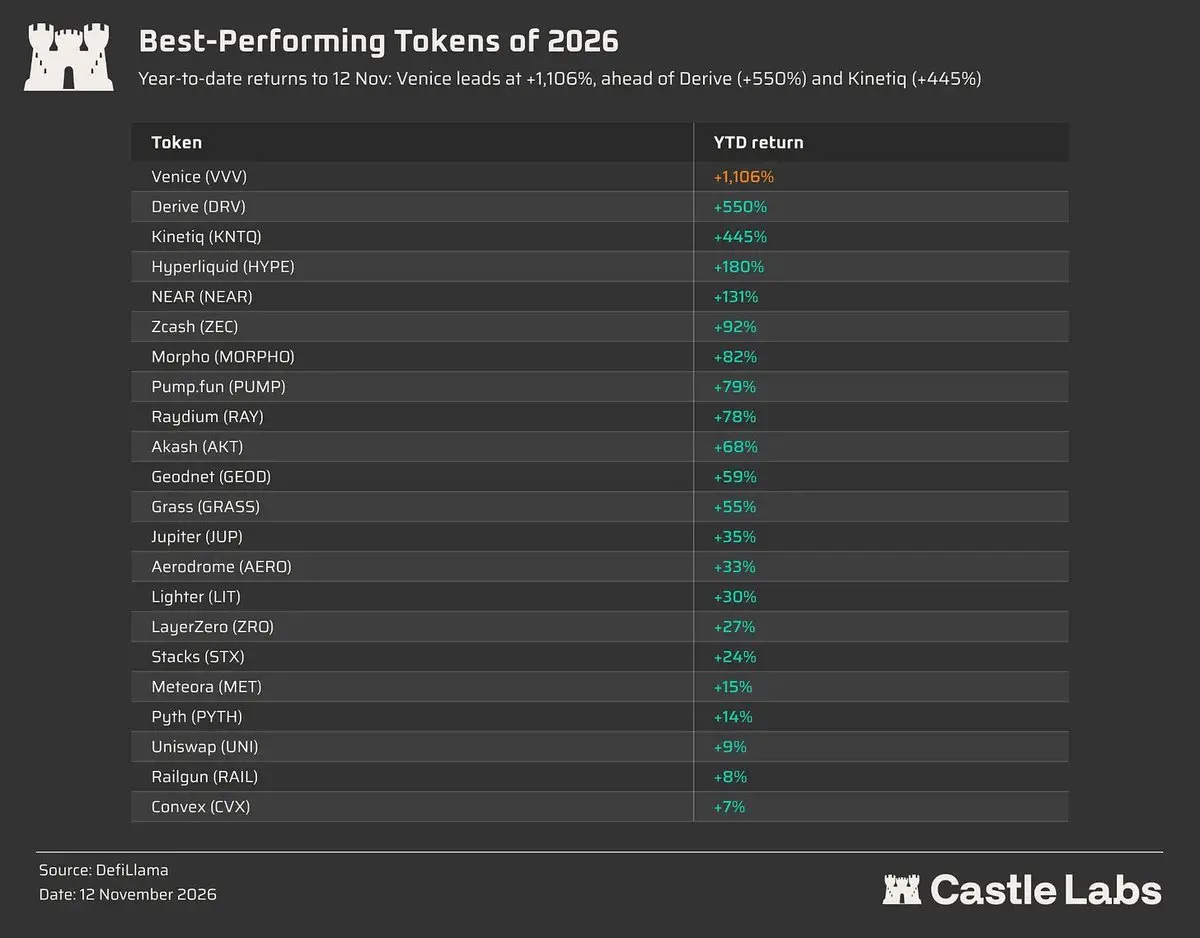
A good investment can encompass both aspects, focusing on fundamentals while also being mindful of future trajectories. If you look at those tokens delivering strong YTD returns, the answer becomes clearer.
Conclusion
Reflecting on the question we posed at the beginning of the article: Is becoming the leading token in a category a significant predictive indicator of performance? The answer is not as straightforward as "yes," as most category leaders perform poorly, which necessitates using a different perspective to assess tokens:
The product's current fundamentals and how closely related they are to the token. If a token can generate sustained cash flow, it is a good token, but it also needs to be understood in conjunction with emissions to comprehend the net flow around the token.
The market the product attempts to penetrate and how large that market can potentially become. Tokenization is a relatively large market, with numerous on-chain products attempting to penetrate; if a product is directly related
the product's narrative it surrounds and has already mastered. Products with strong narratives gain demand based on potential future growth. For Zcash and Pearl, they represent Private Money and AI Money, respectively, as the former is essentially a privacy version of Bitcoin while the latter attempts to satisfy AI computational demands through its token and blockchain design.
The first check is crucial for assessing the token's fundamentals; the second helps delineate market size and growth, while the third highlights what the market is most concerned about.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


