Author: Zen, PANews
The scale of the U.S. residential real estate market exceeds $50 trillion, but unlike the stock market, investors still lack a mature financial tool that directly provides exposure to the prices of the entire U.S. residential market.
Institutions like FHFA and Case-Shiller have already established a mature housing price statistical system but have never formed an index investment market with broad liquidity similar to the S&P 500 ETF.
A startup called Index Industries is attempting to change this situation. Through a daily updated U.S. Housing Price Index, tokenization technology, and related financial services, the company hopes to turn price fluctuations across tens of millions of residential properties into investable and tradable financial assets.
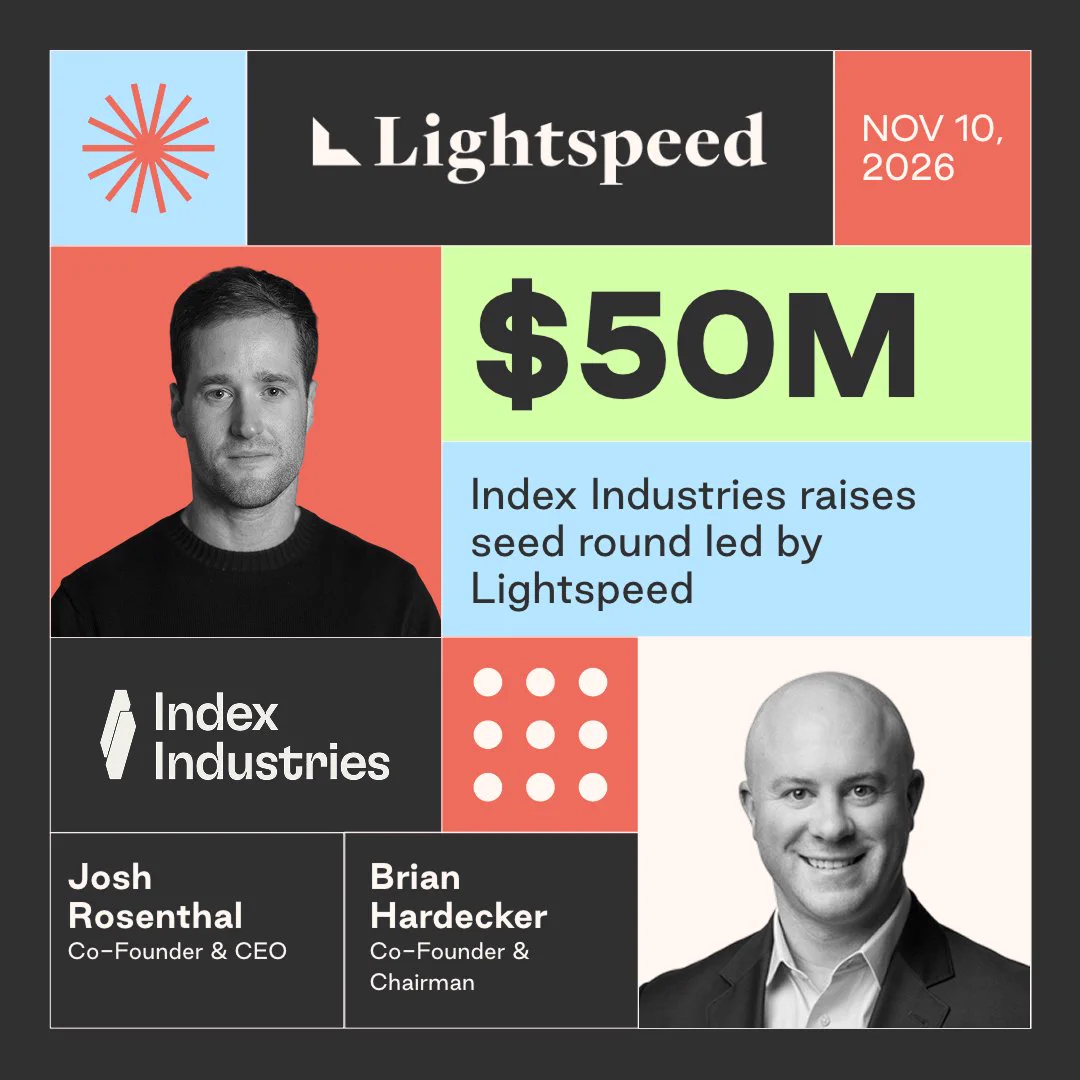
On November 10, 2026, Index Industries announced the completion of a $50 million seed round financing, led by Lightspeed Venture Partners, with participation from Polychain Capital, Galaxy Ventures, Wintermute Ventures, and others.
This previously stealth startup was co-founded by Josh Rosenthal, former president and managing partner of Polychain Capital, and Brian Hardecker, founder and CEO of the residential real estate platform Longmark.
$55 Trillion Housing Market, 0 Investable Index Products
Residential real estate has always been the most important component of household wealth.
According to the Federal Reserve's financial accounts data for the second quarter of 2026, the value of U.S. residents' owner-occupied housing assets reached $49.8 trillion, with net equity in residential housing approximately $35.8 trillion. Index Industries estimates that the U.S. residential real estate market size is $55 trillion. While there are differences in statistical scopes and definitions, they all reflect the enormous size of this asset class.
However, there is a significant gap between market size and investment convenience.
For ordinary investors, participation in the U.S. real estate market mainly occurs through three methods: directly purchasing residential properties, investing in real estate investment trusts (REITs), and buying stocks of real estate developers. However, these methods also have objective issues such as high investments, management costs, and reliance on institutional operational capabilities, and they cannot represent the price trends of the entire residential market.
This raises the question: Is it possible to obtain overall price exposure to the U.S. residential market, without needing to own any property, similar to purchasing an S&P 500 index fund?
In fact, the U.S. already has a fairly mature housing price statistical system. The two most important indicators are the FHFA House Price Index published by the Federal Housing Finance Agency (FHFA) and the S&P CoreLogic Case-Shiller Home Price Index under S&P Global. These indices have become important references for U.S. real estate market research, mortgage risk management, and asset valuation.
However, they essentially remain statistical indicators and are not financial products that ordinary investors can directly purchase. This contrasts sharply with the stock market: the S&P 500 index enables investors to convert it into tradable assets through financial tools like ETFs, futures, and options. The real estate market lacks similar mature market infrastructure.
Index Industries is attempting to address this long-standing gap in financial tools.
From Monthly Updates to Daily Updates, How the USHP Index Measures U.S. Home Prices
Index Industries' first core product is the USHP Index (U.S. Home Price Index), which is a benchmark index for U.S. residential home prices.
Traditional housing price indices mainly rely on transactions that have already occurred. Due to the low frequency of real estate transactions and lengthy data collection and processing cycles, indicators like FHFA and Case-Shiller are usually published monthly, making it difficult for investors to obtain continuous information on price changes.
The USHP Index aims to change this situation. Its index is based on traditional housing price indicators like the FHFA Purchase-Only HPI and Freddie Mac House Price Index. Through statistical models, it integrates relevant data along with signals like trends, momentum, and mortgage affordability to form a nationwide home price curve that is updated daily.
The entire calculation process can be divided into four stages:
- Establishing a price benchmark: The USHP Index is based on traditional housing price indices to establish a relatively reliable pricing foundation for the new index.
- Statistical smoothing: Traditional housing price indices have publication lags; USHP uses statistical models to smooth different data in an attempt to estimate the current market position based on published price changes.
- Integrating market signals: In addition to historical housing price changes, USHP also incorporates factors such as trends, price momentum, and mortgage affordability into its model to create a continuous national home price estimation curve.
- Publishing on-chain data: After the index calculation is completed, the USHP Index and related pricing data are published on Ethereum via Chainlink oracles, providing pricing references for the subsequent issuance, minting, and redemption of USHP products.
Since March of this year, the USHP Index has entered real-time operation, while previous historical data belongs to backtesting and hypothetical data. According to the official introduction, its index methodology is independently reviewed by mortgage and housing data analysis company Andrew Davidson & Co.
Based on the index, Index Industries has further designed two financial products: USHP and USHPi.
USHP is a tokenized index asset designed based on the USHP Index, issued by USHP Limited, and supported by housing-related reserve assets. Holders can obtain exposure to the U.S. housing price index through USHP. It should be noted that USHP does not represent ownership of residential property nor does it involve splitting properties into numerous shares for sale. Its core is to provide a financial exposure linked to the U.S. housing price index.
USHPi is the yield-bearing version of USHP. Holders can convert USHP into USHPi, and the USHP Foundation can distribute a portion of the income generated from the reserve assets to USHPi holders. This design attempts to address another issue with traditional housing price index products: while rising housing prices can bring capital gains, the price index itself does not automatically generate cash flow like bond interest or rental properties.
Financialization of Real Estate Indices, Attempts that Failed 20 Years Ago
In fact, establishing a financial product around housing price indices is not a new idea.
As early as 2006, the Chicago Mercantile Exchange (CME) attempted something similar. In May of that year, CME launched real estate futures and options based on the S&P/Case-Shiller Home Price Index, covering ten major U.S. cities as well as a composite index. Its design thinking shares similarities with today’s USHP, as investors do not need to purchase homes to bet on price fluctuations in the real estate market through standardized contracts.
However, this theoretically sound venture capital product did not develop as expected in reality.
Throughout 2007, CME's real estate futures only traded 2,935 contracts, while the total futures market of CME saw contract trading volumes reach 2.2 billion. In the first nine months of 2008, the average trading volume of real estate futures declined by 59% year-on-year, with the average number of open contracts dropping by 70%. At present, although CME's S&P/Case-Shiller real estate index futures have not disappeared, they have never formed sufficient trading depth, becoming an extremely quiet niche market.
The question arises: why is such a large-scale real estate market unable to support a mature index derivatives market?
The first answer is liquidity. Stocks, bonds, and commodities have relatively mature secondary markets where market makers can hedge their risks through buying and selling related assets. However, residential real estate transactions have longer cycles, higher transaction costs, and more dispersed participants.
Secondly, the real estate market is highly localized, which creates basis risk between the index and specific assets. The houses held by investors may experience price changes that differ from the index due to various factors such as location, age, and renovations. For institutions looking to hedge risks, differences between the index and actual held assets reduce the derivatives' utility.
Third, the market lacks enough natural trading counterparties. For real estate index derivatives to achieve liquidity, there needs to be a simultaneous existence of investors willing to buy and sell. Real estate developers, mortgage institutions, and property owners may have hedging needs, but their risk exposures, investment horizons, and trading directions do not always align, making it difficult for market makers to maintain stable quotes and trading depth.
This history provides important insights for Index Industries.
Although it is not entirely the same as CME's real estate futures from 20 years ago—CME offered cash-settled derivatives based on the housing price index, while USHP attempts to establish a holdable, redeemable index product through tokenization and reserve assets—the underlying issues faced by both are similar: how to create sustained financial trading demand in a market with low trading frequency and highly dispersed assets.
How Does Index Industries Change the Rules of the Game?
The failure of CME indicates that the obstacles faced by real estate index products extend beyond the lack of trading tools; they also stem from a lack of continuous counterparties and effective liquidity supply. What Index Industries is attempting to change is the financial structure behind the product.
First, USHP does not employ the traditional futures contract model but instead transforms the housing price index into a tokenized asset that can be held, minted, and redeemed. This shifts real estate index investment from merely betting on prices to a more asset allocation approach similar to index funds.
Secondly, USHP has set up a dedicated liquidity reserve to support investor redemptions. According to a reserve snapshot disclosed by USHP's official website on August 31, 2026, approximately 86% of its reserves are housing-related assets, with cash and cash equivalents accounting for 8%, and stablecoins and tokenized government bonds making up 6%.
USHP takes the lower of the index price or the net value of reserves corresponding to each token as the pricing basis for minting and redemption. In other words, even if the U.S. housing price index rises, if the net value of the underlying reserve assets does not increase correspondingly, investors can only redeem based on the lower reserve net value. This mechanism aims to prevent tokens from being redeemed at prices above the underlying asset value but also means that USHP holders cannot always exit at the valuation corresponding to the housing price index.
This provides investors with an exit channel different from secondary market trading and establishes a connection between the product price and underlying reserve conditions. However, reserve assets do not equate to cash. This pricing mechanism primarily addresses valuation constraints and cannot independently resolve liquidity issues.
To this end, Index Industries has introduced institutional capital and professional market makers to establish initial trading depth for the product. Prior to the official launch, USHP received commitments for up to $100 million in institutional funding, with Galaxy and its associated entities participating not only in product financing but also expected to act as institutional mints and liquidity providers for USHP; Forward Industries, a treasury company associated with Solana, has pledged up to $50 million.
Furthermore, USHP plans to connect to lending markets, yield protocols, and trading platforms, allowing tokens to enter more on-chain financial scenarios. Compared to the relatively independent real estate index futures of the past, this design is expected to broaden the product's use case, making real estate price exposure a configurational asset in on-chain portfolios.
From a product structure perspective, what Index Industries is attempting to establish is not just a housing price index investment tool but a financial infrastructure that combines index pricing, reserve management, issuance, redemption, and institutional liquidity.
However, these arrangements are still primarily at the product design and launch preparation stage. The monetization capability of housing-related reserve assets, the performance of the redemption mechanism under market pressure, and whether a secondary market can form continuous buy and sell demand all require real operational data for validation. What Index Industries needs to verify is whether the tokenized financial structure can facilitate sustained trading.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


