TL;DR
- Stifel has taken the leadership transition as the baseline scenario and lowered Nvidia's target price from $315 to $205 while maintaining a buy rating.
- This adjustment mainly focuses on the valuation multiples, with Stifel reducing the expected price-to-earnings ratio for the fiscal year 2028 from 20 times to 13 times, while still expecting recent performance to slightly exceed expectations.
- Dan Ives and Gene Munster had previously estimated that Jensen Huang’s departure could reduce Nvidia’s valuation by 20% to 30%, but at that time, the probability of departure was only 10% to 15%.
- With reports of replacement and successor searches, the early judgment that "departure risks have been priced in by the stock" needs to be re-evaluated.
- TIKR calculated that with earnings expectations unchanged, a discount of 20% to 30% would compress Nvidia's forward price-to-earnings ratio to about 10 to 12 times.
- If subsequent export restrictions affect the forecasted sales, the market would need to adjust its earnings expectations, with both valuation multiples and earnings potentially under pressure.
Jensen Huang’s iconic leather jacket is becoming a metaphor for Wall Street's discussion on Nvidia's valuation.
On November 10, Scott Galloway described on the "Pivot" podcast that the AI industry seemed to "rely on a leather jacket for support" that night. As Nvidia's board launched an independent investigation into Huang, investors began pricing in a scenario that had rarely been seriously discussed before—how much is Nvidia worth if the founder leaves?
Some analysts provided initial judgments estimating that the valuation could drop by 20% to 30%. Subsequently, brokerages began adjusting target prices. On November 12, according to a report by Investing.com, Stifel lowered Nvidia's target price from $315 to $205, a decrease of about 35%, while maintaining a buy rating.
As of the time of the report's release, Nvidia had not announced any leadership changes. However, in Stifel's valuation framework, this transition has already become the baseline scenario.
The Value of Jensen Huang Begins to Reflect as a Price-to-Earnings Discount
Stifel's adjustment provides a set of specific numbers for "How much is Jensen Huang worth."
The institution adopted an expected earnings per share of $15.65 for the fiscal year 2028, which will be used to calculate the target price's price-to-earnings ratio from 20 times to 13 times. Based on this metric, a 13 times price-to-earnings ratio corresponds to approximately $203, close to the new target price of $205.
The price-to-earnings ratio reflects how much investors are willing to pay for each dollar of earnings. When earnings forecasts remain at similar levels, a decline in multiples indicates that investors' confidence in future growth is weakening, leading to a reduction in the price they are willing to pay.
Stifel remains relatively positive about Nvidia's recent operational performance. The agency expects that the company's third-quarter results for the fiscal year 2027, to be released on November 17, may slightly exceed expectations, with supply still being a major constraint on growth, and there is potential for upward adjustment in the fiscal year 2028 earnings forecast. Meanwhile, the choice of successor, timing of the transition, whether core executives can stay on, and how sales channels and export compliance arrangements will be adjusted all increase the uncertainty of long-term growth.
Other institutions are also reassessing this risk. According to Investing.com, Bernstein downgraded Nvidia's rating from "outperform" to "market perform," lowering the target price to $200. Morgan Stanley removed it from its preferred stock list but retained its overweight rating and $300 target price. Various institutions’ weighing of earnings and valuations has shown significant divergence.
Jensen Huang's importance first manifests in Nvidia's organizational structure. Robert Cyran, a columnist for Reuters Breakingviews, pointed out that more than 60 people report directly to Jensen Huang, with four senior executives having equivalent status. This structure, which revolves around the founder, makes it challenging for a successor to simultaneously take on multiple responsibilities such as technical judgment, internal coordination, and customer communication, thereby increasing the difficulty of a rapid transition.
External business relationships also test the successor. Large clients such as Microsoft, Amazon, and Google continue to purchase Nvidia chips, while they are also motivated to develop lower-cost self-developed products. Jensen Huang increased the cost of switching suppliers for clients by expanding supporting software and hardware, while establishing financing cooperation with institutions like Apollo and Blackstone to help clients raise funds for chip purchases. Cyran believes that investment and financing support for smaller clients can also help broaden the buyer base and limit the bargaining power of a few large clients.
This arrangement connects product competitiveness, client financing, and order growth. Whether the successor can continue relevant collaborations will impact investors' judgments about future revenue and profit margins, and will determine how much of a valuation premium Nvidia can retain.
The Impact of 20% to 30% Depends on Departure Probability
Before Stifel adjusted its target price, Dan Ives and Gene Munster had already attempted to quantify the impact of Jensen Huang's departure.
Dan Ives from Yorkville Ives & Co. stated on November 10 that if Jensen Huang were to be removed from the CEO position, Nvidia's company and stock value could drop by 25% to 30%. At that time, he estimated the probability of such a scenario occurring at about 15%.
Gene Munster from Deepwater Asset Management provided an impact magnitude of about 20%. He believed that the stock price had potentially reflected about a 25% probability of departure, while his own judgment was 10% to 15%.
TIKR conducted a simple probability-weighted calculation based on this. According to Ives' judgment, a 25% to 30% valuation loss multiplied by a 15% probability of occurrence would correspond to an overall valuation impact of about 3.75% to 4.5%. According to Munster's judgment, the impact would be about 2% to 3%.
Based on these assumptions, TIKR indicated in an article on November 11 that the two consecutive trading days of decline may have already priced in most of the departure risk.
However, this conclusion heavily relies on the timing of the news release.
Subsequently, the Wall Street Journal reported that the board was preparing to replace Jensen Huang, and Bloomberg reported that the company had hired a headhunting agency and was considering appointing an interim CEO. By the time Stifel published its latest assessment, the leadership transition had already entered its baseline scenario. The earlier assumption of a 10% to 15% probability also needs to be re-evaluated.
If investors believe that departure is becoming increasingly likely, even if their assessment of the valuation loss following departure remains unchanged, the risk discount that needs to be reflected in the current stock price will also expand. Whether risks have been adequately priced into the stock requires estimating both the probability of departure and the actual impact of management changes on the company's value.
If Earnings Expectations Remain Unchanged, Nvidia Could Drop to a 10 to 12 Times Price-to-Earnings Ratio
TIKR believes Nvidia's valuation still has support, based on the market's expectations for its earnings growth.
According to TIKR's cited consensus forecasts, Nvidia's adjusted earnings per share will rise from $9.32 for the fiscal year ending January 2027 to $21.41 for the fiscal year ending January 2029, more than doubling within two years.
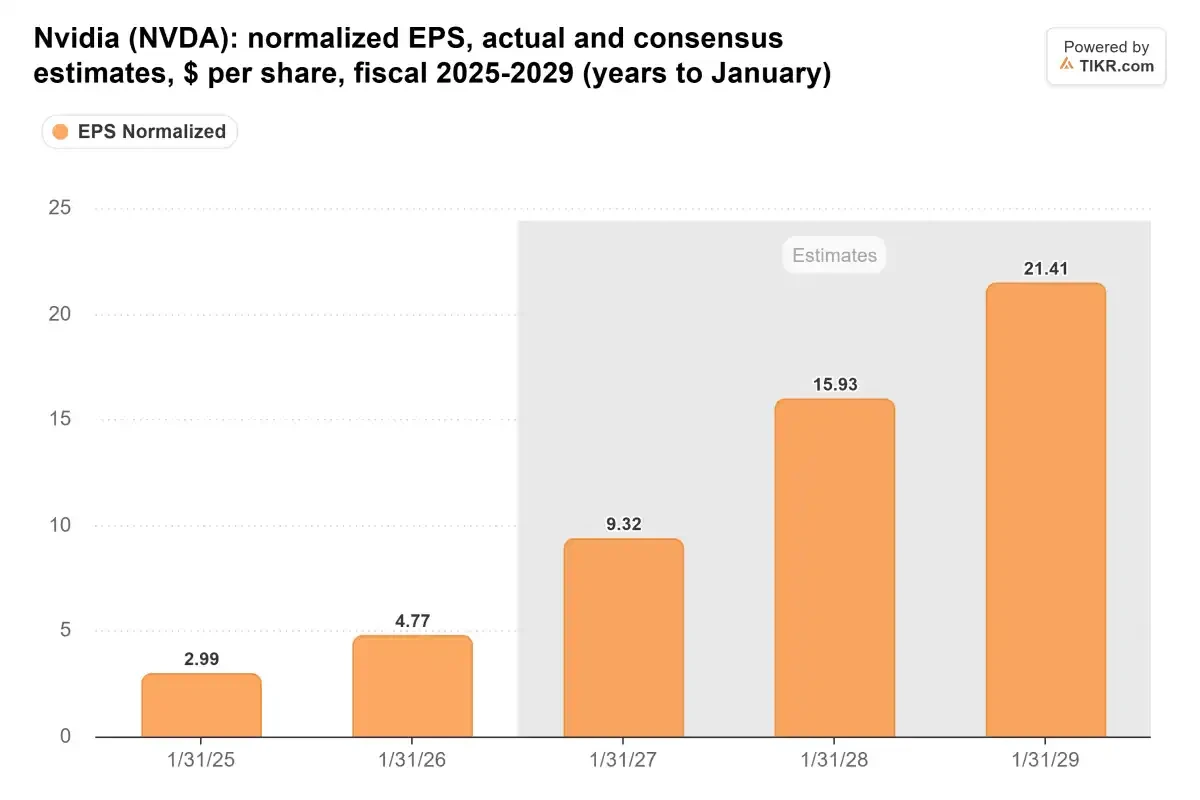
Nvidia's adjusted earnings per share for the fiscal years 2025-2029, in USD. The gray area represents the market consensus expectations.
TIKR's data shows that on November 9, Nvidia's expected price-to-earnings ratio for the next 12 months was about 14.8 times, at a low point over the past three years, below the average level of about 30.1 times during the same period.
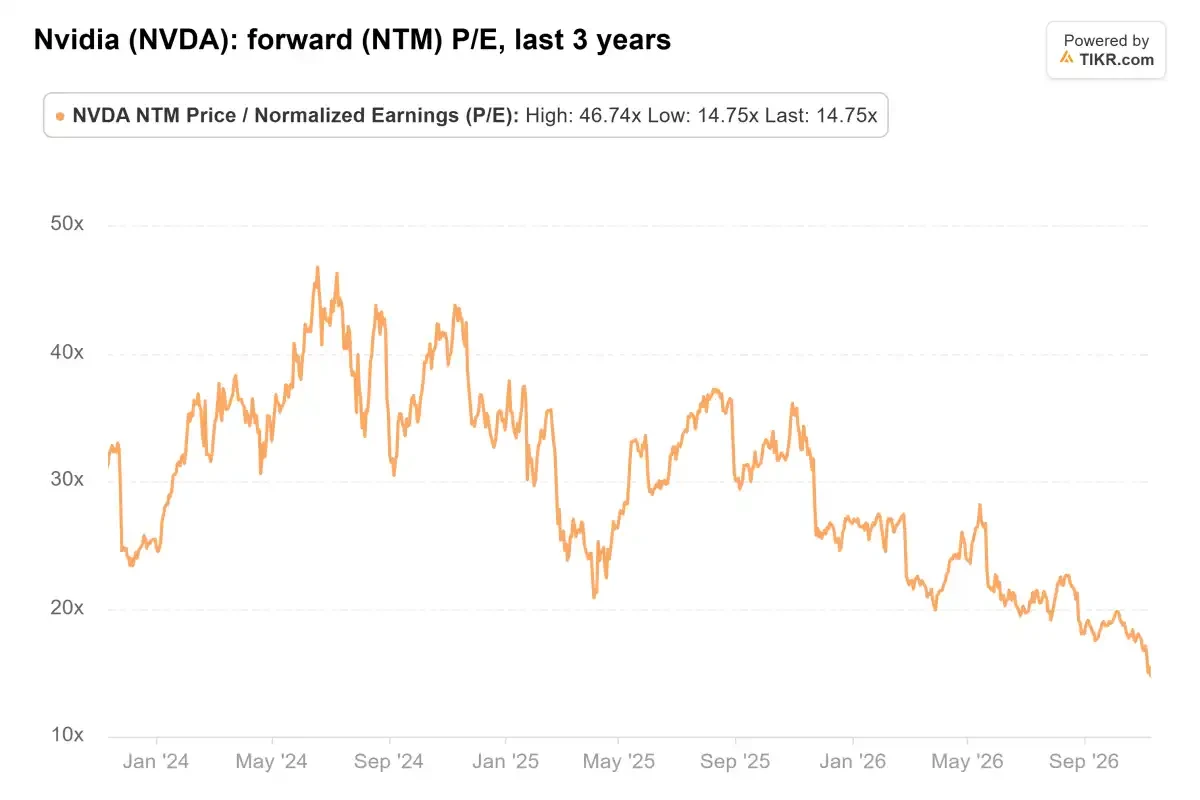
Nvidia's expected price-to-earnings ratio for the past three years, with the latest value shown as 14.75 times.
If earnings forecasts remain unchanged, and the stock price incurs a 20% to 30% discount based on this, the corresponding price-to-earnings ratio would be around 10.4 to 11.8 times. This is what TIKR refers to as "Without Jensen Huang, Nvidia could become a stock with a 10 to 12 times price-to-earnings ratio."
This calculation uses the stock price and earnings forecasts at that time. As prices and market judgments change, the corresponding multiples will also change. In addition, TIKR uses expected earnings for the next 12 months, while Stifel uses expected earnings for the fiscal year 2028, leading to differences in valuation metrics.
Both calculations reflect that the market still expects Nvidia's profits to continue to grow, but is reconsidering how much price it should pay for those profits. The lack of a clear successor, stability of management, and continuity of strategy may all become factors leading to lower valuation multiples.
How much of this discount ultimately remains will depend on whether Nvidia can provide a credible transition plan, and whether the successor can maintain product execution, customer relationships, and financing collaborations.
If Earnings Forecasts Are Also Downgraded, the Reassessment Will Deepen Further
The above calculations have a common premise—the anticipated profits among analysts can be realized.
TIKR pointed out that if subsequent reviews lead to tighter export regulations that impact the already forecasted sales, analysts would need to lower their earnings per share expectations. At that time, the target price could face pressure from both declining earnings and compressing valuation multiples.
Nvidia's previous performance outlook has already assumed there are no revenues from data center computing business in China. Therefore, the effect of subsequent policies needs to be implemented on specific clients, regions, and sales channels to observe whether new restrictions touch existing revenue forecasts.
The financial report on November 17 will provide a test. The company's previous quarterly revenue guidance was $108 billion, with a 2% margin of fluctuation. Stifel expects the actual performance to slightly exceed expectations, and investors will also focus on subsequent growth guidance, as well as management's explanations regarding supply, customer demand, and leadership arrangements.
"How much is Nvidia still worth without Jensen Huang" currently depends on two sets of variables. If the company continues to deliver earnings growth, the market will mainly adjust the price-to-earnings ratio it is willing to pay; if management changes further affect business execution and order expectations, earnings forecasts may also face downgrades.
Whether the transition plan can stabilize the core team, whether product plans can progress on schedule, and whether clients can continuously obtain funding to purchase computing power will determine whether Wall Street's current discount is a risk compensation during the transition or a more permanent valuation adjustment.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


