Tax planning should be done early and it should be done seriously.
Written by: Liu Honglin
Today, I saw a piece of news from the Financial Associated Press, and honestly, I was a bit shocked by the numbers.
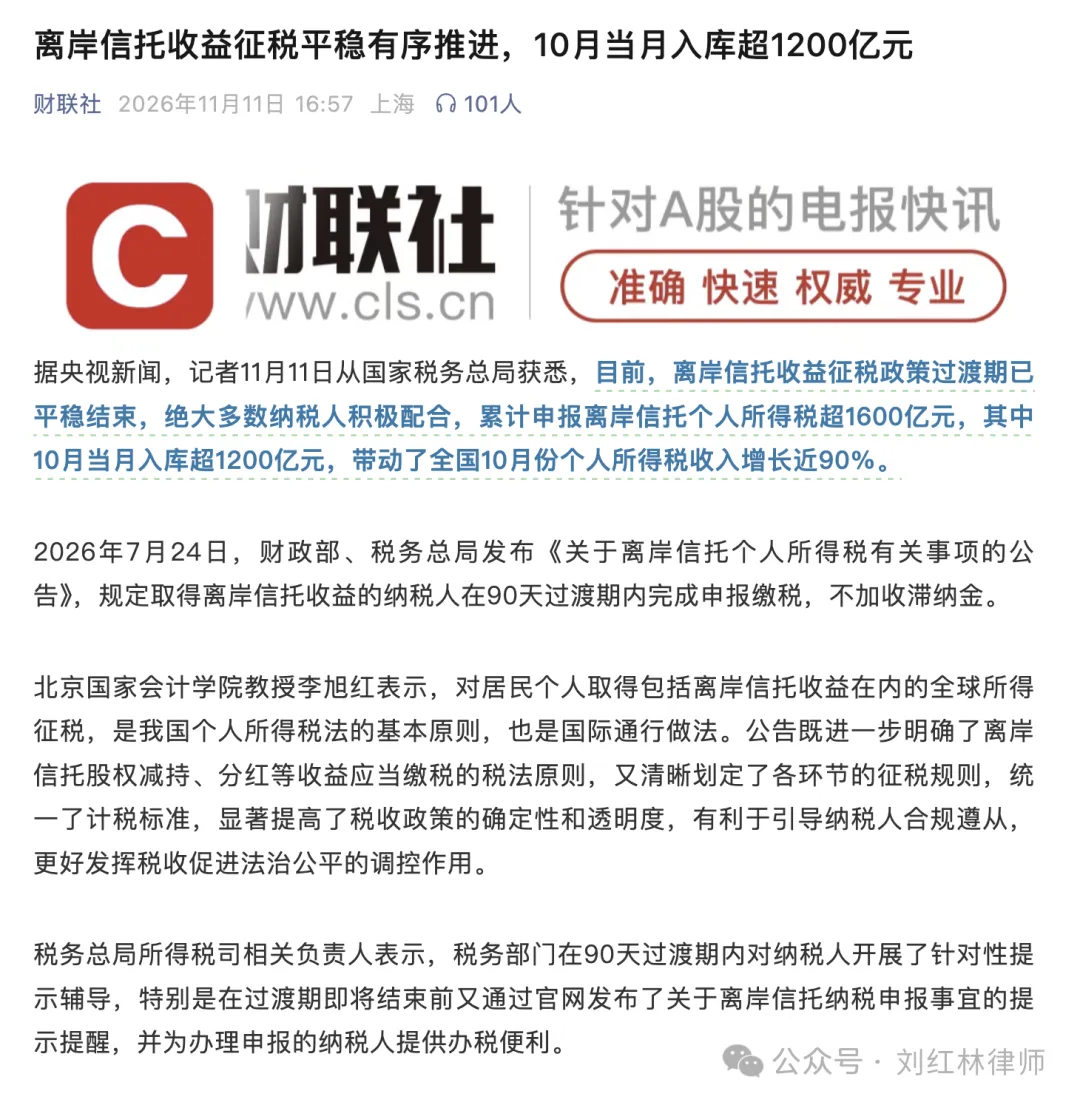
The State Administration of Taxation revealed that the 90-day transitional period for taxation on offshore trust income has ended smoothly, with cumulative declarations of offshore trust personal income tax exceeding 160 billion yuan, and more than 120 billion yuan collected in October alone, directly driving a nearly 90% increase in personal income tax revenue nationwide in October.
In one month, 120 billion. This is not the result of some pilot city, but a nationwide figure. In other words, the money that has quietly sat in offshore structures for many years has truly been brought out to pay taxes this time.
Why are Hong Kong stock owners in a hurry to raise funds?
If you have been observing the Hong Kong stock market, you should have noticed a phenomenon over the past few months: many company owners and actual controllers are intensively raising funds. Some are pledging stocks, some are directly reducing their holdings, and some are even borrowing money as a bridge.
Where is this money going? A considerable part is being used to pay this offshore trust income tax.
On July 24 this year, the Ministry of Finance and the State Administration of Taxation issued a notice, specifying that taxpayers who receive offshore trust income must complete their tax declaration during the 90-day transitional period without incurring late fees. Translated, this means: you have three months to proactively pay what you owe, and there will be no penalties for past periods; after this window, late fees, audits, investigations, and public exposure will all apply.
Looking back now, the design of this window period was very effective. The vast majority of taxpayers chose to cooperate, and the collection of 120 billion yuan is the best proof. Those who rushed to raise funds before the end of the transition period were not suddenly bearish on their own stocks, but rather calculated clearly: it is better to make friends with the tax authorities than to race against them.
In 2026, cross-border tax is the real main line
If we pull out the regulatory trajectory in China this year, we will find a very clear thread: taxes, especially cross-border taxes, are an unavoidable theme in 2026.
In May and June, Futu and Tiger securities were investigated due to cross-border securities business, and the market already felt a round of shock. Following that was the taxation of offshore trusts. Further down the line, the nature of the funds and reporting obligations of Hong Kong insurance have also been repeatedly discussed. Even cryptocurrencies—tax authorities are already paying attention to the path of transferring assets offshore through crypto assets.
In the past, when discussing cross-border assets, regulatory authorities somewhat turned a blind eye: not that they didn't care, but that the priority wasn't very high and the methods weren't very comprehensive. But starting this year, those eyes are completely wide open. From securities accounts to trust structures to on-chain assets, they are gradually tightening control.
There are no secrets left in the accounts
Why have they been able to collect so accurately this time? Because, technically, traditional offshore arrangements have long since lost any secrets.
Under the CRS (Common Reporting Standard) framework, financial account information is automatically exchanged annually between mainland China and more than 100 jurisdictions worldwide. Your bank and securities accounts in Hong Kong, Singapore, or the Cayman Islands, along with balances, earnings, and account holder identities, are essentially transparent to domestic tax authorities. The notion that "offshore trusts cannot be traced" has long become outdated in the CRS era.
What is even more noteworthy is the next step. Starting in January 2027, Hong Kong will join CARF (Crypto-Asset Reporting Framework), requiring crypto asset service providers to report user identity information, transaction records, and balances to tax authorities, with automatic exchange between jurisdictions.
This means that what is exposed in your bank account today will be repeated in your crypto asset account next year in almost the same manner.
Cryptocurrency exchanges are also reporting data
There is now a saying within the community: using cryptocurrency for investment and holding poses no tax risks because of "anonymity on the chain."
This judgment does not hold up on a theoretical level. Take a look at those top compliant exchanges; their backend has long been integrated with dedicated tax reporting interfaces. What does this mean? It means that from the first day of product design, exchanges have been preparing to submit data to regulatory authorities.
The logic is actually very simple. For exchanges to survive, they must obtain and maintain licenses. Whether they hold licenses from the United States, Dubai, Singapore, or Hong Kong, compliance obligations are part of the licensing requirements, and the exchange of user information is one of the strictest obligations. Exchanges will not and dare not risk their own existence to help users hide tax liabilities.
Therefore, "crypto assets are tax-exempt" has never been an attribute of the asset; it is at most a window period before regulatory enforcement. A window period and an additional firewall are entirely different in legal consequences.
Gray areas, only a time window remains
The 160 billion from offshore trusts once again verifies one thing: if regulatory authorities want to push something deeply, there is almost no resistance at the execution level. 90 days, 120 billion collected, without the need for combative law enforcement, just a notice and a transitional period is enough.
This judgment also holds true for crypto assets. My perspective is that in the coming one to three years, there may still be a certain gray area for crypto assets in terms of taxation—after all, the information exchange for CARF will not start until 2027, and there are extensive technical and legal details to implement for historical transaction tracing. But this is really just a matter of time, not a matter of space.
Taking "regulatory authorities have not yet looked into it" as "regulatory authorities cannot look into it," is the most common and costly cognitive error in this market.
My suggestion
If you or your family actually have offshore assets, trust structures, or hold a large amount of crypto assets, my advice is very straightforward: tax planning should be done early and it should be done seriously.
What is meant by "seriously" is to make structural arrangements within the legal framework—how resident identity is determined, what structure the assets are placed in, at what stage earnings are realized, and how reporting obligations are fulfilled; each of these must have a clear basis. It should not rely on temporary measures like "not reporting," "underreporting," or "changing wallet addresses" to gamble on the patience of regulators.
The issue with temporary measures is that they are never free. The pit you bypass today will come back to you in two years in the form of late fees, fines, or even criminal liability, including both principal and interest. The offshore trust case is a prime example: proactive reporting during the transition period only involves paying what should be paid; being caught after the transition period results in taxes plus late fees plus fines, and serious cases may even lead to public exposure.
Tax compliance here represents an early arrangement as a cost, and a late arrangement as a price to pay. The 120 billion already indicates that the state is serious about this.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


