Strong data could turn into a nightmare for the market—it will provide ammunition for the Federal Reserve's December rate hike, adding another "interest rate bomb" amidst the collapse of AI trading and massive sell-off by CTA funds.
Written by: Xu Chao, Wall Street Journal
The U.S. October non-farm payroll report is scheduled to be released on Friday (November 6) at 8:30 AM Eastern Time. The market generally expects data to rebound from the September low, but the timing of this report is extremely tricky—just one day before the data release, tech stocks were hit hard, with the Nasdaq 100 Index plummeting 6.36% in a single day, marking the worst day since March 2020, and AI trading completely collapsed.
Thursday’s market turbulence has profoundly changed the framework for interpreting the employment report. The S&P 500 Index fell 4.36% in one day, and the Philadelphia Semiconductor Index plummeted 12%, with the VIX panic index jumping 11.5 points to 28, leading to a sharp contraction in market liquidity. In this context, an unexpectedly strong employment data may not only fail to bolster market sentiment but could also reignite expectations for a Federal Reserve rate hike in December at the worst possible time, adding fuel to an already fragile market.
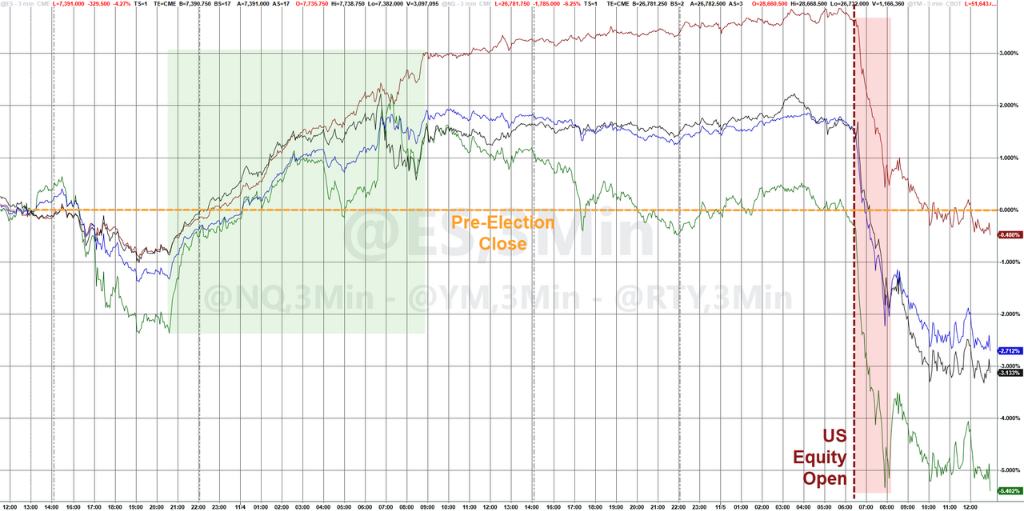
From the reaction in the options market, investors are preparing for significant volatility. The implied volatility for straddles on the S&P 500 Index reached 1.45% on Friday, the highest single-day pricing level since March of this year—whereas the actual realized range for straddles on Thursday was nearly 8 times the pricing.
Data points to a rebound, but divergences remain
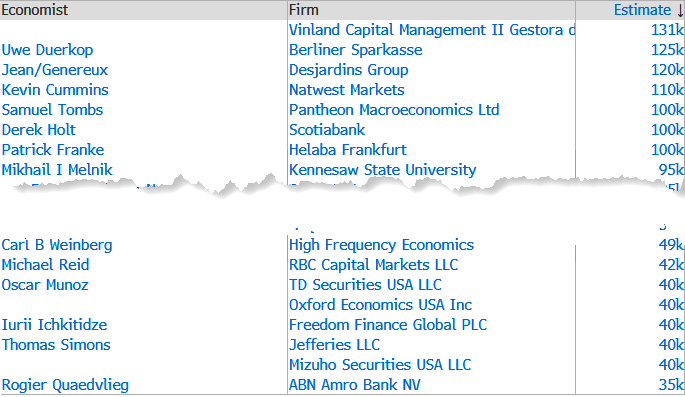
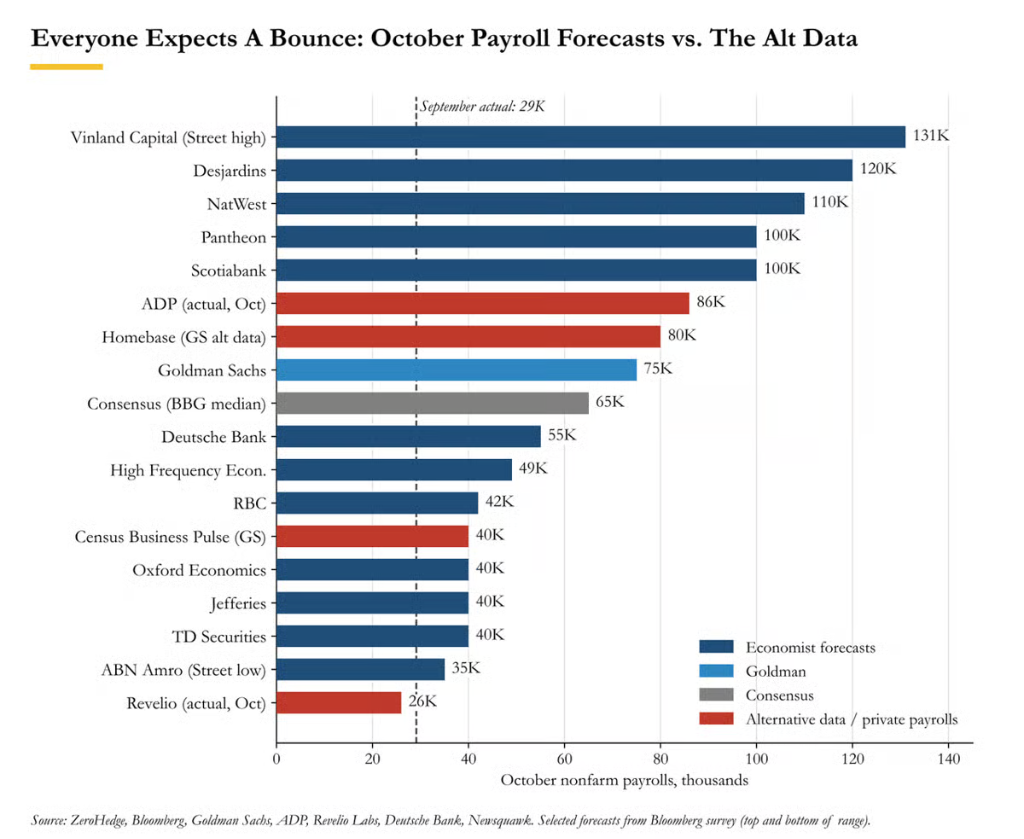
The market generally expects the October non-farm payrolls to rebound significantly from 29,000 in September. A Bloomberg survey shows that Wall Street's forecast ranges from 35,000 to 131,000, with a consensus expectation of about 65,000. The unemployment rate is expected to remain unchanged at 4.2%, and average hourly wages are anticipated to grow 0.3% month-on-month, while the year-on-year growth rate is expected to drop to 2.9%, falling below 3% for the first time since May 2021.
Goldman Sachs forecasts an increase of 75,000 in non-farm payrolls, higher than the consensus expectation, and estimates a 70,000 increase in private sector employment. Goldman’s predictions are based on: the number of initial jobless claims dropped to 195,000 during the survey reference week in October, down from 204,000 in September; JOLTS data indicating an unexpected surge of 333,000 in job openings in September to 7.523 million, a record high; ADP private employment showed an increase of 86,000, above expectations; Challenger data indicated that the number of announced layoffs in October was 43,994, down 71% year-on-year, marking the lowest since 2023. From a seasonal perspective, Goldman also points out that employment data typically rebounds in October when the Labor Day holiday falls later in September, with an average historical acceleration of about 50,000 positions.
However, there are also voices pointing to downside risks. Data service provider Revelio’s tracking shows that October’s new employment only reached 26,000, significantly below the previous month’s revised value of 67,600, marking a clear outlier at the low end among forecasts.
Unemployment rate and wages: details matter more than headlines
The unemployment rate reading may become a more market-impactful variable than the total non-farm number this Friday.
The September unrounded unemployment rate was 4.18%, meaning that a very slight change could push it to 4.1% or 4.3%. Goldman Sachs, Turnleaf, and the Chicago Fed all lean towards the belief that the unemployment rate faces downside risks, suggesting it may converge to a lower level implied by the sustained number of applicants for unemployment benefits. Goldman also points out that its comprehensive "slack tracker" of ten labor market indicators currently reads 4.6%, "indicating that the labor market is actually weaker than what is presented by the single unemployment rate."
On the wage front, if the consensus expectation is realized, the annual wage growth rate will fall below 3% for the first time in over four years.
Goldman's broad wage tracking, which combines several wage indicators, shows that the annualized quarter-on-quarter growth rate for the third quarter is 3.0%, while the year-on-year growth rate is 3.3%. Deutsche Bank’s nominal wage growth proxy is expected to slightly decrease to 4.1%, which the bank believes "still supports robust consumer spending growth." Notably, productivity in the third quarter jumped 3.6% year-on-year, far exceeding the expected 2.7%, while unit labor costs unexpectedly decreased by 0.7%.
Federal Reserve path: rate hike expectations eroded by AI collapse
In the October monetary policy meeting, the Federal Reserve kept rates unchanged, but two members voted against.
Fed Chairman Warsh signaled that rates would rise at a "measured pace." Even during the Thursday Nasdaq plunge, Cleveland Fed’s Hammack reiterated that monetary policy "needs to shift towards a restrictive stance" and leaned towards "more frequent and smaller adjustments"; Richmond Fed’s Barkin expressed expectations for further rate hikes but remains uncertain about "the magnitude and pace."
Goldman economists expect the Fed to implement a second and final rate hike in December, raising the federal funds rate target range to 4.00%-4.25%, followed by a pause and resuming rate cuts between the end of 2027 and early 2028. Before entering this week, the market's implied pricing for a December rate hike was around 21 basis points (approximately 83% probability).
After the extreme sell-off of the AI sector on Thursday, the implied pricing for a December rate hike has dropped to 17.25 basis points (around 70% probability), and the yield on 2-year U.S. Treasuries has fallen about 12 basis points in a steepening bull market. Goldman’s rate sales team points out two major downside risks facing the front-end and belly of the rates curve: one is that Trump could restart strikes against Iran after the midterm elections, reigniting inflation expectations; the other is that the collapse of AI trading could cause a substantial growth shock. According to Axios reports on Thursday evening, Trump stated that decisions regarding the Iran War "are coming soon."
A strong report may be the last thing the market needs
Overall, leading up to the release of this non-farm data, the labor market fundamentals exhibit a strong pattern that is rare in recent years: initial jobless claims are near a 57-year low, October layoffs reached the lowest level in 2023, JOLTS job vacancies spiked by 333,000, and ADP data came in better than expected. In this situation, the risk of the employment data exceeding the consensus expectation of 65,000 actually leans to the upside, and the unemployment rate could also decline.
The problem lies here. A strong report would provide ample justification for Warsh, Hammack, and Barkin to raise rates in December—at a time when the Nasdaq has just experienced the most brutal trading day since March 2020.
Goldman’s rate sales team believes that a single data point cannot completely eliminate the market's pricing for a rate hike; rather, a reasonable employment number would likely bring the December rate hike back to the table, further complicating the existing AI issues with an additional interest rate problem. Given the current positioning dynamics—CTA strategies have begun net selling futures, and long institutions have "again hit a deadlock"—this is not a recipe for a bottoming rebound. Goldman’s model shows that if the market drops another 2.5 standard deviations from the current level, the potential sell-off scale for S&P 500 futures could reach $7.48 billion within the next week.
It is worth noting that the September non-farm data revision for August (from the initial value down to 133,000 and ultimately revised to 29,000) is also worthy of close attention from the market—the last revision had an impact on the bond market and rate pricing that was comparable to the headline data itself.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


