Author: Melly in Silicon Valley
What you sold today is a bill
On November 5, the Dow Jones Industrial Average fell by 1,833 points, the Nasdaq fell by 5.52%, and the Philadelphia Semiconductor Index fell by 12.25%—the last time it dropped this much was on March 2020, the day the world went into lockdown. The S&P 500 and Nasdaq both recorded their worst day since the "Liberation Day" tariff crash on April 4, 2025. Nvidia closed at $181.60, losing more than $440 billion in market value in a day, turning negative for the year; the seven giants collectively evaporated over $1 trillion in one day; Micron and AMD each dropped 17%, Broadcom fell 10%, Arm dropped 13%, and Qualcomm fell 9.5%. The VIX volatility index surged nearly 70% in one day, marking the third-largest single-day increase on record since 1990. In the S&P 500, 34.6% of components are down more than 20% from their 52-week highs.
24 hours ago, the Democrats swept both houses of Congress, and the Dow had just risen by 3%, about 1,570 points, marking the best post-midterm election trading day since 1982. Today, not only is everything given back, but there's an additional drop of 260 points.
If you held Nvidia, Micron, or Broadcom, your account likely shrank by more than ten percent today. What you most want to know has probably shifted from "why did it drop" to "should I sell." A post by Gary Marcus on X has been viewed by 240,000 people: "A total slaughter... the day of reckoning for the AI industry may finally have arrived." People around you are already saying the bubble has burst, and you're hesitating whether to run with them.
Let’s make a judgment.
Bearish in the short term. There are still weeks of drops to come. Two events in mid-November are lined up—the Nvidia earnings report on November 17, and Anthropic's IPO, potentially worth up to $2 trillion, going public as early as the week of November 16. Plus, there’s a strong liquidation record that just emerged today: that 24-year-old genius, who had already faced a liquidation in July, announced on X that he has exploded again today. The Nasdaq 100 has entered the correction range for the third time this year, and the previous two times created new highs in about two months; this time, it’s very likely that won’t happen.
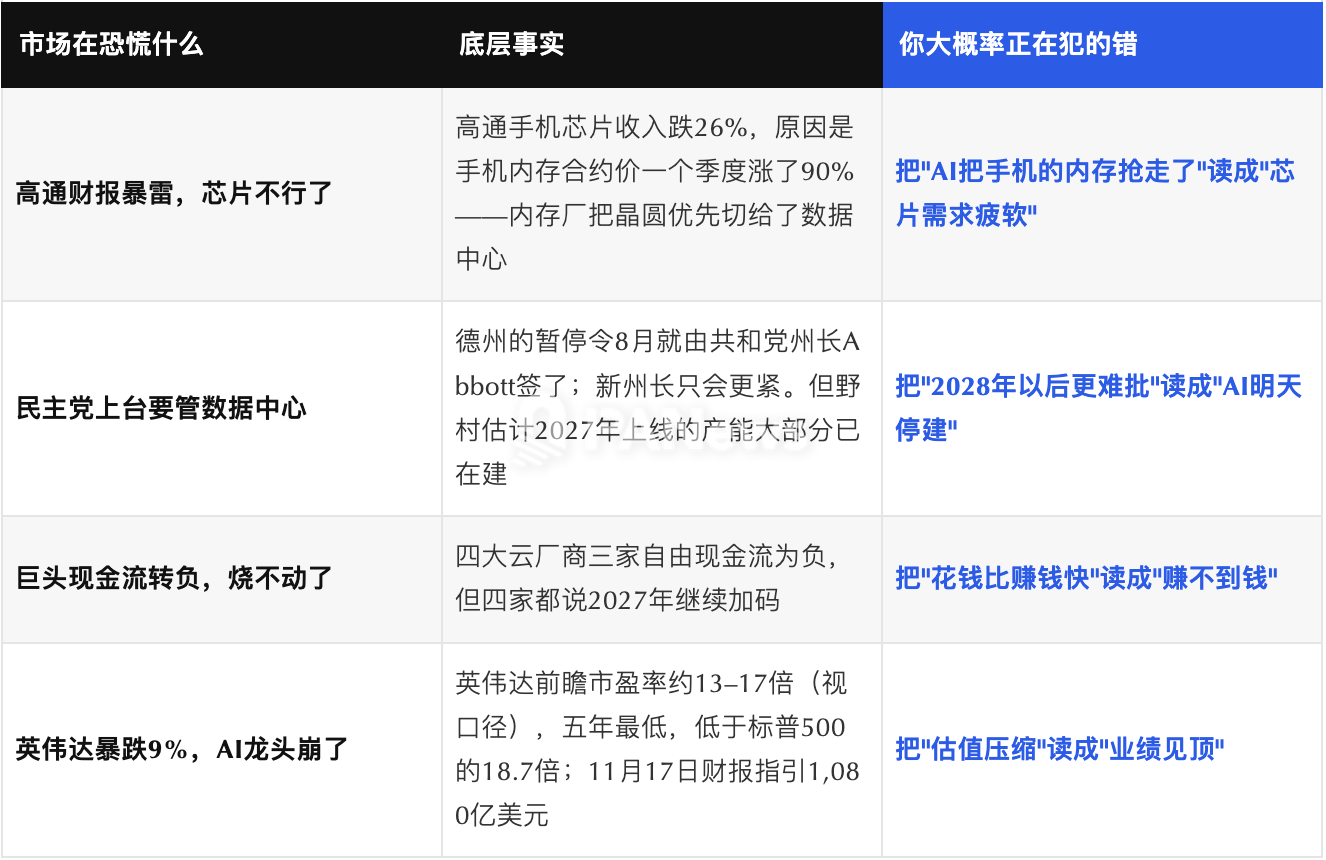
Bullish in the long term. Because those selling today were mistaken about what to sell. They sold Texas approvals, Alphabet's cash flows, and Qualcomm's memory bills. All three are indeed real, and will not improve in the short term. But the demand for AI has not changed one bit: Microsoft's CFO stated on October 28 that "customer demand continues to exceed available supply"; Amazon stated that by 2027, their capacity is "nearly sold out"; Anthropic's quarterly revenue has skyrocketed from $1.4 billion to $17 billion in a year.
Ted Parkhill from Incline Investment said something today that aligns almost perfectly with my judgment: the market is shifting from "the promise of AI" to "the price of AI." The bills are expensive, but buyers are still lining up.
Why today: Three bad things landed on the same morning
Looking at any single one of these events is not enough to cause the semiconductor index to drop 12% in one day.
The first event: Texas has changed, and it's a bipartisan tightening bid. Many people think that "the data center moratorium" is the campaign slogan of the new Democratic governor. They are wrong. The current Republican governor Greg Abbott had already ordered ERCOT (the Texas grid operator) to audit new data centers for grid connection on August 3, 2026; in September, he ordered the state Environmental Quality Committee to stop issuing permits for new data centers. Democratic challenger Gina Hinojosa's position is to codify the moratorium into state law "until the legislature establishes rules." Then she won, with 57% to 41%.
Understanding the sequence of this event: the challenger shouts first, the incumbent follows suit, and the incumbent still loses. This indicates that opposition to data centers has become a bipartisan consensus; the election proves one thing—tightening regulations leads to better election outcomes. According to estimates from Wells Fargo, 27% of planned data center power capacity in the U.S. is in Texas. UBS estimates that approximately 30% of the anticipated new capacity in 2028 may be at risk due to construction moratoriums. Ohio's new governor Amy Acton has promised to impose conditional moratoriums on new data centers upon taking office: covering all grid costs, using union labor, and building on old industrial sites. NBC's exit polls show that nearly 80% of respondents oppose building data centers in their communities. Of 41 local ballot initiatives to limit data centers, 40 passed.
During the All-In podcast live on election night, Chamath Palihapitiya observed the Texas vote counts and said: "The only thing that can drag down the U.S. economy is AI trading; and the only way to drag down AI trading is to drag down data centers." Musk dumped $474 million on the Republicans, and after the election results came out, he tweeted two messages: one said "the space data center now looks quite attractive," and the other said, "it seems that my space lasers intervening in the election didn’t work this time." Senator Ed Markey told tech executives: you need to "plant a few more forests so we have enough to print the tickets."
The second event: Qualcomm's earnings report puts "memory" in the spotlight. Qualcomm reported a revenue of $10.3 billion after hours on November 4, exceeding expectations, and the revenue guidance for the next quarter was also higher than expected, but mobile chip revenues fell 26% year-on-year. CEO Cristiano Amon stated: "The memory shortage and price increases across the industry will determine the scale of the entire mobile phone industry." Arm’s earnings report on the same day had royalty revenues of $670 million, which was below expectations; the CFO mentioned the same issue: memory price hikes are suppressing sales of mid-range and low-end phones.
The third event: the string had already been pulled to the limit. The Nasdaq 100 had closed into the correction zone on November 2, down 10.4% from the peak on October 6, marking the third time this year. In October alone, the Nasdaq 100 evaporated over $2 trillion. After Alphabet's earnings report, it dropped 13% in a single day, the largest single-day decline in history, losing $500 billion in one day. Microsoft lowered its 2026 capital expenditure from $175 billion to about $170 billion, citing delays in the delivery of third-party data center capacities. Intel dropped 29% in one day on October 30, its largest drop since 1974. The string was already pulled to the limit before the election; the election results were just what made it snap.
In October alone, $2 trillion was evaporated, and no one shouted "the bubble has burst." On November 5, after one day of decline, everyone was shouting. The difference is not in the drop size; this time, no one knows when they will be able to buy back. The Kobeissi Letter posted half an hour after the market opened: U.S. tech stocks "evaporated $1.3 trillion in market value in 30 minutes." Nomura's Charlie McElligott used a more severe term: the market is in a "firing squad"—everyone sold out the leaders. Vanda Research defined retail investors' behavior as a "complete surrender."
Plain interpretation
A highway has cars lined up to the toll booth. In October, everyone was arguing that "the roadwork is too expensive, when will it be profitable." On November 3, the newly appointed transport director said, "Let's pause the approval of new segments"—actually, the previous director halted it in August; the new director just indicated it would be paused longer. On November 4, people first celebrated, saying, "At least we know who the director is now." On the morning of November 5, the convenience store next to the toll booth (Qualcomm) reported, "All the items on the shelf have been bought by those doing the roadwork." With three events overlapping, everyone squeezed toward the exit at once.
The three locks lock the same thing: the pace of construction. The political lock restricts the speed of approvals, the cash flow lock restricts the speed of financing, and the squeeze-out locks the speed of materials. None of them touch demand. Remember this phrase; every section afterward will return to it.
The first lock: Data centers became a target in the elections
This is the hardest lock to unlock among the three.
Underlying mechanics: the profit from data centers is national—model services are global, profits go to shareholders; costs are local—electricity, water, land, grid upgrades are borne by surrounding voters. Profits go to shareholders, costs go to voters. This kind of business will face backlash in any place with ballots—it’s just a matter of time. On November 3, that time arrived.
Some may counter: do data centers actually raise ordinary people's electricity bills? Economically, this matter is still under debate. Evidence from the wholesale side is robust: PJM (which covers the electricity grid across 13 Eastern states) cleared the 2027/28 capacity auction at a price cap of $333/MWh, with about 5,100 of the new peak load of approximately 5,250 MW directly coming from data centers; PJM's independent market monitoring agency reported a 76% year-on-year increase in wholesale electricity prices in Q1 2026. However, retail-side instrumental variable studies found that data centers diluted grid fixed costs, resulting in a slight decrease in residential electricity prices.
This debate is politically no longer significant. The figures on the bill will not discuss econometrics with voters. The localization of costs is primarily a political fact, and then an economic debate; but ballots only recognize the former.
It takes years to unlock this lock. The Senate, governor, utility commissions, and local zoning: each layer can add another approval step. Greg Casar, chair of the progressive caucus, is already saying, "AI company CEOs should be summoned to testify under oath." Nomura’s judgment is that most capacities planned to be online in 2027 are already under construction; the projects set to come online in 2028 will truly be exposed to approval delays. BMI states more cautiously: a nationwide halt to construction is unlikely, but slowing down may cause overall investment to decline beyond expectations. Data from CBRE provides a side note: the pipeline of North American data centers under construction saw its first contraction since 2020 in the second half of 2025, due to community opposition and permitting obstacles.
Plain interpretation
A city wants to build a new airport. The entire nation benefits, but noise and land acquisition falls on the surrounding residents. Once residents start voting against it, the airport won't stop being built, but the approvals for the second and third runways will be delayed.
An example
The market today was very precise in its selling. Companies still on the drawing board were hit the hardest—Applied Digital dropped 15%, Ciena dropped 16%, data center operators transforming from Bitcoin mining Cipher and IREN dropped more than 14%; giants that already have electricity and land just fell along. Equibles estimates that out of eight companies in Texas with about 18.3 GW of pipelines, only about 20% have been approved, while 53% are still under review. Morgan Stanley’s James Sullivan stated more directly: due to limited new supply, "existing capacity is now significantly more valuable." Applied Digital’s CEO even said the moratorium "has enhanced the strategic value of our parks"—his stock still dropped 15%. The market today did not distinguish between blueprints and existing resources; this will be an opportunity discussed in section six.
The second lock:
Alphabet has been swiping credit cards for two consecutive quarters
The four major cloud providers (Amazon, Microsoft, Alphabet, Meta) have a combined capital expenditure guidance of approximately $730 billion for 2026, which is nearly an 80% increase from about $410 billion in 2025. Wall Street's expectations for 2027 are generally above $1 trillion, with Goldman Sachs estimating between $1.14 trillion and $1.2 trillion. Nvidia's CFO Colette Kress mentioned in an August conference call that the top five cloud providers' capital expenditure for 2026 is about $800 billion, rising to $1.3 trillion next year.
Where does the money come from? In the past, it was from operating cash flows, but that is no longer enough. Alphabet's capital expenditure in the third quarter was $51.4 billion, 121% of its operating cash flow, with a free cash flow of -$9.1 billion, marking the second consecutive quarter of negative free cash flow (the second quarter's -$5.9 billion was its first since going public in 2004). In the first nine months, it has net borrowed $76.3 billion. Meta recorded -$2.1 billion in free cash flow for the third quarter, the first time since 2012. Amazon recorded a -$42.4 billion in free cash flow based on the past 12 months. Among the four, only Microsoft is still positive at $18.6 billion, down 28% year-on-year.
Goldman Sachs estimated back in July that about 35% of cloud providers' capital expenditure in 2027 would need to rely on debt financing, with about $400 billion coming just from investment-grade bond issuances. Amazon’s CEO Andy Jassy stated in a conference call, "We can fund this plan," but when asked how, he replied, "I have nothing to share."
The borrowing environment has also changed. The yield on 10-year U.S. Treasury bonds is around 4.85%, which is about 75-80 basis points higher than a year ago. Brent crude oil prices dropped from $105 to $96 after the election but are still 52% higher than a year ago.
There is a deeper change than the idea that "the giants can withstand this while the small players are squeezed": giants with negative free cash flow are issuing bonds, effectively changing the funding sources for AI construction from "profits from ads and clouds" to "debt-market risk appetite." The speed of AI construction is now linked to the credit spreads for the first time. It’s fine when the 10-year is at 4.85%, but if credit spreads widen—whether or not it’s related to AI—the pace of construction will slow down passively. This is where the cash flow and political locks intersect: both locks are stalling construction speed.
Plain interpretation
Four wealthy individuals are bidding for a piece of land; previously, they used cash from their own pockets, now they have started swiping credit cards. The wealthy can swipe cards without issues, and banks still give them limits. But for the small developers who have followed behind and rely solely on borrowed money to enter the market, they suddenly find that interest rates have risen, approvals are slow, and the lands in their hands have turned into liabilities.
An example
The five-year credit default swap (CDS) for CoreWeave reached a historic high today; CoreWeave and Nebius have seen their stock prices halve since October 6. Oracle dropped 7-8% today, with debt around $125 billion in August, rated BBB-, close to junk status. The market today is penalizing these companies’ balance sheets: first borrowing money to build, and then waiting for customers to pay; as interest rates rise and approvals slow, they are squeezed from both ends.
The third lock:
Qualcomm lacks supply, Micron raises prices, and the market punishes both
This is the only one of the three events that has been interpreted incorrectly.
We need to be precise with the chain. First, memory manufacturers prioritized wafer production for HBM (high bandwidth memory, dedicated to AI chips) and server memory. Micron’s CEO stated they can only satisfy half to two-thirds of customer HBM demand; HBM capacity for 2026 is fully contracted. The second step is the consumer-grade memory contract prices skyrocketing: according to TrendForce data, DRAM contract prices will rise 90-95% quarter-on-quarter in Q1 2026, with LPDDR for phones increasing by about 90%, and another 63% spike in Q2, marking "the steepest rise in history." The third step is a collapse in whole machine shipments: IDC predicts a 12.9% drop in global smartphone shipments, the largest decline in a decade, with models below $200 dropping 20%; Intel predicts a 12% decline in PC shipments, with over a 20% drop in the second half. The fourth step is that Qualcomm, Arm, and Intel’s PC business reflect shipment reductions.
Intel's earnings report serves as the cleanest case. The same company, the same document: server demand is "the strongest in 15 years," but they cannot meet it; the PC business has been dragged down by memory prices, with gross profit margin guidance for Q4 dropping from 44.1% to 38%. One single company has just encapsulated how "AI is eating its neighbor."
Putting these three earnings reports together, the conclusion is: there is no softening of AI demand; AI demand is so strong that it's emptying the neighbor's rice barrel. This also serves as evidence of demand being squeezed out—every dollar of memory demand for AI replaces a dollar of smartphone demand. The tension on the supply side and the substitution of demand are two sides of the same coin; today, the market only saw the substitution.
Qualcomm dropped 9.5% due to lack of memory. Micron dropped 17%, and Micron is the one selling memory. The market punished both the ones lacking supply and the ones raising prices on the same day.
Plain interpretation
A very popular restaurant has opened on a street, taking away all nearby chefs, ingredients, and parking spaces. Several neighboring stores report poorer business and release loss announcements. And then someone says, "The food industry on this street is failing," and sells all the stores together, including that popular restaurant.
An example
Micron dropped more than Qualcomm today. Half of it was due to label sales—selling "semiconductor" shares; the other half is market asking a real question: with smartphone and PC shipments dropping 12% in a year, how much longer can memory price increases last? This question has no answer, but it is different from the idea of "softening AI demand." Most of those selling Micron today did not differentiate between the two. AMD's CEO, Lisa Su, said in an interview today only, "The market can sometimes be a bit shortsighted."
In 2000, there were empty houses, today, there are not enough houses
Let’s pull the lens back to 2000.
The fiber optic bubble looked like this: nearly 40 million miles of fiber were laid across the U.S. in five years with around $90 billion invested; by 2002, Merrill Lynch estimated that less than 10% of the laid fiber was lit. Cisco had a peak forward P/E ratio of over 150. WorldCom and Global Crossing went bankrupt. The hallmark of a bubble is when supply far exceeds demand, with prices upheld by stories of "someone will eventually use it in the future."
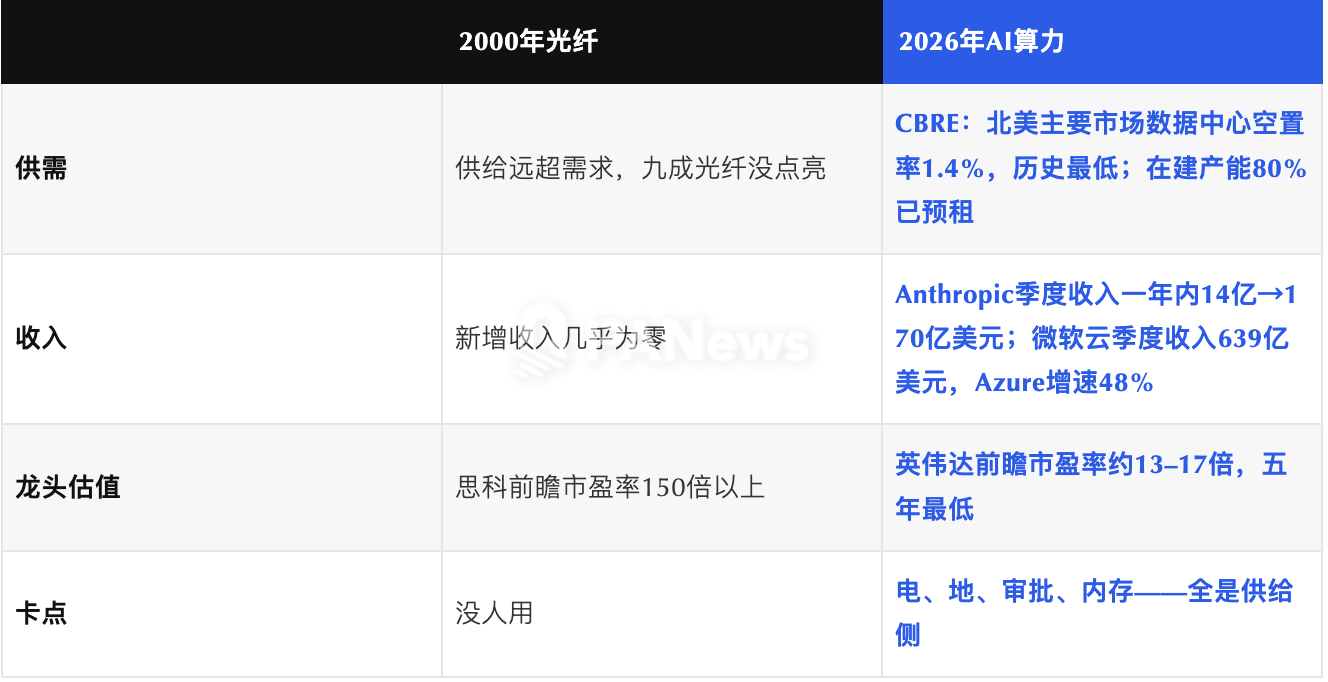
This table can be saved directly.
There is a detail more important than the table: the fiber laid in 2000 was eventually all used. The lesson from the fiber optic bubble has never been that "demand is fake"; the lesson is that the speed of construction ran five to seven years ahead of demand, breaking the financing chain in between, and assets changed hands for a few cents on the dollar. This is precisely what we need to focus on today: long-term positivity resides in the computing power assets themselves, not necessarily in every company currently holding assets.
Ken Griffin from Citadel mentioned in October that AI is "almost certainly a bubble," to which Michael Burry responded on X, "This is obvious for anyone with a normal brain cell." But few people turned what Griffin said in the first part of his statement: GPUs are like airline seats, with extremely low marginal costs, "once oversupply occurs, prices will free-fall." Note that he is talking about GPUs, which is the price of computing power, not the prices of electricity, land, or data centers. Furthermore, he just acquired a whole bombed-out AI position at a discount back in July—buying the bottom first, then shouting bubble.
Supply is stuck while demand remains unchanged, leading to only one result: the value of existing capacity rises. But we need to clarify what is rising. What’s rising are physical items: electricity meters, data centers, and memory—CBRE data shows that rents for data centers over 10 MW in the first half of 2026 rose by 6.7% year-on-year, and the "free termination rights" of ultra-large tenants are disappearing from contracts; LevelTen data shows that North American wind power purchase agreement prices increased by 17.5% year-on-year. What is not rising is the computing power itself—hourly rental prices for GPUs have been steadily declining since 2025; Griffin’s "free-fall" refers specifically to this. The price of computing power is determined by Nvidia's product cycles, while the prices of electricity and data centers are dictated by ballots and approvals.
Anthropic’s S-1 provides a direct piece of evidence: their Q3 revenue was $17 billion, yet it transformed from an operating profit of $970 million in Q2 to an operating loss of $567 million, due to the fact that short-term computing power costs "are currently significantly higher." Even Anthropic is paying a premium for spot computing power. This is the rise in the value of existing capacity, happening in the IPO prospectus.
Looking at Nvidia, it has the lowest forward P/E ratio in five years, below the S&P 500's 18.7 times. The CFO mentioned in August that revenue growth for fiscal year 2028 would be around 70%, and analyst expectations for earnings per share in FY2028 are about $15.8, double that of the last 12 months. Revenue of $96.2 billion in Q2, and guidance of $108 billion in Q3, does not include any data center chips from China. If you sell Nvidia today, you are selling something ten times cheaper than Cisco in 2000.
But we must acknowledge the cost: ballots are cutting construction speed while Nvidia is selling speed. If the newly added capacity in the U.S. is truly cut by 30% starting in 2028, Nvidia's long-term growth rate will need to be revised lower, not just the P/E ratio. Long-term positivity relies on computing power assets, which may not directly correlate to the sellers of computing power.
Plain interpretation
A bubble is when houses are built but no one lives in them. Today, it's that houses are not enough, and the government says new developments should have approvals slowed down. House prices may fall in the short term because "developers are making money slower," but the houses that are already built become more valuable. The stocks of developers and landlords are both being sold together today.
An example
Today, the Nasdaq fell by 5.5%, while on the same day, the Hong Kong Hang Seng Index rose 3.67%, the Hang Seng Tech Index rose by 5.5%, and SMIC rose over 5%. However, Korea's KOSPI fell by 5.3%, with Samsung and SK Hynix each dropping more than 7%. The direction of capital is very clear: U.S. new capacity and global memory giants have fallen together while China's alternative supplies have risen. Money has not left AI; it is just changing seats within AI.
Don't rush to bottom fish: the two pumps are lined up in mid-November, along with a recently blown position
Being bullish in the long term does not mean you should bottom fish tomorrow. Those who bottom fish tomorrow are likely to be shaken out by mid-November.
The first pump: volatility. The VIX rose nearly 70% in one day, which means one type of capital has to sell mechanically—volatility-target funds that adjust their positions based on realized volatility over the past 1 to 3 months; when volatility jumps, leverage goes down. These funds will complete their reduction in one or two weeks: in August 2024, Nomura estimated that volatility-related funds sold $83.6 billion in U.S. stock futures in just two weeks. However, they will only return once today’s date rolls out of the 1 to 3 months volatility window. Therefore, in the next few weeks, the market is lacking buyers, while sellers will complete their sell-off in a week or two.
What’s more troublesome is muscle memory. The Nasdaq 100 has entered correction territory three times this year; the previous two times saw new highs in about two months. Nvidia has had four retracements of over 20% since 2023, with the first three bouncing back to new highs within six months. The "buy on dips" strategy worked in two instances this year, but today, for the first time, it failed—today, the Nasdaq Composite fell below the 200-day moving average, which is the trigger line for trend-following strategies (CTAs) to cut back. In the past four instances, those buying the dip were rewarded, so this time the scale of mechanical reduction will be larger.
The second pump: Anthropic. Anthropic publicly submitted its S-1 on October 26, and updated financial data on November 2: Q3 revenue was $17 billion, with a quarter-over-quarter growth rate slowing from 144% in Q2 to 47%; they committed to future expenditures exceeding $895 billion. According to reports from the Wall Street Journal and others, they may begin trading as early as the week of November 16, with a valuation range of $1.5 to $2 trillion, potentially raising over $100 billion.
A $100 billion IPO means that institutions need to free up cash on the scale of $100 billion from their existing holdings. A recent precedent occurred in June during the SpaceX IPO: BNP Paribas estimated that retail and passive funds sold approximately $50 billion of other stocks to buy SpaceX, while the Nasdaq fell by 4.18% during that week, and $1.3 billion flowed out from QQQ—of course, that week also included Broadcom’s guidance and employment data, with SpaceX merely acting as an amplifier. This money will not suddenly appear; it will come out of your current holdings in Nvidia, Microsoft, and Broadcom.
The mechanism has another half: since March, the Nasdaq changed its rules, allowing new stocks in the top 40 by market value to be included in the Nasdaq 100 within 15 trading days after their debut, the SpaceX event resulted in approximately $22-27 billion in passive buying. If Anthropic is subject to the same rule, it implies a pumping period before listing and a reinvestment period afterward. This pumping period is about four to six weeks from the roadshow to inclusion. This time scale aptly defines how short "short-term bearish" is.
(Interest disclosure: The author holds an exposure to Anthropic through an SPV; Anthropic’s Claude utility was used as an aid during the writing of this piece.)
Next comes that strong liquidation record. Let’s talk about the verified parts first. Leopold Aschenbrenner, 24 years old, a former researcher at OpenAI, wrote a 165-page document titled "Situational Awareness" predicting AGI in 2024, then started a hedge fund under the same name. By the end of June 2026, the fund had a net return of 439%, growing to $45 billion, with a 4x leverage—The New York Times mentioned that his team even requested 10x leverage from banks. They were long on AI infrastructure (SK Hynix, Micron, CoreWeave, Sandisk) and short on software (Adobe). In July, both sides reversed positions, adding margins, and by July 30, the entire position was sold at a discount to Ken Griffin’s Citadel, with its scale dropping to $10 billion, suffering a loss of 67% in a month. FT described it as the largest dollar loss in hedge fund history. The SEC then issued subpoenas to Goldman Sachs, JPMorgan, Citibank, and Bank of America, investigating their transactions with the fund.
On September 11, CNBC reported that he was back, reestablishing long positions in AMD, Bloom Energy, and CoreWeave in the options market. Jim Cramer tweeted five words: he’s back, bigger than before. Three days later, Protos reported that his new position was already in the red.
Now, for the parts that have not been verified today. At 5:28 PM Eastern Time, the prediction market platform Kalshi tweeted: Aschenbrenner’s fund "is rumored to have blown up," with 230,000 views. Several tracking accounts subsequently listed what were said to be liquidated positions. As of this writing, no mainstream financial media has confirmed this, and the fund itself has not responded. A tracking account tweeted only one sentence: "Leopold, please pick up the phone." Another account's comment was more insightful than all the analyses: "A hedge fund that doesn’t know how to hedge."
I include this section because it is about structure, not authenticity. A trader named Prof posted two numbers on X: on the day of that July liquidation, SPY was around $734; today, SPY is about $735. In three months, the index has not budged while the same person has been liquidated twice. What does this indicate? It indicates that internal fluctuations in AI trading have become large enough to liquidate 4x leveraged positions twice while the index remained unchanged. As long as there are still people using leveraged positions in crowded AI longs, every day like today will produce a batch of forced sellers— and forced sellers do not look at valuations.
Then comes an exam. On November 17, after market close, Nvidia will release its Q3 earnings report. Today's decline has already priced in "below expectations," but it hasn't priced in "meeting expectations, with conservative guidance." In a market that has breached the 200-day moving average, with VIX just rising 70%, "meeting expectations" is often not enough.
Plain interpretation
A class has had "down first, then up" for two consecutive tests; everyone has learned to "add positions when it drops." The third time drops deeper, and suddenly the homeroom teacher announces double the difficulty. The first to leave the classroom are those who have to go out according to school rules—and that student who borrowed four times the tuition to gamble.
An example
Back in February 2018, the VIX rose by 116% in a single day, which hasn't reached that level today. But after that, the S&P 500 fluctuated at the bottom for two months, taking seven months to reach a new high. Once the volatility is ignited, it will not extinguish in a day.
The last question: Who is selling chips to whom
Those selling AI stocks today are selling three things: Texas approvals, Alphabet's cash flows, and Qualcomm's memory bills. All three are real and short-term conditions will not improve.
But there are also three things that they did not sell, and they are firmer: CBRE’s 1.4% vacancy rate, PJM capacity prices are capped for two consecutive years, and Micron can only meet half to two-thirds of the HBM demand. The first three address policies and cycles, while the latter three are physical.
Policies will change, interest rates will fall, approvals will sooner or later be granted. But once demand has been validated, it will not revert to its previous state before validation.
Returning to that key sentence in the second section: the three locks restrict the pace of construction, and none touch demand. The speed belongs to the builders, while demand belongs to existing assets. Today the market sold both together. Every time the bottleneck of AI shifts position, the beneficiaries change hands—In 2023, the bottleneck is GPUs, with Nvidia as the winner; in 2025, the bottleneck will be memory and electricity, with Micron and data centers with power as the winners; by November 2026, the bottleneck will become ballots. Ballots do not sell, do not raise prices, and do not expand production—they will only make what has already been built more valuable.
Ken Griffin bought an entire bombed-out AI position at a discount from a forced seller back in July and stood on stage in October to declare that AI is almost certainly a bubble. These two things are not in conflict. He bought the chips and spoke about prices.
From this round of decline, I only read one thing: today’s question is not "Is AI going to end?" but "Who has sold the chips of existing capacity to whom in these weeks?"
The people who sold on that day in March 2020 took three years to dare to admit that they sold wrong. Today, it won’t take three years; when Nvidia’s earnings report comes out on November 17, you will know whether the bill you sold today was for AI or for the actual service.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


