This article is jointly produced by PANews and BIT U.S. Stocks. BIT U.S. Stocks offers over 10,000 mainboard U.S. stocks and ETFs, supports deposits and withdrawals in stablecoins as well as traditional U.S. dollar wire transfers, and provides full shareholder rights and dividend voting rights.
The impact of the dual negative factors of the bill and interest rate hikes is limited, with BTC's next test turning to 78,500 and September 25.
This week Bitcoin was first pressured by legislative news and then impacted by the interest rate decision, yet it never broke below Tuesday's low. The price retreated from around the opening near $79,600, briefly falling below $75,000 after the procedural vote failure of the CLARITY bill, and volatility increased on the FOMC decision day, with a true exploration happening after Powell's remarks, consolidating around $77,500.
Most traders consider the low near $75,000 on Tuesday as a reference bottom for this round of correction. There is noticeable buying pressure around the $75,500 line, and multiple voices mentioned that this level has been temporarily maintained, indicating active buying. The range from $77,300 to $78,500 has turned from support to resistance, with the key area of $78,200 to $78,600 repeatedly emphasized as a critical region to reclaim; if it cannot effectively hold, it may retest the current low or even decline further. Some traders see support around $73,500 to $74,500, as well as the cost basis for short-term holders near $70,000 to $71,300, believing that touching these positions still constitutes a healthy correction. The lower range of $68,000 to $70,000 is viewed as a warning line where the structure might further weaken.
The next highlight is the quarterly options expiration on September 25, which, according to statistics, carries approximately 43% of Bitcoin's open interest, more than double the size at the end of August. The maximum pain point falls around $72,000, with a clear wall of call options at $85,000 above. As the expiration date approaches, market makers' hedging operations may cause prices to fluctuate repeatedly around key points, and after the expiration is completed, the market may face a true directional choice. The funding situation has not completely turned: CryptoQuant's long position score fell from 80 to 60, remaining neutral yet slightly above, and the fear and greed index stands at 69 in the "greed" range, indicating that the cleaning of chips is not thorough. Glassnode points out that over the past three months, publicly traded companies have only added about 5,900 Bitcoins to their treasury, far below the same period last year, with an average corporate purchase price around $80,500, and the current price still slightly below this level, indicating overall weak new demand.
BIT Asset Management head Daniel Yu believes that the core of this meeting is not "interest rate hikes" itself, but rather the "duration shock"—the dot plot raised the median interest rate for 2027 from 3.6% to 4.1%, which extends the high-rate environment by a year. This clashes with the previous narrative of Bitcoin being an anti-devaluation asset. If oil prices continue to fall back below $100, the certainty of "one more hike" in the dot plot may decrease; conversely, if the 10-year U.S. Treasury yield rises back above 5%, Bitcoin's support may need to shift lower. Next week’s macro calendar is relatively empty, with the September 25 options expiration becoming a key variable driving volatility; the pin effect and the scale of hedging being released far exceed that of the end of August.
Today's Highlights:
Binance will delist four USDC spot trading pairs: BREV, COOKIE, LA, QNT on September 18
LayeZero (ZRO) unlocks about 25.72 million tokens, worth about $27.51 million
Lista DAO (LISTA) unlocks about 33.44 million tokens, worth about $2.6 million
Bedrock (BR) unlocks about 40.63 million tokens, worth about $10.4 million
Upbit 24-hour trading volume rankings: XRP, BTC, ETH, FOLD, NEAR
Bitcoin spot ETF: +$159 million
Ethereum spot ETF: -$39.2445 million, continuing three days of net outflow
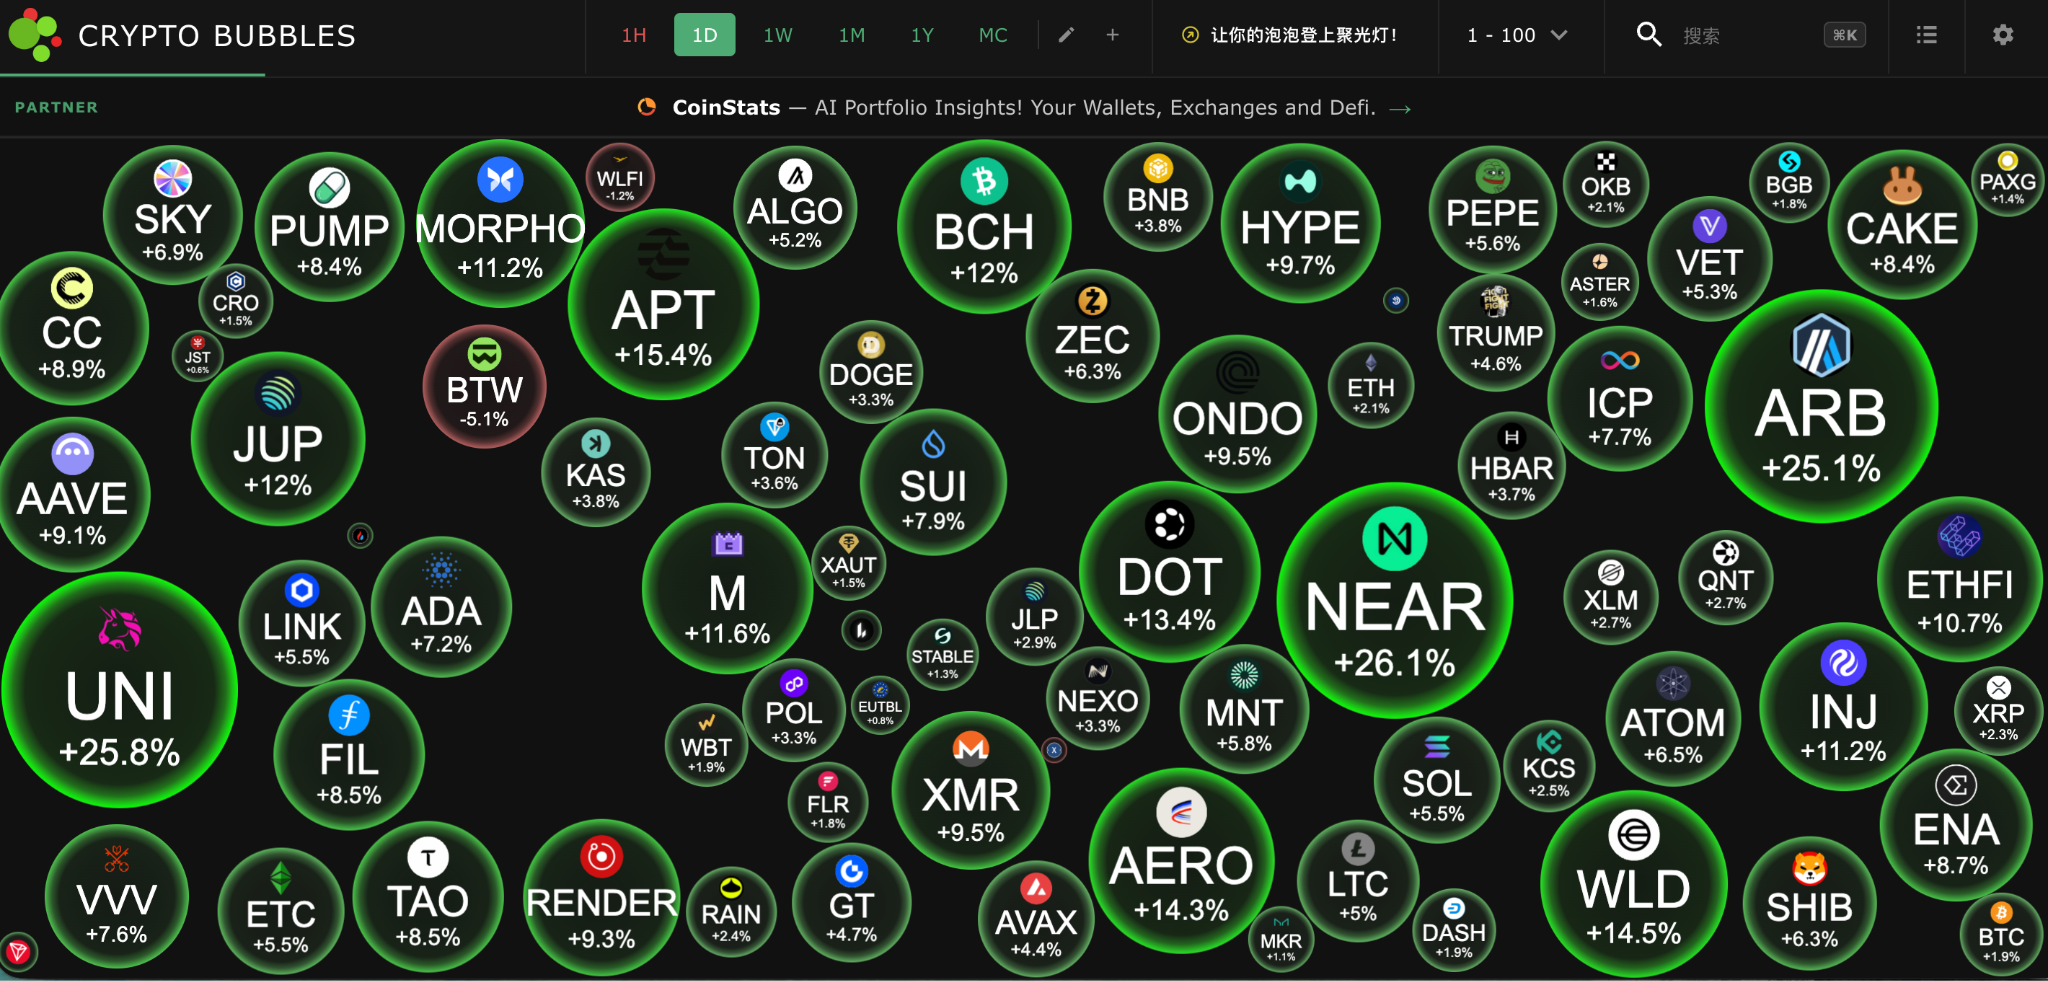
Today's top gainers among the top 100 cryptocurrencies by market capitalization: NEAR up 26.1%, UNI up 25.8%, ARB up 25.1%, APT up 15.4%, WLD up 14.5%.
The night session continues to be bullish, and "Triple Witching Day" makes chasing gains risky
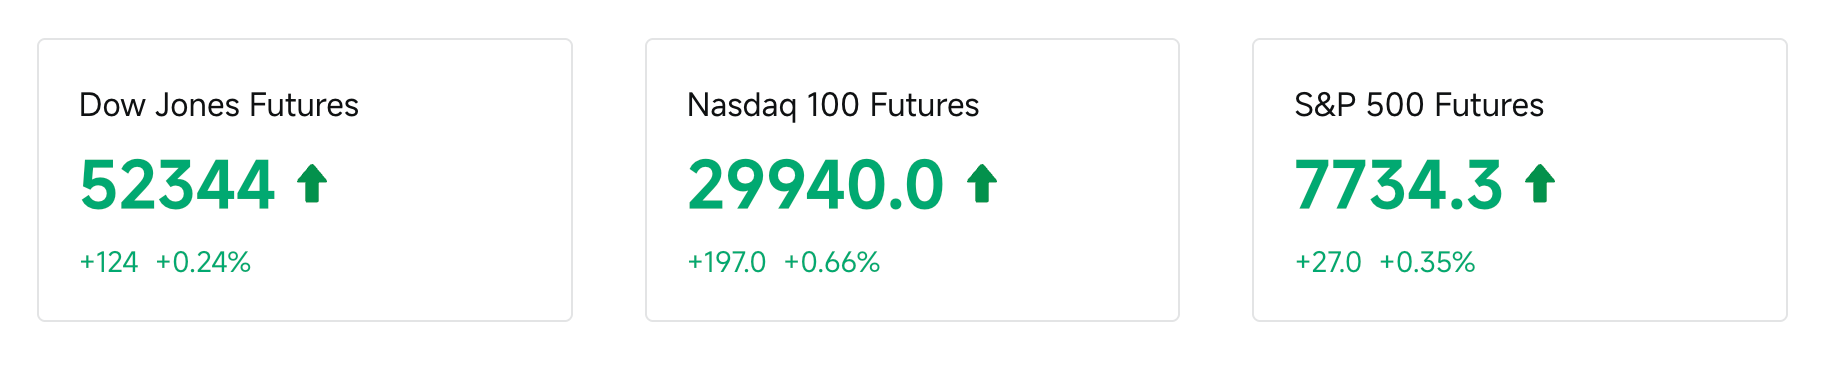
The three major U.S. stock index futures were generally strong overnight, with market sentiment shifting from caution after the interest rate hike to recovery, with Dow futures up 0.24%, Nasdaq 100 futures up 0.66%, and S&P 500 futures up 0.35%.
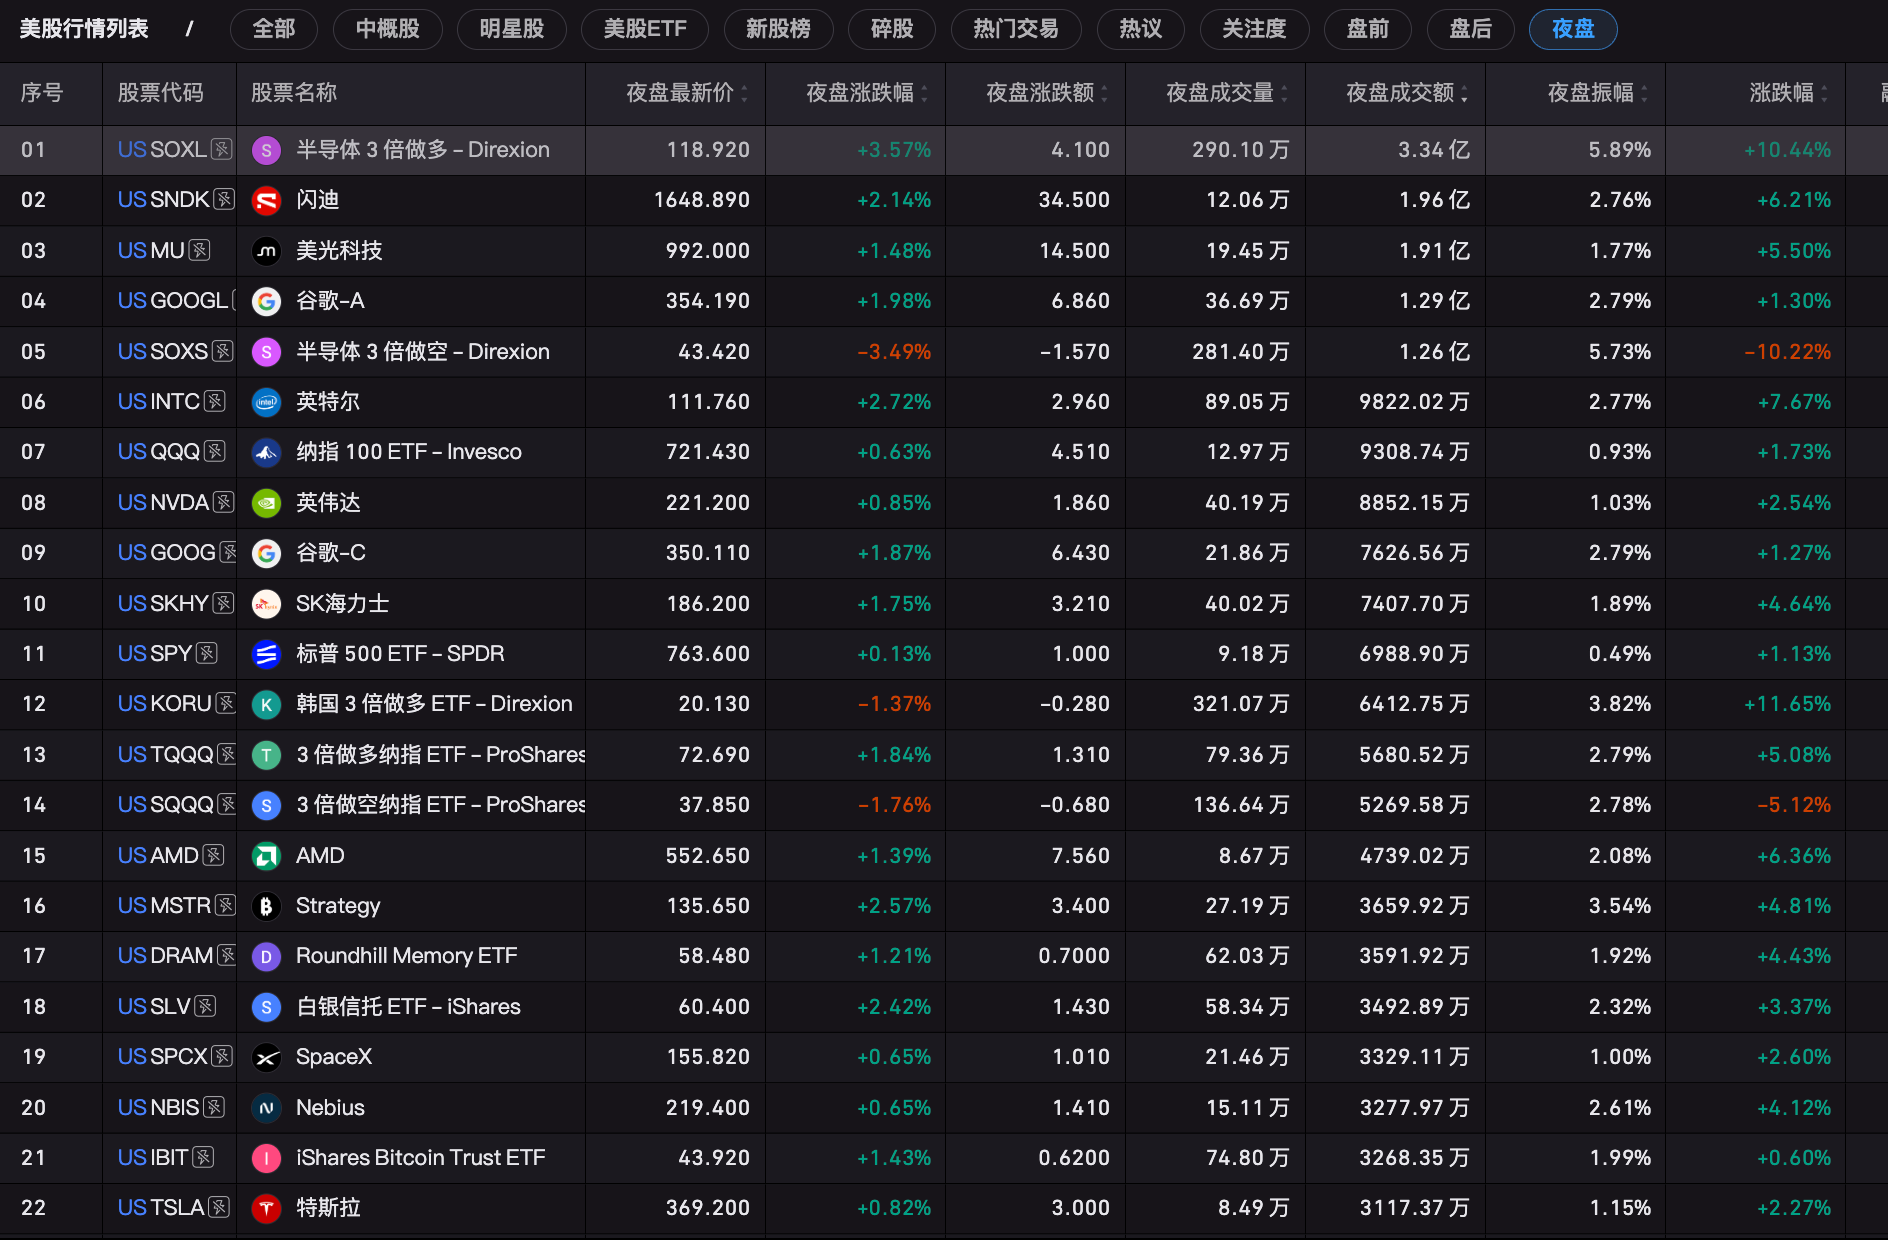
BIT night session data indicates that the tech and semiconductor sectors continued to rise during the night session, with SOXL up 3.57%, Intel up 2.72%, Micron up 1.48%, AMD up 1.39%, and Nvidia up 0.85%. Cryptocurrency-related assets were also active, with Strategy up 2.57% and iShares Bitcoin Trust ETF up 1.43%. Silver Trust ETF rose 2.42%, and Tesla and Google also saw varying degrees of increase.
However, investors need to be cautious of tonight's "Triple Witching Day" effect. This is the day when stock index futures, stock index options, and individual stock options all expire simultaneously, involving a massive settlement of over $2 trillion. Historical data shows that in the 14 instances of similar "Triple Witching Days" since 2012, the S&P 500 has closed down 12 times. Although the current market fundamentals are decent, the expiration of options may lead to increased volatility during the session; if the S&P 500 index drops below a key support level, it could trigger panic selling by investors.
Oil prices retreat, AI shorts squeeze, SEC's new policy "ignites" crypto markets, mining companies repair simultaneously
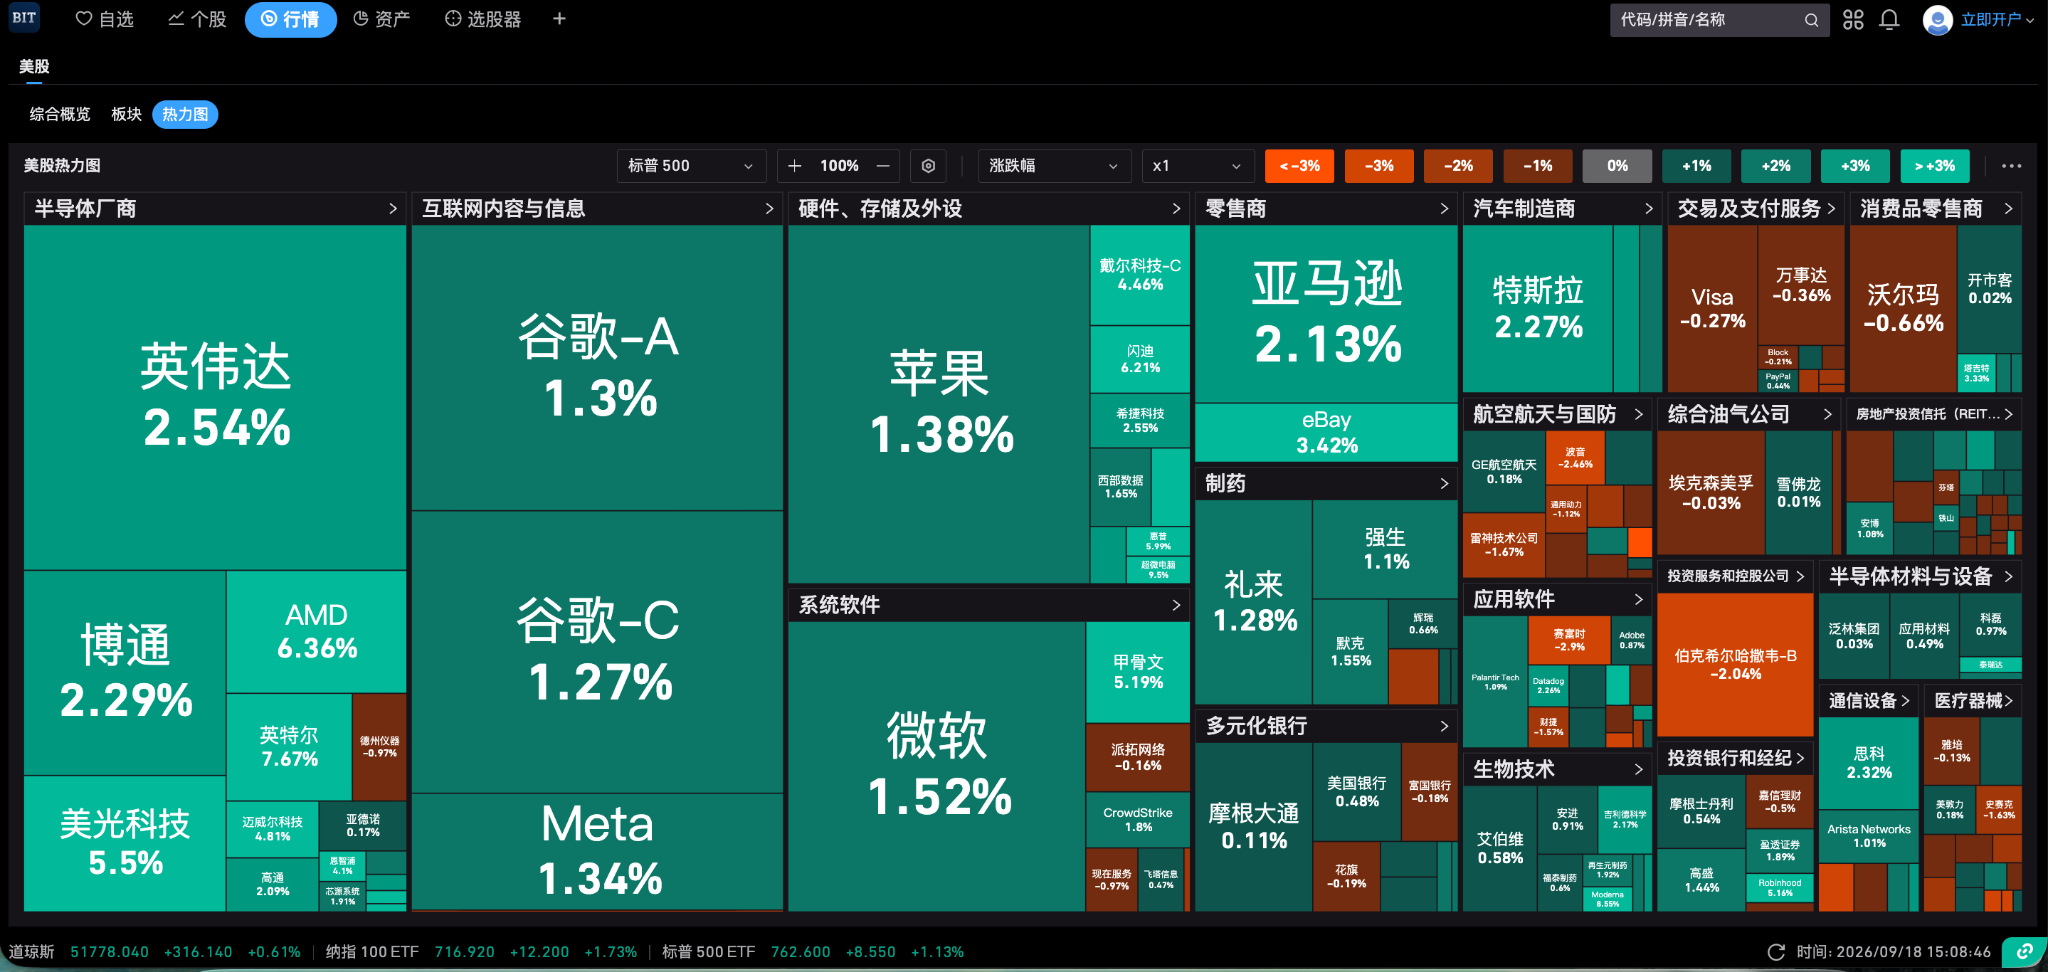
Last night, U.S. stocks ended a three-day losing streak, with the market adjusting its mentality from panic over the Fed's interest rate hikes. The Dow rose 0.62%, the S&P 500 rose 1.14% to 7,637 points, and the Nasdaq rose 1.69%. The core driving force came from oil prices falling for two consecutive days and U.S. Treasury yields retreating from above 5% to about 4.93%, ending a nine-day rise.
The AI and chip sectors became the core of the rebound, with Jensen Huang stating at an event in Scotland that Nvidia's chip sales are expected to double next year compared to this year, citing supply rather than demand as the bottleneck, directly igniting the hardware narrative. The Philadelphia Semiconductor Index surged over 3%, with Nvidia up 2.54%, Intel up 7.67%, AMD up 6.36%, and Micron up 5.50%. Power equipment and cloud computing also strengthened, with Generac surging more than 18% after signing a maximum $8 billion backup generator agreement with Amazon. Goldman Sachs' trading desk activity score is only 4/10, and Castle Securities strategist Scott Rubner believes this is more about short covering and position repair; September may still be bumpy, but the AI sector is expected to stabilize first in October.
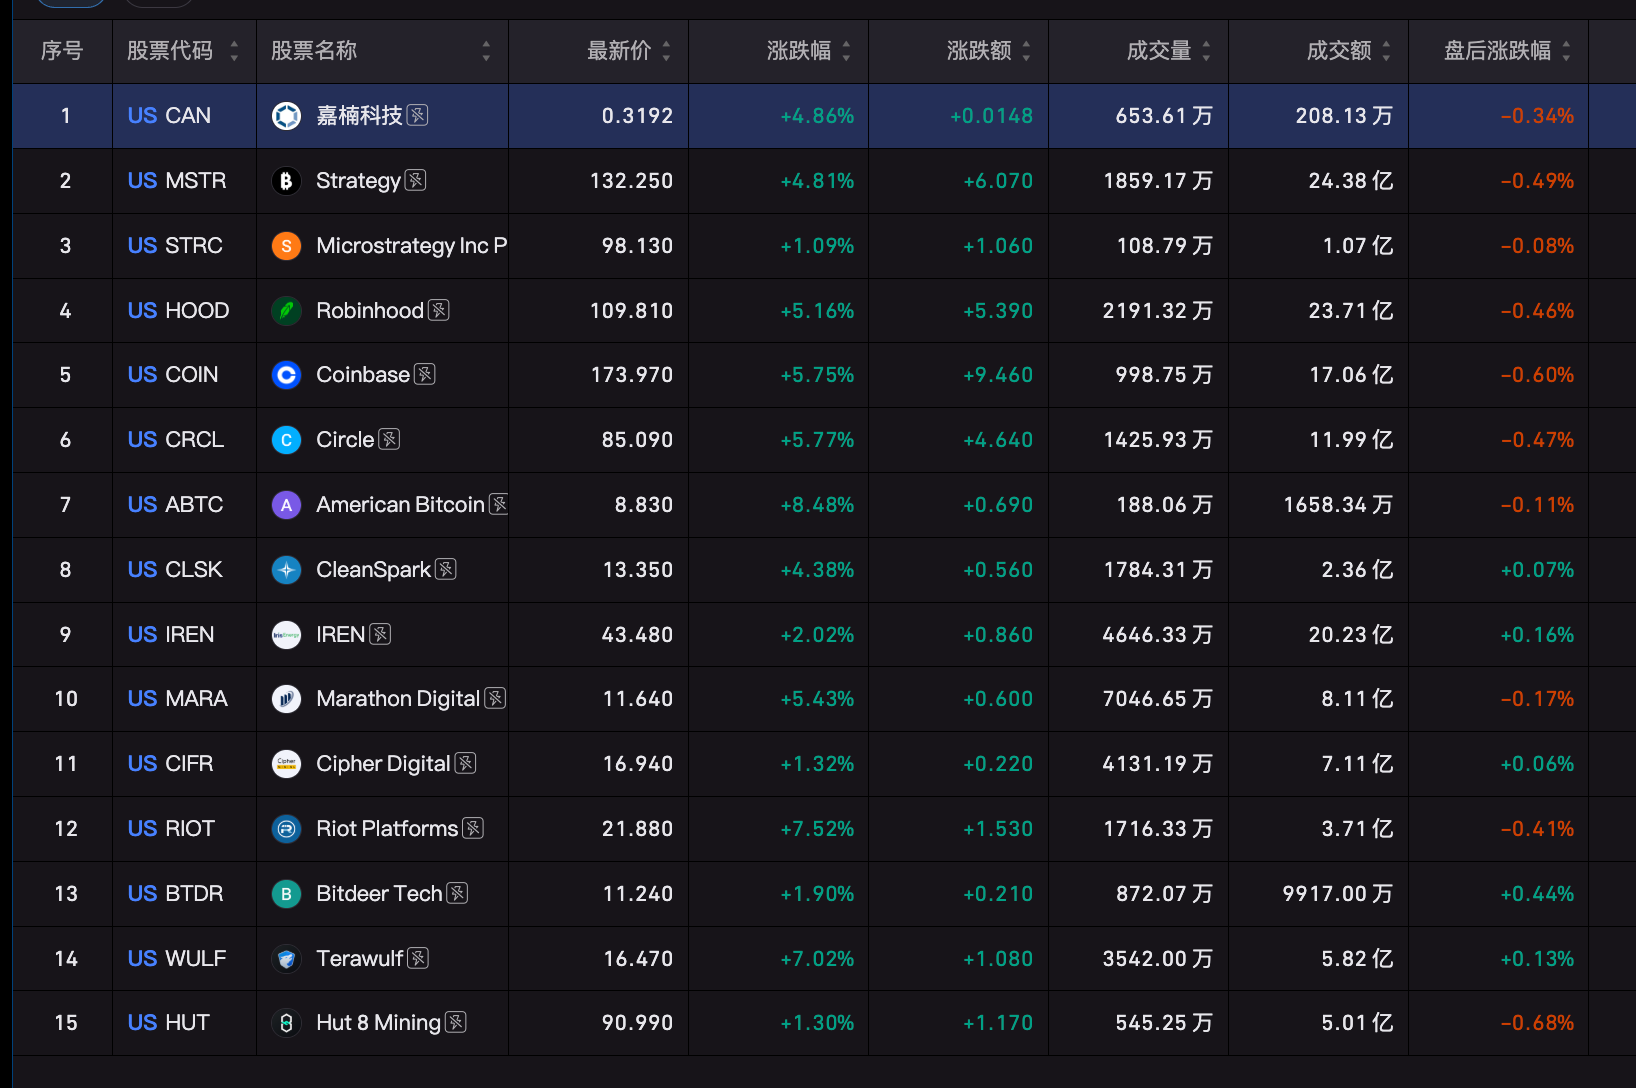
Overnight, cryptocurrency-related stocks nearly all rose, with data from BIT U.S. Stocks showing Robinhood up 5.16%, Coinbase up 5.75%, Circle up 5.77%, and Strategy up 4.81%. Mining companies performed even stronger, with Riot Platforms up 7.52%, Terawulf up 7.02%, Marathon Digital up 5.43%, CleanSpark up 4.38%, and American Bitcoin up 8.48%.
On the regulatory front, the SEC has provided a five-year exemption for tokenized stock trading, directly benefiting trading platforms and on-chain financial infrastructure. The market views this as a test window for traditional securities going on-chain, coupled with Bitcoin stabilizing, leading to a resurgence of capital back into cryptocurrency-related assets.
Japan's rate hike is not hawkish, while South Korea's semiconductors lead the way
The Bank of Japan raised interest rates by 25 basis points to 1.25%, the highest level since 1995, and this is the sixth rate hike since exiting negative interest rates in March 2024. The decision passed with a vote of 7 to 2, with two members opposing, and the statement did not release any clear hawkish signal. Governor Kazuo Ueda emphasized that there is no preset pace for rate hikes; decisions will be made progressively based on economic and price conditions. As a result, the market interprets the two opposing votes and the lack of a clear guide for accelerated rate hikes as the BoJ will continue to cautiously move toward normalization.
The yen weakened in the short term, with USD/JPY rising 1.15% to about 157.8, and the Nikkei 225 index closed up 1.38%. The semiconductor and technology sectors performed the brightest: storage chip giant Kioxia's shares surged 9.40%; semiconductor equipment giant Tokyo Electron rose 4.20%; SoftBank rose over 1% and increased margin loans backed by Arm shares to $25 billion, further strengthening its investment in AI.
The South Korean KOSPI index closed up 2.68%, showing even stronger performance. The semiconductor sector led, with SK Hynix up 6.41% and Samsung Electronics up 3.36%. South Korean media reports indicate that the delivery cycle for key semiconductor equipment components has generally lengthened by more than double; some Japanese components have a waiting time of up to 40 months, and supply chain bottlenecks may delay expansion projects for Samsung's Pyeongtaek and SK Hynix's Yongin. Nevertheless, the AI demand boom continues to support chip stock sentiment, and the market interprets this as a coexistence of short-term supply tightness and long-term capital expenditure narratives.
Today, the three major Hong Kong stock indices collectively closed up, with the Hang Seng Tech Index performing the strongest, soaring 2.2%, while the Hang Seng Index and the State-owned Enterprises Index rose 0.6% and 0.61%, respectively. Semiconductor and AI concept stocks became the core engine of the market: AI large model company MiniMax-W surged nearly 19%, AI chip giant AI Chip Tech rose 16.6%, Tianxu Intelligent Chip rose 11.95%, and Smart Software rose 5.4%; in the semiconductor sector, Huagong Semiconductor, GigaDevice, Inspur Technology, and SMIC all performed strongly. Moreover, AI hardware leader Lenovo Group surged 9.5%, reaching a new high for the stage.
A-shares also fully recovered, with the Shanghai Composite Index rising 0.94%, the Shenzhen Component Index rising 1.72%, the ChiNext Index rising 2.25%, and the Science and Technology Innovation Index rising over 3%, with over 4,200 stocks advancing. Semiconductors, GPUs, storage chips, communication equipment, and computer hardware led the gains, while real estate also strengthened in the afternoon; coal, automobiles, oil and gas, and banks lagged relatively.
Next, we need to focus on:
September 18 (Friday)
U.S. stocks Triple Witching Day: Stock index futures, stock index options, and individual stock options expire simultaneously, making trading volume and end-of-session volatility typically magnified. This time follows the Fed and BoJ decisions closely, increasing volatility risk.
Deadline for Hang Seng Tech Index expansion and restructuring consultation: Expanding to 50 stocks and introducing high-growth factors, which may impact passive funding expectations for Hong Kong tech stocks, with AI, software, and high-growth tech targets being the most focused.
iPhone 18 Pro launch: Will test demand for Apple's new products, influencing sentiment across Apple's supply chain, consumer electronics, storage, optics, and semiconductors.
Huawei Global Connect Conference from September 17 to 19: Market attention on Ascend 950 super node, new AI computing power products and industrial partner plans. Domestic computing power, servers, optical modules, liquid cooling, and data center chains may gain catalysts.
Semicon India from September 17 to 19: Global semiconductor and policy leaders will attend, with markets focusing on India's semiconductor manufacturing, testing, and supply chain policies, which may influence global chip industry chain layout expectations.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


