Author: WuBlockchain
Translator: ShenChao TechFlow
ShenChao Introduction: This article reveals a structural risk that is generally underestimated in the market: the "risk-free asset" premium of U.S. Treasuries is quietly disappearing, and this signal has already been written into the yield curve itself. For investors holding dollar-denominated assets, this is not an ordinary interest rate cycle fluctuation but a reshuffling that concerns the global asset pricing anchors.
Measured by the simplest metric—the yield on ten-year Treasury bonds minus the federal funds rate—this anchor point of the global financial system in the U.S. now has financing costs relative to Germany in the same range. However, the complete shape of the yield curve reveals that the market's premium paid for the U.S. is highest not at the ten-year point but at the twenty-year point. This is not an ordinary cyclical event, but a sovereign credit re-rating embedded in the yield curve itself.
On July 27, 2026, the yield on ten-year U.S. Treasuries closed at 4.65%, with an effective federal funds rate (EFFR) of 3.63%, a spread of about 102 basis points. Viewed in isolation, this is less than one-third of the peak seen in the 1994 "bond vigilantes." But if we expand our view from a single node to the entire curve, the global cross-section, and the probability distribution implied by the option market, a more complete and alarming picture emerges: it is not a single term that is damaged, but an era—the era in which U.S. Treasuries enjoyed negative term premium subsidies as a global risk-free asset.
1. Curve Above Policy Rate at Every Node
By taking the U.S. Treasury curve on July 27, 2026, and subtracting the EFFR, the first fact emerges: from one-month short-term debt to thirty-year long-term debt, every term is above the policy rate (Figure 1). One month is 17 basis points higher, one year is 51 basis points higher, two years are 68 basis points higher, ten years are 102 basis points higher—while the twenty-year point at +152 basis points is the highest on the entire curve, even exceeding thirty years (+149 basis points), leading to an inversion between 20s and 30s.
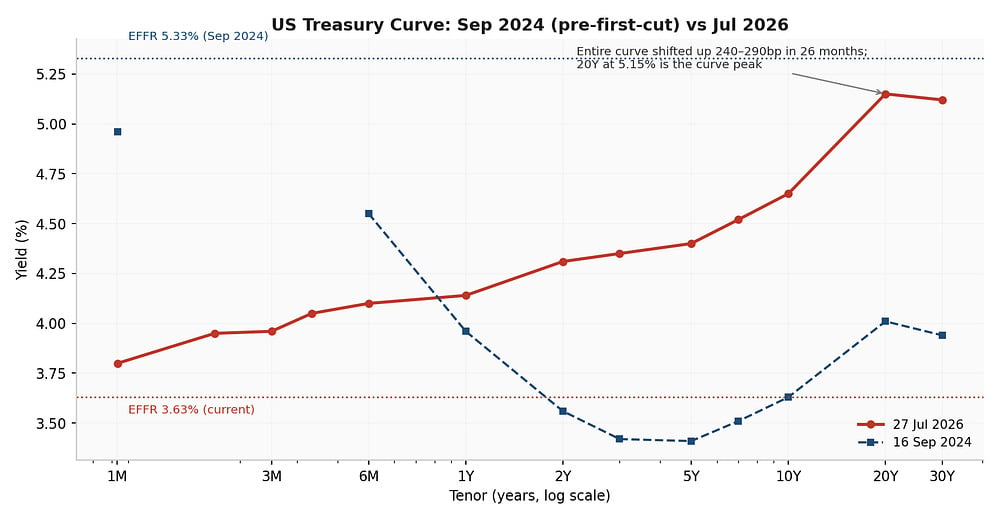
Figure: Comparison of U.S. Treasury Yield Curves—September 2024 (before first rate cut) versus July 2026, the entire curve has shifted up in parallel. Source: WuBlockchain
The slope distribution of each segment of the curve is more informative than any single spread. From two to five years, the movement is only 9 basis points over three years, nearly flat: the market has no expectation of a return to the old interest rate regime. Five to ten years increased by 25 basis points; ten to twenty years jumped by 50 basis points. There is no pricing for the "policy rate of the fifteenth year"; this segment is almost purely term premium and duration supply premium. The point where the market pays the highest marginal price for U.S. duration is precisely at the twenty-year mark—where the demand from pension funds is weakest and the supply is purely for fiscal purposes.
The short end tells another story. One-year at +51 basis points and two-year at +68 basis points price in a hawkish path—no rate cuts for the coming year, and possibly even more rate hikes. This is the policy narrative of the 2026 Middle Eastern energy shock, rather than a credit narrative. Looking at the ten-year node alone would confuse these two elements.
Compared to historical cross-sections (Figure 2), three points stand out sharply.
First, during the periods of wide spreads in 2003, 2010, and 2013, the short end was below the policy rate—the market priced in rate cuts, representing a benign "recovery steepening." The vigilante event of 1993-1994 belongs to the same family as today: the short end is above the benchmark rate, while the long end has a larger premium.
Second, today’s ten-year yield of +102 basis points is only one-third to one-half of the peaks in October 1993 (+219 basis points) or November 1994 (+330 basis points); however, the pure duration premium (twenty-year minus two-year) has reached 84 basis points—about two-thirds of the vigilante peak (124 basis points)—while the federal debt to GDP ratio is around 120%, nearly double the 64% of 1993.
Third, from September 2024 (the entire curve below benchmark rates by 132 to 192 basis points) to today (above benchmark rates by 33 to 152 basis points), the entire curve has shifted up in parallel by 240 to 290 basis points in 26 months. When the ten-year yield hit 5% in October 2023, the curve was deeply inverted—this was a "contractionary pattern"; today we have a "term premium pattern." The two are completely different.
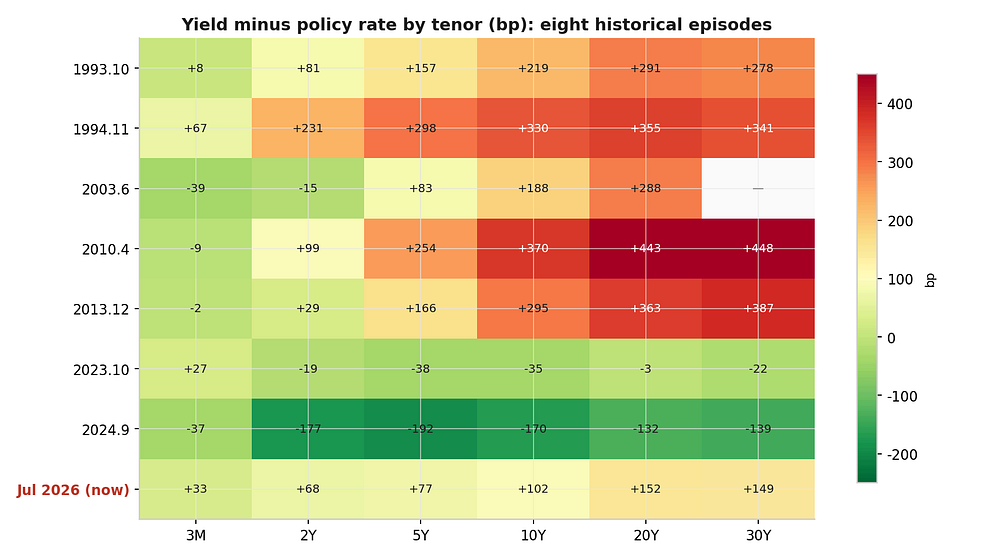
Figure: Yield of each term minus the policy rate (basis points), eight historical cross-sections; the deeper the red, the higher the premium the Treasury is charging. Source: WuBlockchain
The core conclusion: the damage is structural, not localized. Policy expectations can only explain the short end (two-year is 68 basis points above EFFR); the long end is purely term premium, centered at the twenty-year mark—this is where the market charges the most for U.S. securities. The pure duration premium is now equal to two-thirds of the vigilante peak in 1994. The parallel upward movement of the curve by 240 to 290 basis points in 26 months marks a significant re-pricing—cyclical steepening is rotational, while structural change is translational.
2. Global Rankings: On Par with Germany, Short End on Par with India
Applying the same metric to major economies (Figure 3), we arrive at a counterintuitive result: measured by "ten-year minus policy rate," the U.S. (+102 basis points) is almost on par with Germany (+88 basis points), better than the U.K. (+125 basis points), France (+167 basis points), Italy (+169 basis points), and Japan (+178 basis points). But 2026 is the year of global energy shocks: central banks of the European Union, Japan, Australia, South Korea, and New Zealand have all turned hawkish, leading to a simultaneous expansion of term premiums in the developed world. The U.S.'s mid-tier ranking is somewhat covered by the overcrowding in the entire ward.
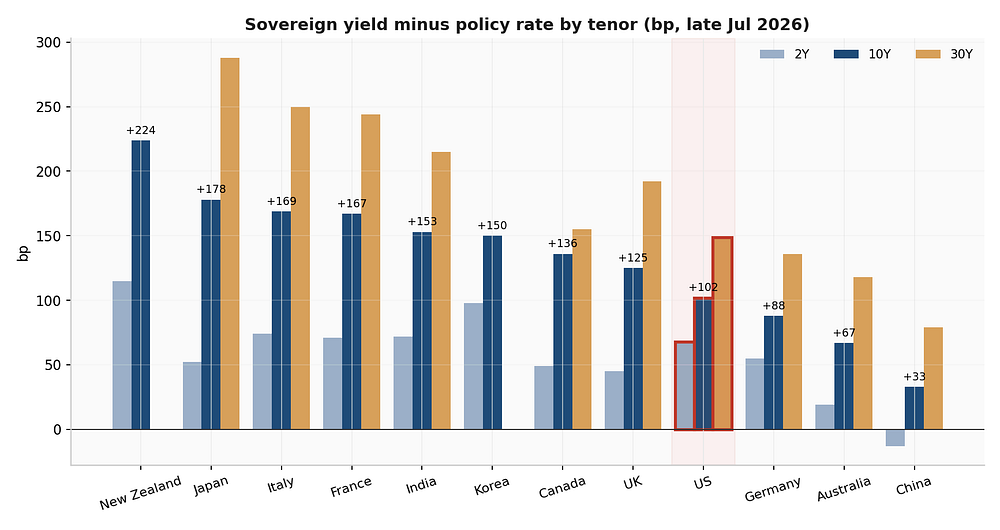
Figure: Rankings of term spreads by sovereign countries (ten-year minus policy rate), U.S. is on par with Germany. Source: WuBlockchain
Decomposing by curve segments, three details deserve attention.
First, on the short end (two-year minus policy rate), the U.S. (+68 basis points) is nearly matched with India (+72 basis points), Italy (+74 basis points), and France (+71 basis points)—an emerging market with a BBB rating whose short end is only 4 basis points more expensive than the issuer of the global reserve currency. Fairly speaking, this segment mainly reflects the common pricing of the tightening cycle in 2026, representing a policy narrative rather than a credit narrative; but this also means the credibility of the Federal Reserve no longer brings any discount to U.S. Treasuries on the short end.
Second, in the long end rankings (thirty-year minus policy rate), the U.S. remains on the "core credit" side, but only leads over the U.K. and India by one position. The complete ranking is: Japan (+288 basis points) > Italy (+250 basis points) > France (+244 basis points) > India (+215 basis points) > U.K. (+192 basis points) > U.S. (+149 basis points) ≈ Canada (+155 basis points) > Germany (+136 basis points) > Australia (+118 basis points) > China (+79 basis points).
Third, the damage to the U.S. is depicted by the entire curve being elevated rather than just the long end soaring alone: the 30Y to 10Y slope of the U.S. (+47 basis points) is nearly identical to Germany (+48 basis points) and Australia (+51 basis points), but starkly different from Japan (+110 basis points) or Italy (+81 basis points).
When we factor in the stock of debt, the picture becomes more operationally significant. Dividing the ten-year spread by the debt to GDP ratio gives us the market charge for each unit of debt (Figure 4): India about 2.6, France 1.45, Germany 1.40, U.K. and Italy about 1.25—while the U.S. is only 0.85, the lowest in the table aside from Japan (0.77), where the central bank itself is the final buyer. The market is still granting U.S. Treasuries a "reserve currency discount." If this discount regresses to the G10 median (around 1.25), the ten-year spread will widen to 150 to 170 basis points—about 50 basis points of "normalization" upsurge are still available without any crisis, only requiring the market to stop pricing for this privilege. Japan shows another endgame: routine bond purchases by the central bank have driven the spread down to 0.77—the price paid is currency depreciation and an expanding central bank balance sheet.
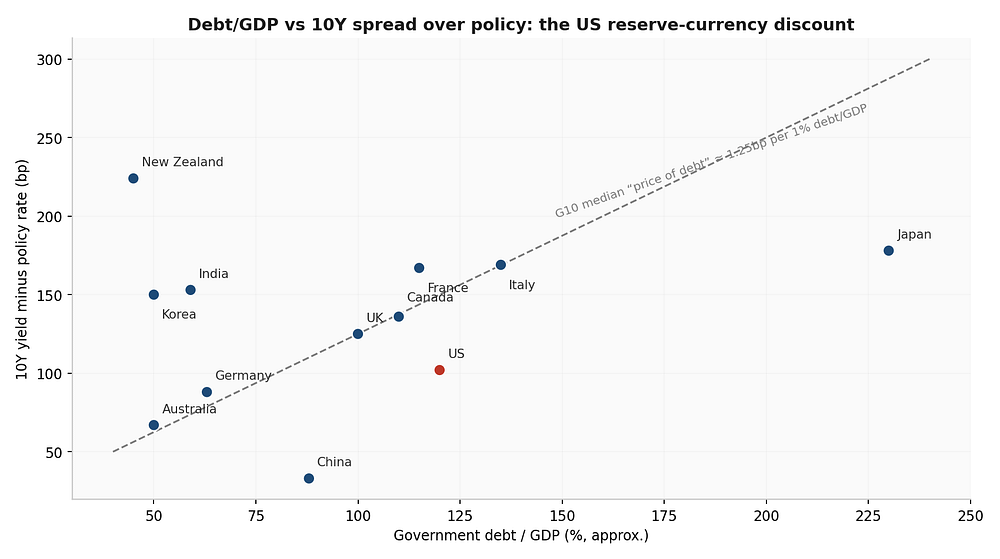
Figure: Relationship between government debt/GDP and ten-year spread, the U.S. "reserve currency discount" keeps it low. Source: WuBlockchain
The term premium model confirms the same conclusion. The ten-year term premium of the New York Fed's ACM model has risen to +0.72%, while the San Francisco Fed’s Christensen-Rudebusch model has risen to +1.25%—whereas the two-year premium is only +0.21%: the damage is precisely concentrated at the long end. The breakdown by the San Francisco Fed shows that, within the ten-year yield, the average expected value of future overnight rates over the next decade is only 3.47%, below the current EFFR—around 1.25 percentage points remaining is purely a duration premium: the elevated long end can no longer be explained by "market expectations of Fed tightening"; it is a straightforward sovereign credit and duration surcharge. Between 2016 and 2021, this premium was negative—the global shortage of safe assets provided a subsidy for U.S. Treasuries. The return of this subsidy is the essence of this re-rating.
The core conclusion: cross-sectionally, the U.S. is on par with Germany, in the circle of Canada and the U.K., with the short end aligned with India—but as the issuer of the global reserve currency, it should historically be systematically lower than this benchmark. Its "unit debt spread" is 0.85, the lowest in the table aside from Japan (0.77), which is supported by the central bank—reserve currency discounts still exist, but mean regression to the G10 median of 1.25 indicates approximately 50 basis points of "normalization" space in long-end yields, requiring no crisis, only the market stopping to price for this privilege.
3. The Two-Peak Pricing in the Options Market
The cash curve tells us how much has been priced in; the options market tells us what is still a concern. As of July 28, four markets are telling four different stories:
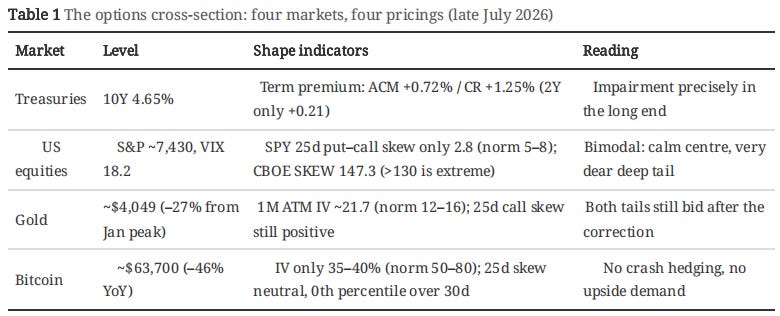
Figure: Table 1—Options Cross-Section: Four Markets, Four Pricing (End of July 2026). Source: WuBlockchain
These numbers internally show inconsistencies: interest rate options, the SKEW index, and gold volatility are all pricing in fiscal pressure, while the 25-delta equity skew and Bitcoin volatility are still pricing in a business-as-usual scenario. Put simply, the market is pricing in a bimodal distribution: a low-volatility inertial center, a tail of discontinuous fiscal events, and a blank space in the middle. Historically, this gap has almost always closed by equity volatility catching up to interest rate volatility—both October 2022 and October 2023 followed this script—and the flatness of the 25-delta skew suggests that equity downside protection is undervalued relative to the implied risks in the interest rate market.
The cross-asset implications are best interpreted by market.
U.S. Stocks: Three transmission channels. The discount rate channel compresses valuation multiples, with long-duration growth stocks being the most affected; the Kalecki profit channel—approximately 7% of the fiscal deficit to GDP ratio, which in accounting terms equates to private sector surplus and nominal corporate profits—supports nominal profits, creating a slowly grinding, structurally narrow index; the correlation channel keeps stock-bond correlations positive, stripping the diversification function of 60/40 portfolios and risk parity strategies, forcing volatility-target funds to deleverage synchronously as interest rate volatility spills over. Winners are companies with pricing power, energy stocks, and banks benefiting from steepening curves; losers are long-duration tech stocks, bond alternatives, and small-cap stocks reliant on floating-rate financing.
Commodities: Gold is the hedge against de-dollarization, oil prices are the short-end driver. In this round of events, gold is the market's chosen "hedge against de-dollarization"—after a 27% adjustment, its implied volatility remains anchored at 21 to 22, with the bullish skew intact, indicating that the structure of central bank purchases bolstering options market insurance has not changed; oil prices drive the hawkish short end, priced as "range-bound with upside skew."
Cryptocurrency: The harshest verdict of 2026. In the first true year of sovereign credit pressure, capital chose gold over Bitcoin. Bitcoin has been suppressed as a liquidity beta trade by high real interest rates throughout the year; the realization of its narrative as a hedge against currency depreciation requires a second phase—central banks being forced to monetize fiscal deficits—rather than the current first phase of hawkish short ends combined with rising term premiums.
The core conclusion: the options market is pricing in a bimodal distribution—interest rate options, SKEW, and gold volatility have already priced in fiscal pressure, while the 25-delta equity skew and Bitcoin volatility are still pricing in a business-as-usual scenario. Historically, this gap converges by equity volatility catching up to interest rate volatility—against a backdrop of calm centers and expensive tails, the downside convexity at the 25-delta is an undervalued window.
4. History Provides Four Outcomes
U.S. sovereign credibility has been damaged four times previously, and the outcome menu is fixed.
1933: Rewriting creditor terms. Roosevelt abolished the gold clause in government bonds, upheld by the Supreme Court in the Perry case—this was a technical precedent for rewriting creditor terms in the U.S.
1942 to 1951: Fiscal dominance, literally. The Federal Reserve directly anchored the curve for wartime needs (short debt at 3/8%, long debt at 2.5%); the outcome was an inflation tax (15 to 20%) from 1946 to 1948 and the restoration of Federal Reserve independence in the 1951 "Treasury-Fed Accord." This also serves as a template for "if independence is lost": yield curve control.
1971 to 1981: The closest analogy to today. Nixon pressured Burns, and the central bank's credibility was lost, as the long end refused to follow downward during the loosening cycle from 1975 to 1977—completely in line with today’s curve shape. The outcome was the 1978 dollar crisis, forcing the Treasury to issue "Carter bonds" denominated in German marks and Swiss francs, and Volcker pushing interest rates to 20% to restore credibility.
1992 to 1994: The template for a good outcome. The bond vigilantes stifled Clinton's stimulus plan, forcing the passage of the 1993 Deficit Reduction Act and a return in 1998 to 2001 of fiscal surpluses and spread convergence as a reward.
The only pattern is: the outcome will either be fiscal consolidation (1950s, 1990s), or inflation and monetary subordination (1940s, 1970s), or an external disciplinary event (Volcker). There has never been a default in history. And after each repair, the dollar system has become more entrenched. Thus, "deep damage" is not predestined—but in the political ecology of 2026, there are neither Volcker nor Clinton, which is precisely why the options market prices deep tail risks so expensively.
The core conclusion:
The menu of outcomes has only three dishes: fiscal consolidation (1950s, 1990s), inflation and monetary subordination (1940s, 1970s), or external disciplinary events (Volcker). There has never been a default in history—each repair has made the dollar system stronger. Damage is not fate; but in the political ecology of 2026, there are neither Volcker nor Clinton, which is why the deep tail is so expensive.
5. Trump: An Accelerator, Not a Starting Point
It is not valid to completely blame this round of re-pricing on the Trump administration; on the timeline, the bear market steepening divergence between the ten-year Treasury yield and the federal funds rate began in September 2024—before Trump took office. The full attribution can be divided into three layers.
The foundation was jointly laid by both parties (2008—2021): crisis response, tax cuts under full employment in 2017, two rounds of COVID stimulus, and QE driving term premiums to negative values—this subsidy led two generations of Congress members to mistakenly believe that deficits were free.
The trigger was pulled from 2022 to 2024: inflation exploded, activating the arithmetic logic of "r greater than g," quantitative tightening removed marginal buyers of duration, and the freezing of Russian reserves in February 2022 sparked global reserve diversification, with Fitch (August 2023) and Moody's (May 2025) stripping the U.S. of its top rating successively.
Trump 2.0 is the accelerator, pushing through three channels: about a 7% GDP deficit in a full employment state, unprecedented in peacetime; publicly pressuring the Federal Reserve and manipulating appointments, eroding the "independence premium"; tariffs and immigration restrictions prolonging inflation persistence, keeping short-term rates firmly nailed to a hawkish position.
In other words, Trump was neither the direct cause nor irrelevant—his most accurate positioning is as a symptom and amplifier of the fiscal balance post-2008 (voters rewarding deficits, bipartisan collusion). Even successors from fiscal conservatives can only slow down this trajectory but cannot reverse it: with debt to GDP at 120% and the situation of r above g, primary fiscal surplus is needed, yet no candidates in 2024 have this as part of their campaign platform.
The core conclusion:
"Blaming Trump" does not hold on the timeline—the steepening divergence of the bear market began in September 2024, at which point he had not yet been inaugurated; "not relating to Trump" also does not hold marginally—in a state of full employment with a deficit of about 7% and the discounted Federal Reserve independence premium, both are significant new variables. The debt baseline was built by both parties (2008—2021), the trigger was pulled from 2022 to 2024, and Trump 2.0 is an accelerator—also a symptom of the same fiscal balance.
6. Emerging Markets and "Neutral" Strategies: Two Forms of the Same Storm
For emerging markets, the shocks arrive in bifurcated forms—in the very week this article is written, this bifurcation has played out in the most extreme way.
(1) AI Hardware Economy: Leveraged Frenzy, Clearing Ends
The KOSPI in South Korea approached a peak of 9400 points in late June, with intra-year gains reaching as high as 116%. On July 8, the index entered a technical bear market; July 13 saw a "Black Monday" drop of 8.95%; July 24 dropped another 5.73%; and on July 28 it plummeted 12.84%, triggering the eighth market-wide circuit breaker of the year, closing at 6023.66 points—over one-third of the maximum drawdown from the peak. Samsung Electronics and SK Hynix dropped by 13.39% and 14.65%, respectively, on that day.
Retail investor leverage is the amplifier. The 16 stocks approved for two-times leveraged ETFs on May 27 attracted nearly 12 trillion Korean won in funds within fifty days—over 90% flowed into Samsung and SK Hynix—which led to a death spiral of "down → forced rebalancing selling → further decline," resulting in over 1.2 million leveraged accounts receiving margin calls, with hundreds of thousands forced to be liquidated. The exchange has triggered 40 side-car mechanisms and 8 circuit breakers this year; the KOSPI volatility index closed at 97.99 at the end of June, close to an all-time high.
The transmission chain is clear. The latest issuance of Meta's $12.5 billion data center bond was priced at about 5.0%, much higher than around 4.2% when it was issued in 2025—re-pricing of AI capital expenditure discount rates has begun; TSMC's June revenue turned negative month-on-month, with capital expenditure guidance adjusted to over $60 billion, triggering a global "computing power peak, memory surplus" chip sell-off. South Korea is the economy with the highest concentration in this industry chain (two stocks' market value exceeds half of the total index market value), with the heaviest retail investor leverage, while the central bank is still raising rates, leaving the won weak even under significant surplus. Chinese A-shares resonated simultaneously: on July 28, the ChiNext index plummeted 7.35%, marking the largest single-day drop in over a year, while the Shanghai Composite Index just managed to hold above 3800 points, with storage, optical modules, and semiconductors leading the decline, while banks and liquor stocks rose against the trend.
(2) Failure of Hedging and Weak Dollar: This is Not a Taper Tantrum
What best illustrates the detail of the policy mechanism transition is the failure of bond hedging: on July 28, while the Asia-Pacific stock market crashed, the yield on ten-year U.S. Treasuries not only did not decline but remained in the 4.6%—4.7% range—the old relationship of "stocks down, bonds up" did not appear. On that day, Nasdaq futures fell by 2.29%, while Dow futures rose by 1.12%, with cash-rich software stocks rising, and chip stocks falling. This is not a recession panic, but a re-pricing of discount rates and cash flow durations: capital has not exited but has shifted from long-duration assets to cash-generating assets—this is the standard signal of positive correlation and systematic duration re-pricing under fiscal dominance.
The position of the dollar is also telling: on July 28, the dollar index closed at only about 101.6, in the lower half of a multi-year range. This is different from the taper tantrum of 2013, where it was a strong dollar squeeze—the current risk comes from the U.S.'s own fiscal and AI financing re-pricing, with the dollar not strengthening in the impact. According to IIF data, non-resident investment portfolio funds saw a net outflow of $26.6 billion in May and $17.8 billion in June, contrasting with record inflows of $98.8 billion in January—this is a complete pressure sequence since the Iran war (Figure 5).
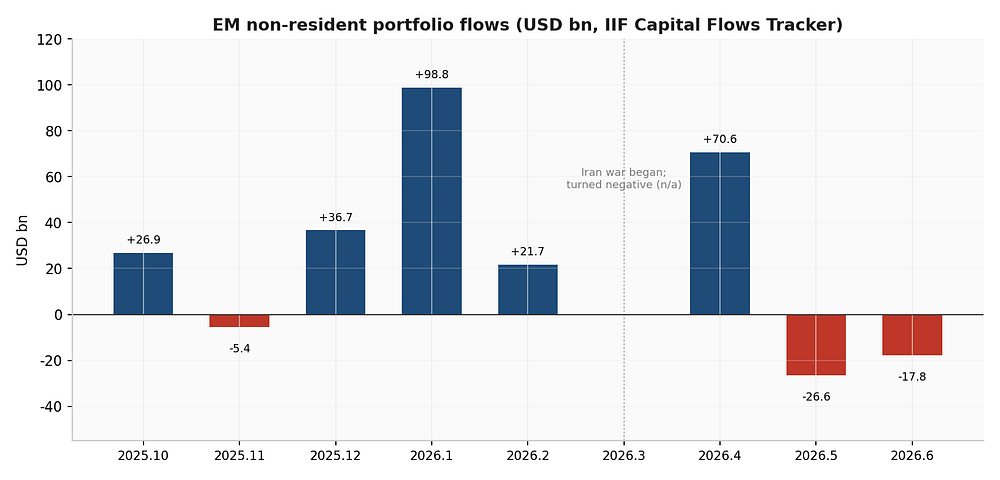
Figure: Flow of non-resident investment portfolio funds in emerging markets: from record inflows in January to two consecutive months of net outflows. Source: IIF
The derivatives pricing aligns with the spot market: Korea's five-year CDS is only 52.5bp, while China's is 31bp—credit markets have yet to price in the pressure; the stress is concentrated on capital flows and volatility—again presenting the bimodal characteristics of calm centers and shifting tails. China's position is quite unique: the ten-year Treasury yield is 1.73%, the lowest among the curves and policy spreads; CDS is calm; the Hang Seng Index rose by 9.9% in July—this is the "reverse extreme point" of the global term premium storm, exporting deflation while attracting reserve diversification demand for RMB assets. The decline of A-shares is a resonance of global AI industry chain re-pricing and domestic liquidity events—the IPO of Changxin Storage at 57.9 billion yuan (the largest in history on the Sci-Tech Innovation Board, freezing about 1.7 trillion yuan in new funds), extreme congestion (TMT trading volume exceeding 45%) and consecutive declines in financing balances—this is a structural clearing, not a systemic bear market.
(3) Neutral is Not Immune: Three Transmission Channels
For "strictly neutral" strategies—volatility strategies, dollar-neutral long and short, statistical arbitrage—one illusion must first be dispelled: neutrality hedges directional risk, not policy mechanism risk. The shock transmits through three channels.
Capital channel: EFFR is 3.63%, short-term Treasuries are 3.8%—4.0%, and each neutral strategy's cash threshold is about 400bp higher—total exposure just to maintain the status quo requires earning four extra points, while leverage costs (repos, swap financing, short selling) are rising simultaneously.
Correlation channel: In a world where stocks and bonds are positively correlated, "dollar-neutral" does not equal "duration-neutral"—longing growth and shorting value combinations imply short-duration exposure, and rate-driven factor rotation can trigger concentrated liquidations of crowded positions (the "quantitative winter" of 2022 is a template), and in tail moments, pairwise correlations approach 1, compressing the Sharpe ratio of statistical arbitrage.
Crowding channel: When term premium becomes the dominant macro variable, all macro-driven quantitative funds will lower risk simultaneously under the same signal—neutral strategies seldom die from direction; they perish due to soaring capital, crowding, and correlation, as evidenced by the "quant earthquake" in August 2007, February 2018, and the October 2022 UK LDI event.
(4) The Other Side of the Coin: Historical Fertile Ground for Volatility Strategies
It must be pointed out that the current policy mechanism is also the most fertile ground for disciplined volatility strategies in history. AI-driven concentration provides diversification opportunities for the U.S. and South Korea—high volatility in single stocks corresponds to low volatility in indices; the gap between the flat 25d stock skew and the extreme SKEW index is a time window for relative value volatility; the difference between interest rate volatility and equity volatility provides negative carry but positive expected convergence trades.
What needs to be avoided is leverage carry and short gamma: a bimodal distribution means that jump risks are increasing, with margin and VaR shocks always forcing deleveraging at the worst times. For multi-strategy funds built around volatility and derivatives, the information conveyed by the current policy mechanism can be condensed into one sentence: exposure has not disappeared—it has shifted from delta to gamma, capital, and crowding. The term premium itself has become a directly tradable risk factor: longing the steepening of 10s20s, longing the back payment volatility, longing the 25d call skew in gold, longing equity downside convexity (while the 25d skew remains flat)—the three legs price the same thing, and the pricing differences themselves are the source of alpha.
The core conclusion:
At both ends of the same chain: South Korea's leveraged clearing is the intersection of the "U.S. Treasury term premium → AI financing costs → long-duration re-pricing" encountering an extremely vulnerable microstructure of retail investors; the weak dollar, static credit, and the failure of bond hedging prove this to be a re-pricing of the policy mechanism, rather than a dollar squeeze or recession panic. For neutral strategies, exposure has not disappeared—it has shifted from delta to gamma, capital, and crowding.
7. Alternative Monitoring Checklist for Conclusions
This round of re-pricing is neither a validation of "collapse" theories nor a continuation of "excessive privilege" as usual. It resembles a blend of 1993 and 1975: while the magnitude still has some distance to cover, the mechanisms are of the same kind. For investors, the triggers are more useful than opinions:
Term premium: Are the readings of the New York Fed ACM and the San Francisco Fed CR continuously rising;
Equity skew gap: In what direction does the gap between SPY 25d skew and SKEW index converge;
Hedging structure: The resilience of the gold 25d call skew and the percentile turning of Bitcoin skew;
Supply digestion: The tail of the twenty-year U.S. Treasury auction;
Emerging markets: IIF monthly flow data, as well as tracking AI hardware economy right-tail frenzy for VKOSPI and Korean leveraged ETFs;
Policy mechanism signals: Does the U.S. Treasury yield continue to refuse to decline on risk aversion days—the failure of bond hedging itself is a signal.
When the "unit debt spread" converges from 0.85 to the G10 median of 1.25, and the 30Y—10Y slope shifts from +47bp towards the form of the U.K. and France, the "deep damage" will evolve from pricing structure into pricing consensus. History shows that the window period before consensus formation is always the best entry time for such trades.
This report is based on publicly available data and reasonable inferences and does not constitute investment advice.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


