In the past month, despite Lumentum (LITE) reporting outstanding performance and the ongoing acquisition by Marvell Technology (MRVL), the LITE stock price has significantly dropped. I believe this round of adjustment is very attractive, as the company's revenue and profits continue to grow, and performance continues to exceed my predictions. However, this acquisition has made the investment logic more complex, as shareholders now have to bear not only the risks associated with Lumentum itself but also be exposed to Marvell's valuation and the uncertainties of the transaction itself, which is expected to complete by 2028. I remain bullish on Lumentum, but if I were to make new investments now, I would be much more selective than before and would no longer simply view past historical highs as realistic targets for stock price recovery.
The financial report further strengthens my bullish logic
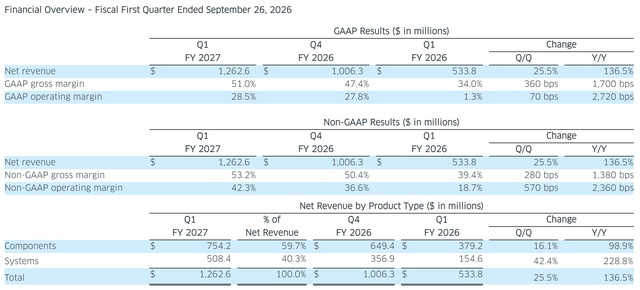
Lumentum's FY2027 first-quarter revenue reached $1.26 billion, a year-on-year increase of 136.5% and a quarter-on-quarter increase of 25.5%, which is quite impressive. Adjusted EPS grew from $1.10 to $4.57. Considering we are discussing the field of AI infrastructure and Lumentum is not a software company, thus lacking the extremely low production costs of software enterprises, such performance is even more remarkable.
What impressed me the most was the company's profitability. The adjusted gross margin increased from 39.4% to 53.2%, and the adjusted operating margin surged from 18.7% to 42.3%. Improving capacity utilization could be one reason, but I believe that an optimized product mix and pricing also made significant contributions to this result.
The revenue from the systems business also deserves special emphasis. Lumentum's systems business revenue reached $508.4 million, a year-on-year increase of 228.8%; in comparison, the components business revenue was $754.2 million, a year-on-year increase of 98.9%. This means that the systems business now accounts for about 40% of the company's total revenue. This is very important because Lumentum's exposure to OCS (Optical Circuit Switching) and advanced optical products is rapidly growing and has now become a significant part of the company's business.
The second-quarter revenue guidance is even more impressive. According to management's expectations, the company expects revenue to reach $1.575 billion to $1.625 billion, with an anticipated adjusted operating margin of 45%-46%, and EPS of $5.90-$6.20. Based on the midpoint of this guidance, this implies a quarter-on-quarter revenue growth of approximately 27%. I find it hard to identify many hardware suppliers able to deliver similar data.
[Original image location: FY2027 First Quarter Financial Results]
The Marvell acquisition is another factor that must be considered
The acquisition by Marvell has introduced some complexities to Lumentum's investment logic that were not necessary to consider when analyzing the company independently. According to the transaction agreement, Lumentum shareholders will receive 4.5 shares of Marvell stock for every share of LITE held, with the transaction expected to complete in the first half of 2028.
The strategic logic behind this transaction is actually not surprising. Marvell's capabilities in network connectivity and custom semiconductors highly complement Lumentum's strengths in optical manufacturing, lasers, and switching products. After the merger, the two companies can offer a more complete connectivity solution to large AI infrastructure customers. Management also expects to achieve over $1 billion in annual cost savings.
But I am concerned that Lumentum shareholders are becoming increasingly dependent on Marvell's valuation. Even if Lumentum continues to report extremely strong performance each quarter, as long as Marvell's stock price continues to fall, this performance may not significantly help LITE's stock price. The trading on November 16 illustrates this point well: LITE fell by 8.48% that day to $546, while MRVL dropped by 7.27% to $145.36. Due to the share exchange agreement, the interconnection between the two stocks has been significantly enhanced.
Initially, I viewed this round of stock price adjustment primarily from the perspective of Lumentum's profitability. However, as I delve deeper into this transaction, I increasingly feel that the profitability multiples of the standalone company are no longer suitable for assessing LITE's short-term stock price. Lumentum's profitability remains important, but if the transaction is successfully completed, its importance will diminish; it will only regain centrality if the deal fails. Shareholders buying LITE today must also be willing to continue holding Marvell stock after the transaction is completed. This is a completely different investment compared to directly buying an independent optical components manufacturer.
Cash generation capability is also crucial
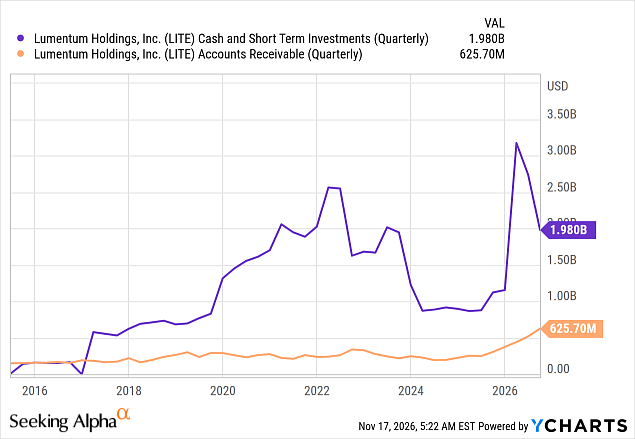
There is one aspect in which I am not willing to unconditionally give Lumentum a pass. The company ended the quarter with $2 billion in cash and short-term investments, a decrease of $758.8 million compared to the previous quarter, despite the company's strong profitability performance.
Inventory increased from $691.6 million to $807.7 million, accounts receivable rose from $520.3 million to $625.7 million, and property, plant, and equipment also experienced growth. These changes in themselves are not necessarily concerning. Manufacturers clearly need more inventory and equipment to meet rapidly growing demand. But I would like to see that, alongside the continuous improvement in adjusted earnings, cash generation capability can also enhance concurrently.
The currently reported decline in cash, relying solely on operational explanations, is insufficient to draw conclusions unless we further analyze the cash flow statement in detail. Therefore, until I have a clear view on this issue, I will wait for a more comprehensive cash flow reconciliation from the company regarding operations, investments, and financing activities.
[Original image location: Lumentum stock performance]
This round of sell-off has created an upside potential of up to 55%
Based on MRVL's closing price of $145.36 on November 16, the exchange ratio of 4.5 in the agreement implies that each share of LITE corresponds to a value of approximately $654.12. Compared to LITE's closing price of $546 on that day, this suggests a potential upside of about 20%, provided the transaction is successfully completed and Marvell's stock price remains unchanged. This discount looks attractive, but since the transaction will not complete until 2028, the actual appeal is not as high as the superficial numbers suggest. If Marvell's stock price drops to $120, then the exchange value would fall to $540, effectively wiping out the current upside potential.
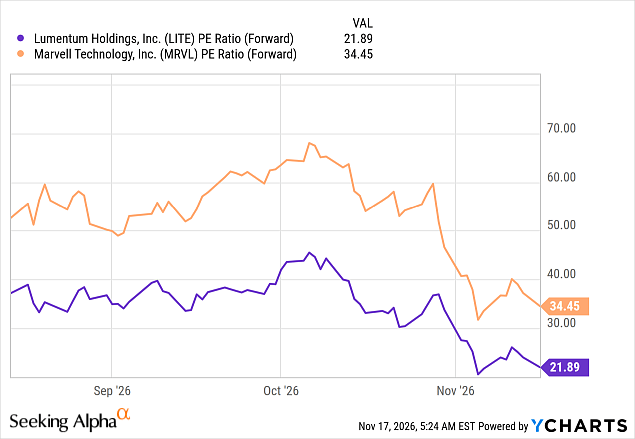
According to the $6.05 EPS guidance provided by management, annualized earnings power is about $24.20 per share. If a more conservative multiple of 20 times earnings is applied, the valuation is $484; applying a 30 times earnings multiple yields $726, representing about a 33% increase; if a 35 times earnings multiple is used, it corresponds to $847, implying about a 55% potential upside. In my view, if AI growth can sustain, considering Lumentum's revenue growth, margin expansion, and customer order commitments, these higher valuation multiples are not unrealistic. However, it must be emphasized that these are merely scenario valuations based on profitability and not the company's official guidance for year-end stock price or annual earnings.
On the other hand, based on the current MRVL stock price, the acquisition price corresponds to about $654.12 per share of LITE, which is around 20% higher than the current $546. In my view, the combination of profit growth momentum, acquisition price, and potential upside still supports my "strong buy" view on LITE.
[Original image location: Comparison of LITE's potential valuation and acquisition price]
What risks would prompt me to reevaluate my investment logic
First of all, I am worried that Lumentum's continuously improving operating performance may gradually decouple from the returns ultimately received by shareholders. If Marvell's stock price drops, then the acquisition price will decrease, regardless of how well Lumentum performs. If the timeline for completing the transaction is further delayed, the time shareholders are exposed to this uncertainty will also increase.
From an operational perspective, if revenue continues to grow rapidly, but margins start to shrink significantly, I would begin to worry. This could mean that the benefits of added sales are being offset by production expansion issues or pricing pressures.
Final thoughts
After experiencing this significant adjustment, I still remain bullish on LITE. Lumentum's current stock price is around $546 per share, which I believe offers a very good entry point, as the current valuation is supported by continuously improving profitability, expanding margins, and multi-billion-dollar customer orders.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


