Original authors: Yang Chen, Long Yue
Original source: Wall Street Journal
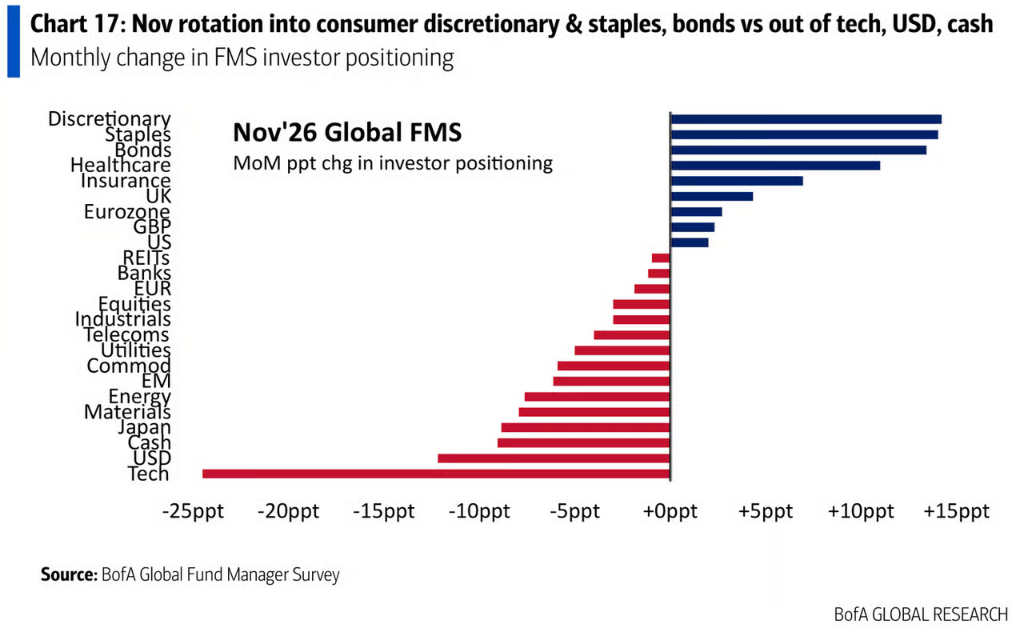
Bank of America's latest monthly survey shows that global fund managers are withdrawing from technology stocks at the fastest rate since 2006.
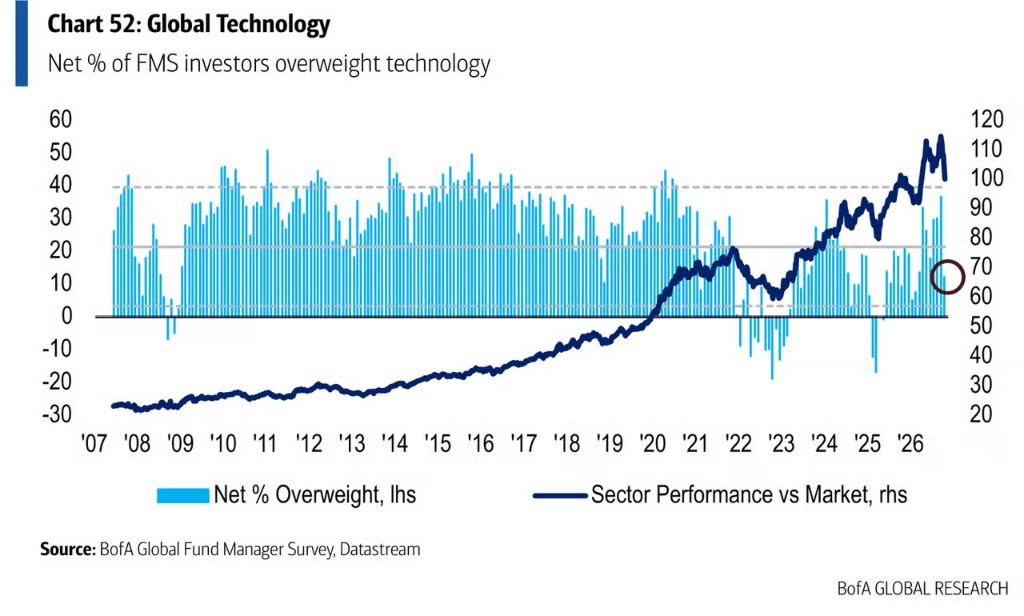
The survey shows that the overweight ratio of technology stocks has plummeted from a net 37% in October to a net 12%, marking the largest monthly decline in nearly 20 years.
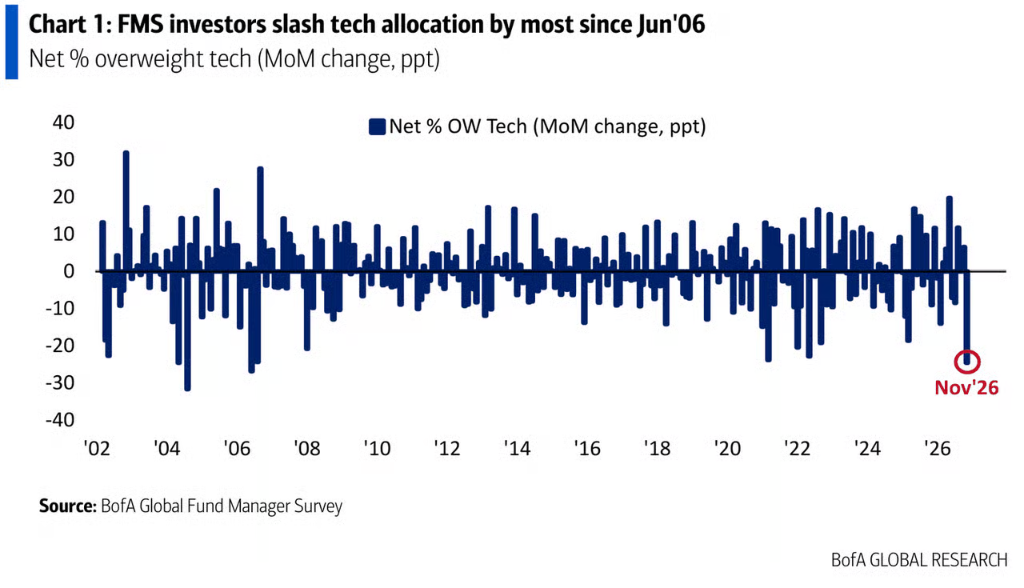
BofA strategist Michael Hartnett bluntly stated in the report that "the AI boom and euphoria have ended," and advised investors to maintain a defensive position in the coming months.
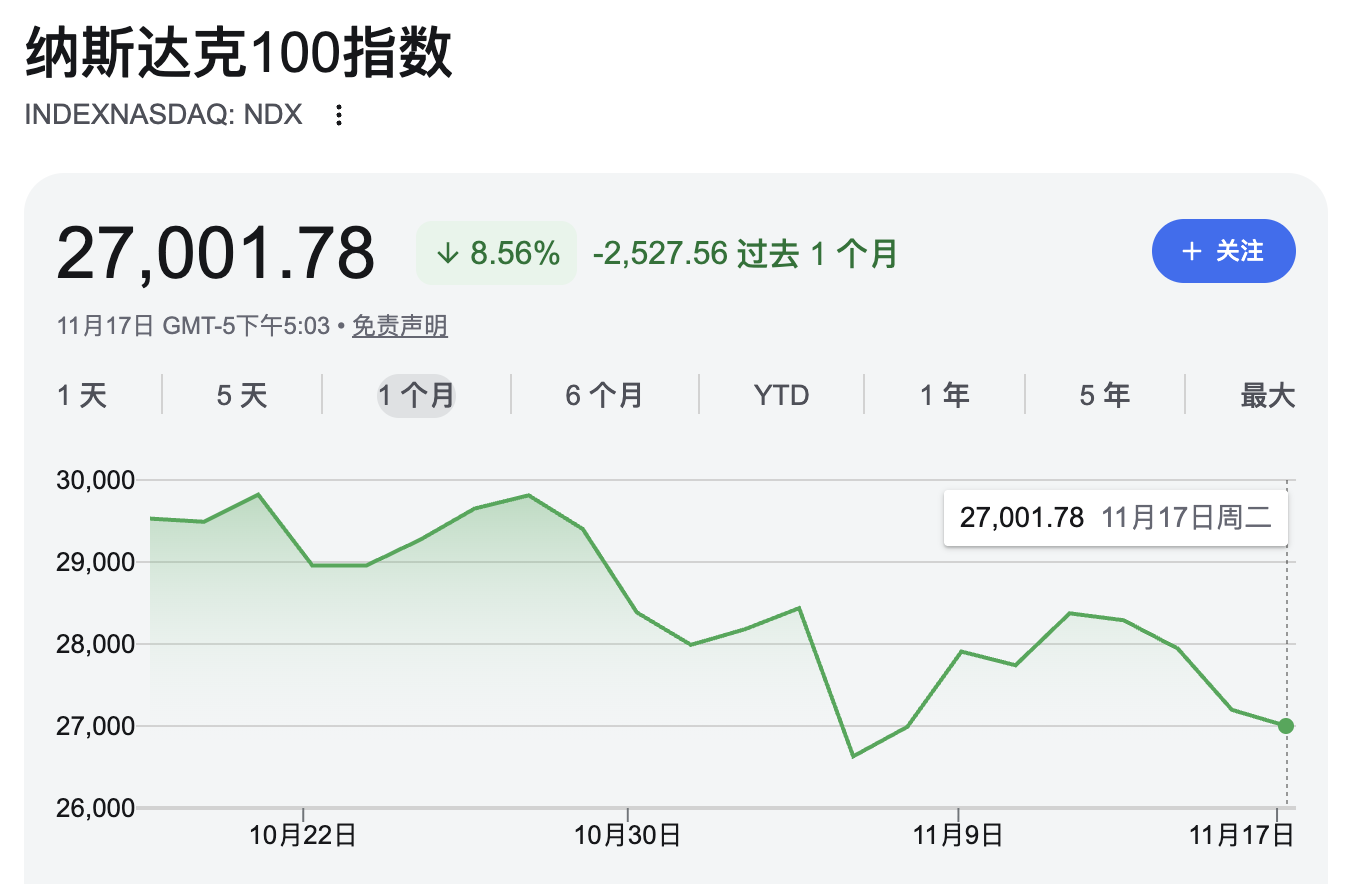
Market performance confirms this shift in sentiment. The Nasdaq 100 index has fallen more than 4% this month and is expected to record its worst November performance since 2008; semiconductor-related stock indices have dropped 27% cumulatively since early October.
This survey was conducted from November 6 to 12, covering 169 participants globally, managing a total of $461 billion in assets; 94 participants from Europe responded, managing a total of $241 billion in assets.
Technology stocks face large-scale reductions, but bottom fishing is not advisable
Fund managers' enthusiasm for technology stocks is rapidly fading. The survey shows that the overweight ratio of technology stocks fell from a net 37% in October to a net 12%, the largest decline since June 2006, surpassing any during the 2008 financial crisis, the 2022 rate hike cycle, and the "equal tariffs day on April 2" this year.
Currently, the position in technology stocks is below the long-term average by about half a standard deviation.
In addition, Goldman Sachs' commodity brokerage department recorded the largest week-over-week leverage reduction for hedge funds since March 2020 two weeks ago; last week, the same group of funds sold off the strongest rebound in chips since April, pushing Goldman’s tech long-short ratio to a historical low; 13F filings show that Druckenmiller and others started reducing chip holdings as early as the third quarter. Hedge funds are exiting, and long-term funds are following.
Hartnett suggests that based on historical patterns, the best entry point occurs after fund managers further reduce their positions in technology stocks to an underweight status; currently, the survey has not shown enough investor "panic" sentiment, making it inadvisable to enter hastily.
65% consider AI the number one risk
Behind the mass exodus of fund managers from technology stocks is a shaky confidence in the AI narrative itself.
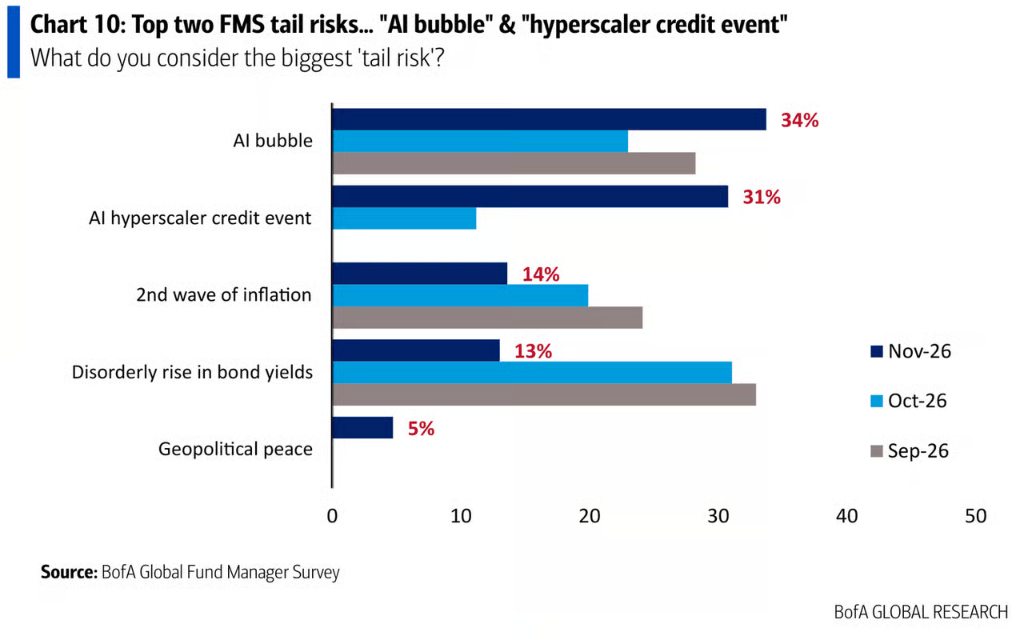
In the voting for the largest tail risk, "AI bubble" ranked first with 34%, followed closely by "credit events of AI mega-operators" at 31%. Combined, these account for 65%, indicating that two-thirds of fund managers view AI as the greatest threat to the current stock and credit markets. In contrast, the number one risk in October was the disorderly rise in bond yields.
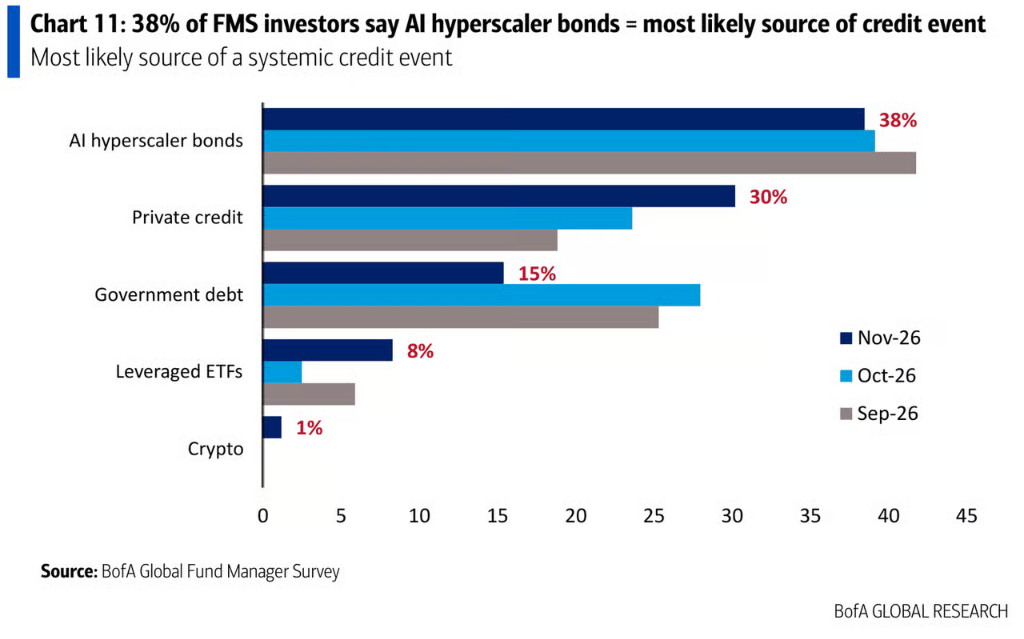
Among the most likely sources of systemic credit events, 38% of respondents pointed to the bonds of AI mega-operators, while 30% pointed to private credit.
Meanwhile, investors' patience with corporate AI spending has worn thin. A record net 38% of respondents believe corporations are over-investing, a ratio that first exceeded zero at the end of last year and has continued to climb since. Regarding "how to use corporate cash flow," 42% advocate improving balance sheets, 33% advocate returning to shareholders, and only 16% support increasing capital expenditures — the lowest since May 2020, when no one knew whether the economy would still exist. In January of this year, this figure was still 34%.
52% of respondents expect that within the next six months, some AI mega-operators will announce reductions in capital expenditures, up from 30% in October, while 79% of respondents in September believed there would be no reductions this year.
Hartnett describes this signal as the strongest call from fund managers to corporations to "stop spending," with such a call never being so loud historically.
Cash levels low, panic insufficient, Hartnett refrains from giving buy signals
Despite the clear shift in sentiment, the actual movement of funds tells a different story.
The cash holding ratio has decreased from 3.9% to 3.6%, the lowest since August, and is positioned 1.9 standard deviations below the long-term mean. According to Bank of America's "cash rule," when the cash ratio is at or below 4.0%, it constitutes a contrarian sell signal for the global stock market — according to Bloomberg, since 2011, the median return rate within four weeks after such signals are issued is -1%, with the worst recorded at -29%.
Although technology stocks are under pressure, fund managers' concerns about the macroeconomic outlook remain relatively mild. Only about 3% of respondents expect a recession in the coming year. The global stock market remains consensus as the best asset class for 2027. Bank of America’s composite sentiment index has slightly decreased from 6.4 to 6.3, the lowest since June.
Hartnett's Bull & Bear Indicator is currently at 7.4, well below the peak of 9.5 reached in September, but still far from the level below 2.0 that triggers a contrarian buy signal.
Hartnett wrote:
In the November survey, investors are bullish on the macro level (only 3% predict a recession) and hold positions that are optimistic on the market level (cash is at a super-low 3.6%, believing global stocks will become the best-performing assets in 2027); however, the AI boom and euphoria have come to an end... We maintain a tactical defensive stance, and the November survey has not shown sufficient investor panic sentiment, making it inadvisable to enter the market.
Multiple institutions remain optimistic about future markets
Other institutions still hold an optimistic stance on the overall stock market. Morgan Stanley stated this week that the AI spending boom will make 2027 "the year to embrace risk"; Goldman Sachs expects the S&P 500 index to rise 17% in the next 12 months, with a target level of 8700 points.
In terms of asset allocation, about 36% of fund managers expect international stocks to be the best-performing asset class in 2027, followed by US stocks (24%) and gold (17%).
Optimism in European stock markets rises, profit expectations improve
Compared to the cooling of global technology stocks, investment sentiment in European stock markets has clearly improved.
A net 67% of fund managers expect European stock markets to rise in the next one to three months, up from a net 44% last month, reaching the highest level since February. Respondents expect an average increase of 5.92% in European stock markets over the next 12 months, higher than the previous 4.53%; average earnings growth expectations have also been raised from 6.09% to 6.58%.
From the perspective of profit-driving logic, cost control has become the top driving factor for 43% of fund managers in terms of European corporate profits, reaching the top for the first time since May; 37% of respondents believe that sales or revenue growth is the main driving force, with 13% pointing to profit margin expansion.
On a macro level, a net 40% of respondents expect European economic growth to improve in the next 12 months, significantly higher than the previous 22%.
On the industry level, the industrial goods and services sector has become the sector with the highest overweight ratio since September 2025; the construction and healthcare sectors have also shifted from underweight to overweight, while the basic resources and energy sectors have returned to neutral.
The automotive sector remains the most neglected, with a net underweight ratio as high as 47%. Among the sectors most favored for the next 12 months, about 23% of respondents prefer healthcare, followed closely by consumer discretionary and financial sectors, each accounting for 17%.
Among various national markets, Switzerland has become the most favored market with a net preference ratio of 30%, followed by Germany at 27%. France, on the other hand, has the lowest net preference ratio at -60%, setting a historic low.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


