Author: Jerry Neumann, former professor of entrepreneurship at Columbia University, senior retired venture capitalist
Translation: ShenChao TechFlow
ShenChao Introduction: Once known for their "small and beautiful, strict discipline" approach, Benchmark and USV have recently both significantly expanded their fundraising, with each partner managing funds reaching historic highs. This departure from their original intent reflects the severe reality that the entire venture capital industry is being swept by an AI arms race and the concentration of enormous capital.
Veteran investor Jerry Neumann points out, using Knight's theory of "risk and uncertainty" and comparing it to historical crises from the 1980s, that when capital growth far exceeds the cognitive capacity of partners, institutions will inevitably abandon uncertain risks and degrade into seeking certainty through leveraged acquisitions or growth equity investments.
The excess returns in venture capital essentially stem from underwriting true uncertainty that no one has ventured into. As leading giants indulge in the scale of funds and defensive premium wars, the traditional venture capital model is once again heading towards partial extinction, while the hope of nurturing the next technological era will return to those agile small funds that dare to bet on obscure unknowns.
Abandoning Restraint: The Huge Turn of Two Early Icons
In 2024, one of the most successful early venture capital firms, Benchmark, raised a $425 million fund, while its partners also contributed an additional $170 million. This means that each of the five partners needs to manage nearly $120 million on average.
In a letter to investors (LPs) at that time, the partners explicitly stated that they deliberately aimed to maintain fund sizes at previous levels in order to "force self-discipline and a sense of responsibility, thus focusing on what truly matters."
However, in June of this year, Benchmark raised a total funding pool of up to $2 billion: including a $750 million early-stage investment fund, and the unprecedented establishment of a $1.25 billion growth fund. Managed by the same five partners, the average management scale surged to $400 million. What was once considered "truly important things" seems to have undergone a qualitative change quietly.
Ten years ago, Fred Wilson, the founder of the highly esteemed early investment benchmark Union Square Ventures (USV), openly wrote: "If USV were to manage a $1 billion fund, I would probably spend sleepless nights."
Until before 2024, USV's core fund size was strictly restrained between $125 million and $200 million. However, in October of this year, USV announced the completion of fundraising for a new $900 million fund, which includes a $500 million core fund and a $400 million opportunity fund, managed by five investment partners. Wilson is dangerously close to the sleepless nightmare he once feared.
Benchmark and USV are noteworthy because their reputation and enormous returns depend entirely on their precise enablement of nascent enterprises at the very early stages. Choosing to raise a fund far exceeding previous sizes is tantamount to testing the edge of abandoning their most proficient skills.
This is not an isolated event; they are merely following the recent trend of the entire industry towards gigantic funds. By 2025, the top ten venture capital funds absorbed a third of all industry funding, far surpassing 13% in 2021.
This trend of concentrating capital at the top is intensifying. From 2026 to now, funds exceeding $1 billion have consumed 72% of all venture capital raised in the U.S., compared to 34% in 2025, and only 16% a decade ago. But institutions with large capital have not proportionally expanded their partner teams. Increasingly, more funds are becoming highly concentrated in very few hands, which has become a common picture across the industry.
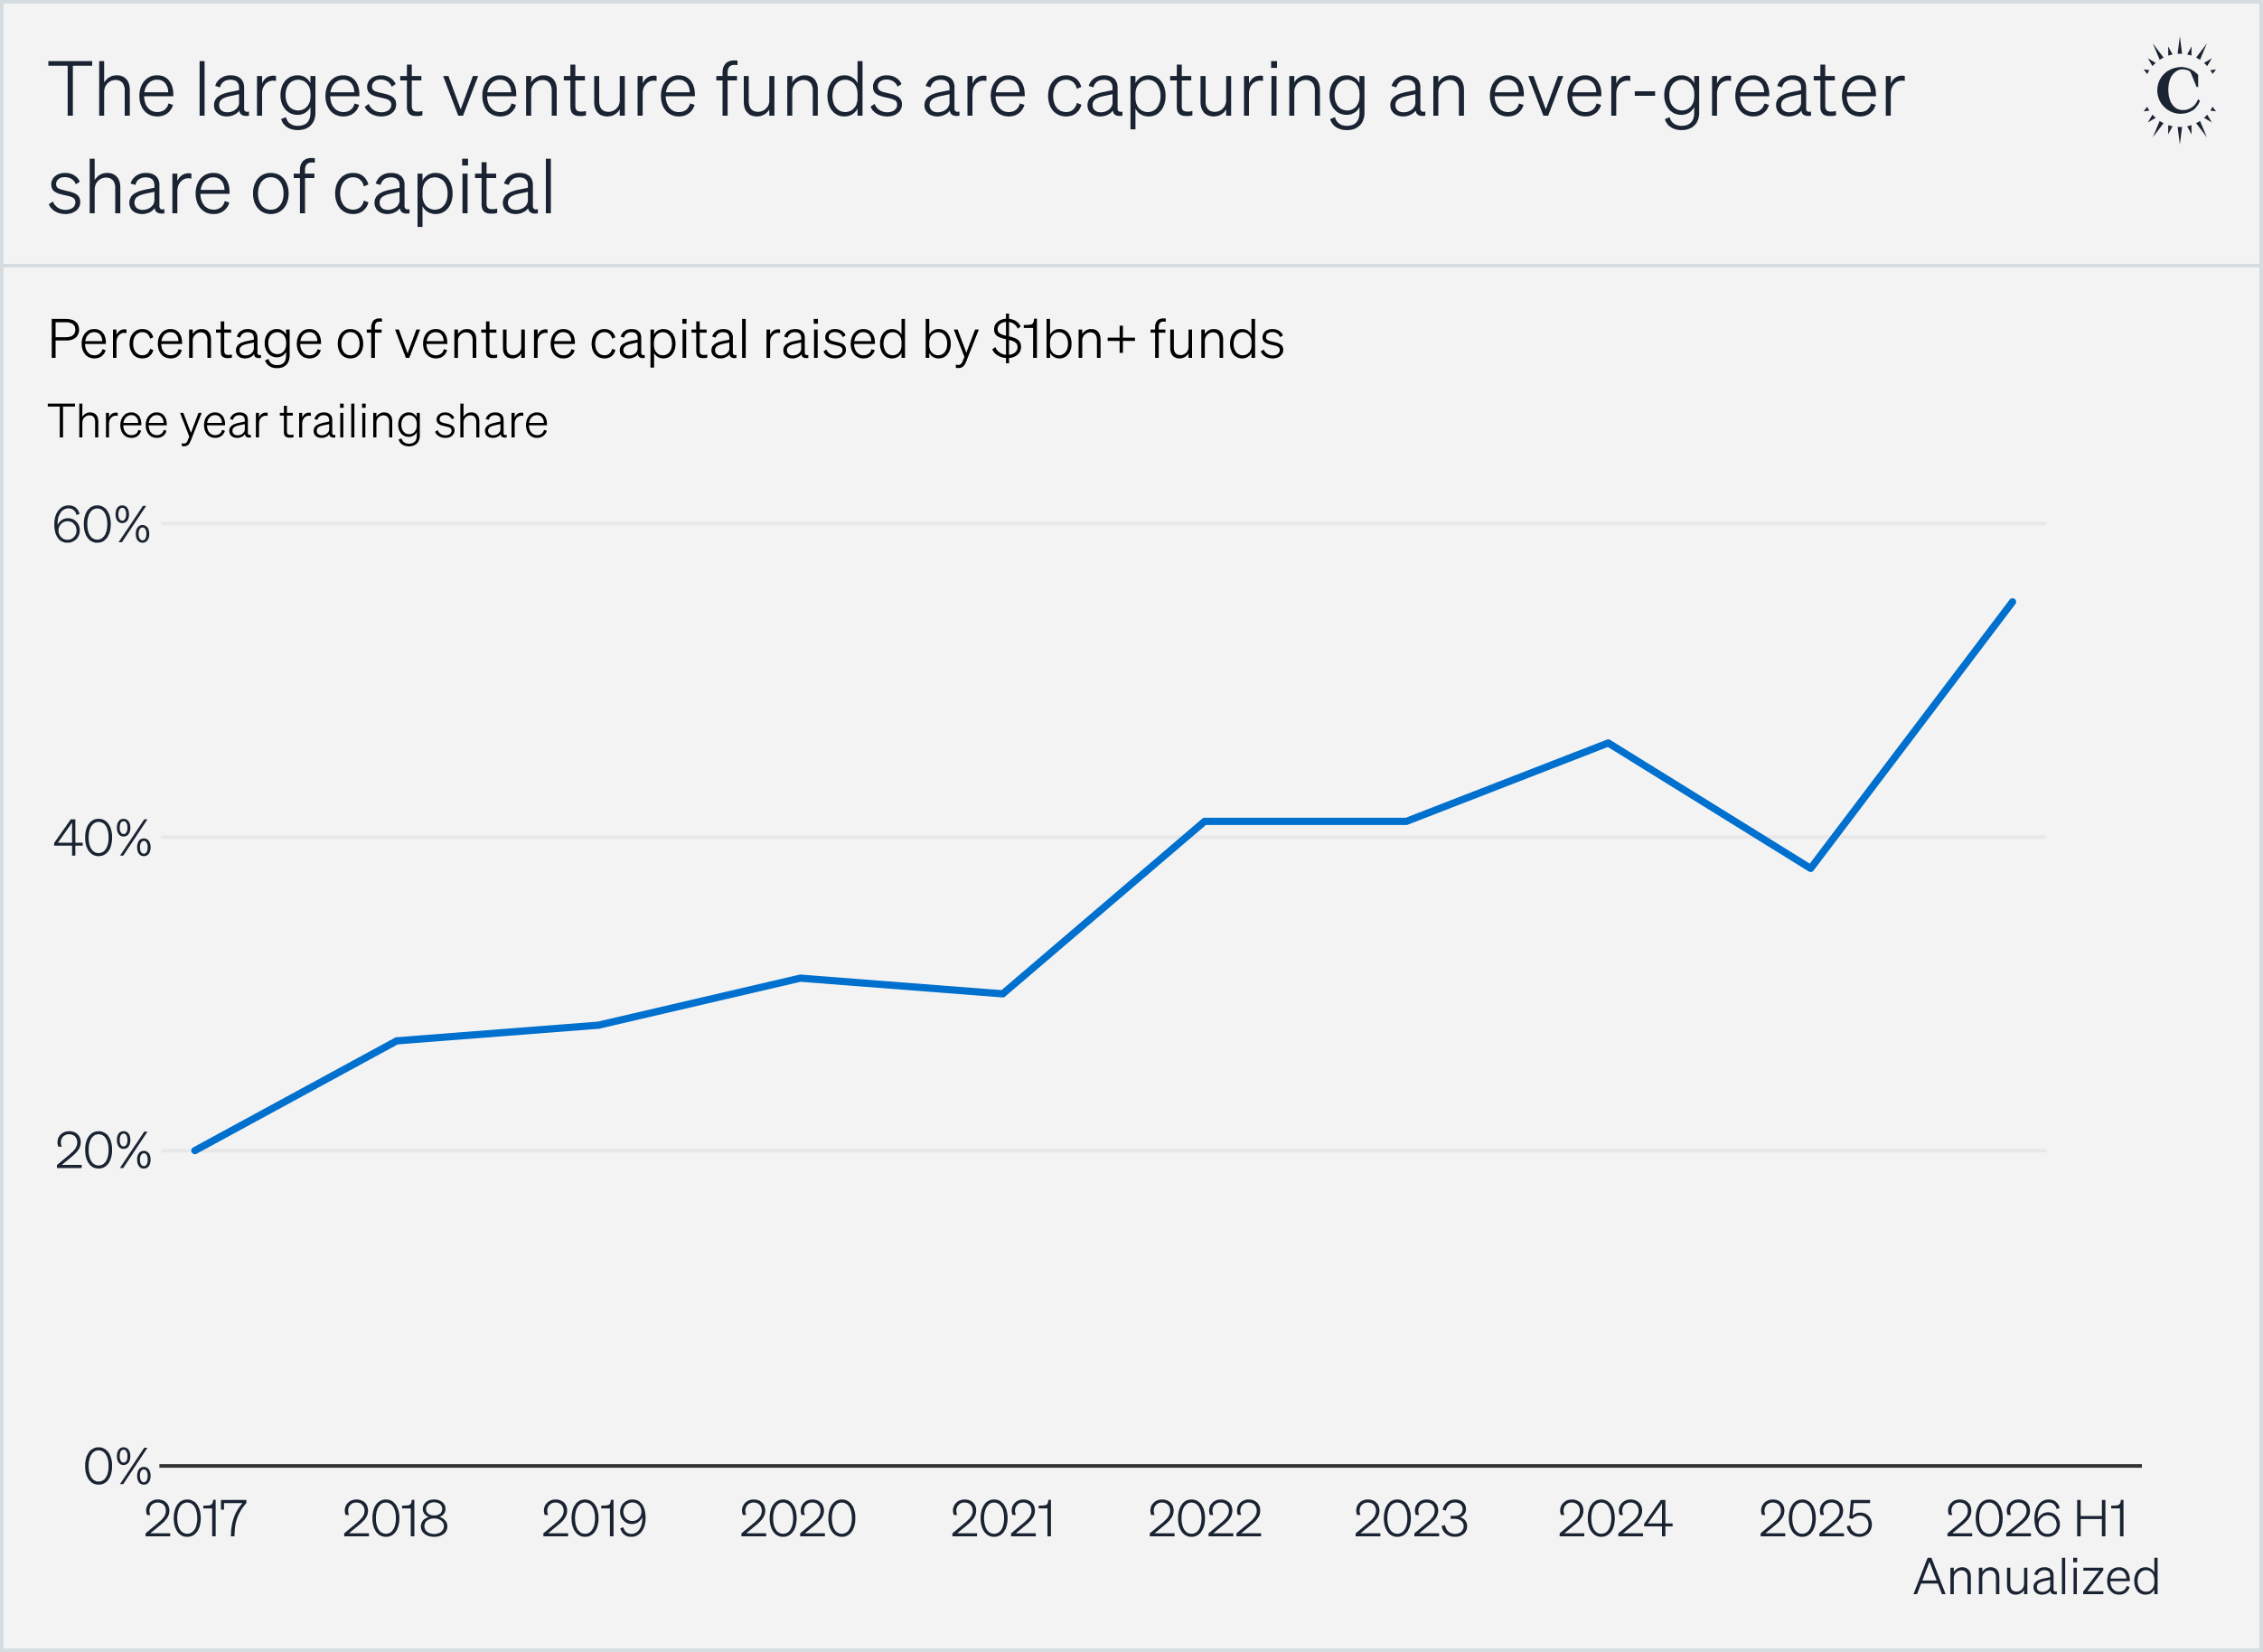
Chart: Data source: NVCA Yearbook 2026, Pitchbook
To a large extent, the compensation of venture capital institutions is directly linked to the scale of capital they manage. Top-tier firms like Benchmark and USV, with their stellar records, reasonably strive for larger asset management scale for each partner, from a business rationality perspective.
However, the underlying logic of venture capital always relies on two pillars: one is investing in nascent micro-enterprises that have objective physical limits on capital absorption; the second is that each partner must personally engage and actively manage projects that constantly face the risk of early-stage failure. When average managed funds surge, one of these two pillars must shatter. At what critical point does this no longer even qualify as venture capital?
Risk and Uncertainty: The Fundamental Cornerstone of Venture Capital
Pioneers in venture capital in the 1960s summarised an effective strategy: to establish a portfolio consisting of small trial-and-error investments and to follow up with substantial investments in those enterprises that have proven to be viable. These two elements are essential, as in the venture world, returns strictly follow an extreme power law distribution, and startups constantly face deep-rooted extreme uncertainty.
The scholar Frank Knight, who first proposed the theory of entrepreneurial economics, provided a classic definition of "uncertainty": when you know the odds of winning or losing, you are facing "risk"; when you have no way of knowing the odds, you are facing "uncertainty".
Mature and well-operating conventional companies bear risks, while startups face pure uncertainty. When there is certainty, a company can apply for a loan from a bank; when facing calculable risks, secondary stock markets and private equity funds will naturally come in to price.
But when true extreme uncertainty arises, and a company's foundation is built on variables that current human cognition cannot predict, only venture capital can provide a solution. In short, this is the essence of how the venture capital model operates. By diversifying investments across many micro-teams and managing losses in phases, venture capitalists can navigate uncertainty.
Well-managed established giants have no fear of taking risks; insurance companies and banks are constantly buying and selling risks, but they demand statistical predictability. Thus, large companies systematically eliminate uncertainty projects from their processes that cannot be reasonably assessed for expected returns.
This means that only those without other options will pursue ideas filled with uncertainty. These desperate individuals are the entrepreneurs, whose mission is to bear uncertainty. This exploration avoids direct confrontation with resource-rich giants, allowing startups to secure narrow windows for development.
The most successful entrepreneurs in history often maneuver through uncertainty by creating unprecedented new markets. The upside in existing markets is limited by known capacities; however, new markets represent entirely new spaces that humanity has never ventured into, with no upper limit that can be assessed. When Apple was founded in 1976, no one knew how large the personal computer market could actually be.
This unexpected positive surprise led to an attractive long-tail distribution in business results. The rational strategy in the face of extreme uncertainty is not to go all-in on a single company in the early stages but rather to construct a diversified portfolio and retain the option for subsequent investments through phased funding.
When There Is Too Much Capital: The Double Curse of Partner Time and Returns
Entrepreneurs cannot juggle multiple uncertain ideas at the same time; focusing on honing a single project is exhausting enough. This is precisely the significance of the social division of labor in venture capital: venture capital institutions manage uncertainty at the portfolio level, allowing frontline entrepreneurs to concentrate fully on their specific business.
Venture capital partners must manage both their own investment uncertainties and assist startup teams in resisting external risks. However, partners' energies have unbreakable biological limits. The traditional rule of thumb is that a partner can deeply participate as the core leading investor and assume a board role in only about 10 to 12 companies.
To increase the volume of investments managed by each partner, institutions typically have only two paths: either increase the number of projects invested in or force more funding into each project.
If institutions choose to increase the number of investment subjects, partners will have to step away from a deep leading role and instead rely on external leading investors' due diligence judgments and go with the flow. But such freeloading behavior will fundamentally undermine the mechanism of managing the risk of failure in companies through deep enabling.
The alternative approach is to increase the scale of single transactions: either paying a higher valuation premium at the early stage or pushing funds toward later rounds. However, whether paying exorbitant valuations early or buying into mature subjects with significantly diluted uncertainty later will irreversibly erode the long-term return on capital.
Later-stage growth investments have essentially evolved into a completely different financial category. It deals with known probability conventional risks, rather than exploring unknown pure uncertainty. This also requires partners to expend a large amount of effort negotiating and engaging with external private buyers, severely encroaching on the focus originally devoted to early nurturing.
The Echoes of History: The Venture Capital Crash Crisis of the 1980s
The phenomenon of each partner managing too much capital, leading to a dramatic plummet in overall return rates, has already played out through a complete painful cycle in the history of venture capital.
In 1979, the U.S. modified the prudent man rule in the Employee Retirement Income Security Act (ERISA), clearing the first hurdle for massive funds from pension funds to flow into the venture capital industry. In just five years, the annual fundraising scale for venture capital in the U.S. skyrocketed sixteen-fold, from $218 million in 1978 to $3.6 billion in 1983.
However, the speed of training professional investment talent across the industry could not match the astonishing influx of capital. From 1978 to 1987, the average asset scale managed per venture capital professional tripled, from $4 million to $12 million.
This imbalance had the most direct adverse consequence of skyrocketing valuation bubbles. The Wall Street Journal pointed out in 1983 that: "The valuations of young companies have risen too quickly, making it extremely difficult for traditional early-stage venture capital to earn their required 5 to 10 times return." The overall industry median internal rate of return (IRR) fell from over 30% in 1982 to around 8% in 1988.
The inflated fund sizes triggered even more lethal chain reactions: there simply were not enough early-stage startups in the market to absorb such enormous capital. The Wall Street Journal recorded in 1988: "In many cases, the massive fund sizes have made seed-stage investments a trivial adjunct to core business."
The proportion of seed-stage investments shrank from 25% of total U.S. venture capital in 1980 to just 12.5% in 1988. In response, many venture capital firms simply pivoted to leverage buyouts (LBOs). This category, which found no footing in 1980, consumed 23% of U.S. venture capital funds by 1986.
Many established venture firms, including J.H. Whitney, Patricof, and Warburg Pincus, either significantly engaged or completely transformed into LBO private firms, and even Sequoia Capital once attempted leverage buyout deals.
Those that still adhered to the name of venture capital began to shy away from uncertain risks, instead funding stock market consolidations in mature, homogenous competitive landscapes and traditional retail businesses with no technological barriers. Office supply superstore Staples was a good investment, but in the subsequent two years, investors rushed to pour nearly $200 million into at least 16 similar supermarket chains.
This rapidly evolved into a vicious price war and a wave of bankruptcies. As venture capital aimed to eliminate uncertainty to pursue low volatility, it ultimately resulted in chaos across the board.
As capital was pulled away from technological sources and diverted into mergers and acquisitions within mature industries, the number of new companies engaged in core technological innovation saw a dramatic decline. The establishment of new technology product companies in the U.S. dropped by 28% from its peak in 1982 to a low in 1991; the number of new independent software developers fell by a staggering 76% within five years.
Faced with a lack of investable targets, committed capital flowing into venture capital halved from 1989 to 1991, down 71%. Marc Andreessen candidly remarked about Silicon Valley in early 1994, saying: "It was completely dead, a lifeless pond."
In short, the once-glorious venture capital industry faced an influx of capital that far exceeded its absorption capacity due to loosening regulations; when the speed of money outpaced the availability of investment talent, returns began to collapse; in response, institutions shrank back and abandoned uncertainty, thus falling into a vicious cycle of lower returns.
Replaying the Mistakes Under the AI Arms Race
Today, we stand at a remarkably similar historical crossroads. Based on the scale of Benchmark's new fund in 2026, each partner will need to invest $400 million, over three times the scale they believed they could maintain two years ago. Each USV partner now also needs to manage $180 million, likewise several multiples of their previous levels of capital.
This is not an isolated case. U.S. venture capital fundraising peaked at $223 billion in 2022 but plummeted to $67 billion in 2025. Although this year's data has seen some rebound, vast amounts of capital are irreversibly concentrating toward a very few mega-funds. If history serves as any warning, we may be on the brink of replaying the painful prelude of the early 1990s.
No one intends to deliberately sabotage venture capital. The current enormous inflation is essentially an unending arms race. The explosion of generative AI has pushed capital thresholds and market valuations to outrageously high levels, as if only massive funds holding large amounts of money are deserving of entry tickets.
Cutting-edge labs require billions to build data centers and train foundational models, while numerous emerging AI startups demand exorbitant sums in their first round of financing, such as Thinking Machines securing a staggering $2 billion in its first financing round in 2025. But regardless of how grand the intentions may be, this fundamentally violates the core tenets of venture capital.
OpenAI initially faced true uncertainty that no one could grasp. This pure unknown allowed it several years to explore foundational technology and business closed loops, consuming only about $130 million in its founding years. Meanwhile, most emerging AI companies have stepped into a highly saturated, mature arena surrounded by giants.
They can secure vast funding because the underlying uncertainty has long been explored by pioneers; however, they must face the strangulation of global tech giants holding the most abundant resources. It seems venture capitalists have returned to the 1980s, keen on gambling with known risks in the red sea while fearing to truly embrace the unknown uncertainty.
Using exorbitant valuations that underwrite uncertainties to buy into conventional risky enterprises engaged in homogeneous competition, the resulting real return on exit is destined to be unable to compensate for the high entry tickets. Just as General Motors acquired Cruise for over $1 billion at the peak of self-driving hype in 2016, ultimately being forced to close it down in 2024, the glamour eventually ebbed to reveal the underlying truth.
Big Money to the Left, Venture Capital to the Right: The Next Generation of Pioneers from the Ashes
Venture capital is essentially about underwriting extreme uncertainties to capture excess profits in the right tail of a power-law distribution. When the funds allocated to each partner in a fund are severely overloaded, they are either forced to compromise by engaging in poor premium transactions or can only seek safety by reducing uncertainty. The former is bad business, and the latter ceases to qualify as venture capital.
In this sense, venture capital is once again entering its cycle of partial extinction. There is nothing wrong with engaging in growth equity or leveraged buyouts; the market indeed needs such asset transporters. But the world also cannot do without true venture capital. As large funds collectively drift away, agile small funds will inevitably take up the exploration torch.
The historical rhymes are currently echoing clearly: Lightspeed has set up a fund of over $750 million for the acquisition of vintage enterprises, forcefully wrapping them in AI packaging; Thrive Capital spent $7.6 billion on a leveraged buyout of the 150-year-old traditional home security company ADT.
Top-tier former venture capital titans are expending significant effort on asset bundling, restructuring, and mergers, while the genuine venture forces focused on seed and early-stage investing are facing severe shrinkage.
Meanwhile, the pure venture forces focused on seed and early-stage investments are experiencing a significant contraction. In 2025, the proportion of first-time funds among total U.S. venture capital plummeted to a historic low of 10.9%; the share of early micro-funds under $100 million also shrank to just 11.7%.
But it’s worth remembering that during the major recession of the 1980s, it was independent currents like Kleiner Perkins and Accel that steadfastly adhered to early uncertainties that eventually transformed into ruling legends during the internet wave of the 1990s, leading humanity’s grand innovation renaissance.
Venture capital did not truly vanish in the 1980s, and it will not this time either. The eye-catching massive funds will ultimately occupy media headlines, but the true pulsating future of the venture capital industry will always belong to the minority investors who remain sharp and awake, quietly accompanying entrepreneurs in exploring new markets on the edge of the unknown.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


