NVIDIA has announced that company co-founder and its only CEO for 33 years, Jensen Huang, has resigned immediately and also stepped down from the board. CFO Colette Kress will serve as interim CEO, and Harvey Jones, a veteran from Synopsys, will become the company's first chairman of the board. Candidates for the permanent CEO position will be considered from both internal and external sources.
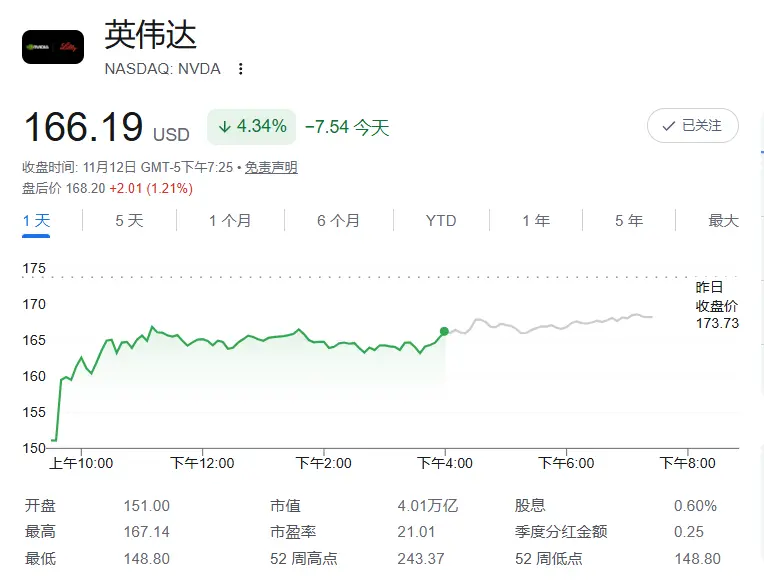
The news landed at 8:48 AM Eastern Time on the 12th. Before the opening, NVIDIA's stock price had fallen about 10% to around $156, breaching the 52-week low of $164.27. The market capitalization evaporated by about $420 billion in a single day, and over the past month, the company's valuation has decreased by about one-third.
That evening, research reports from 14 Wall Street investment banks flooded the inboxes of analysts and fund managers.
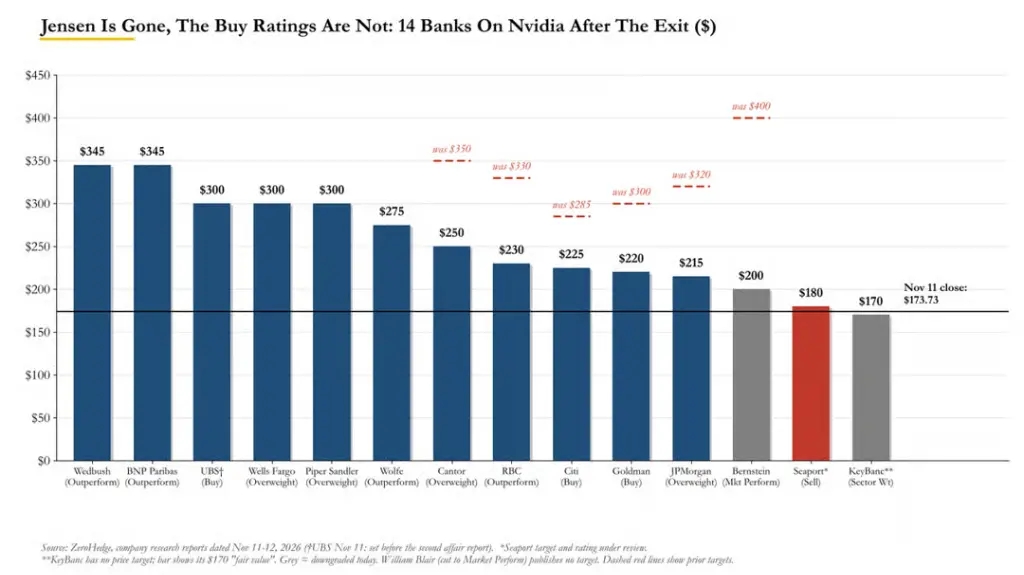
Three firms downgraded NVIDIA’s rating: Bernstein, KeyBanc, and William Blair. Six others lowered their target prices: Bernstein, JPMorgan, RBC, Cantor, Goldman Sachs, and Citigroup. However, the vast majority maintained a buy rating—the core logic being “orders are filled until 2028, with no immediate concerns regarding fundamentals.” The average target price from 13 investment banks is about $260, indicating around 50% upside from the pre-market price.
On the topic of who can succeed Jensen Huang, Seaport’s Jay Goldberg wrote in a report—“In short, no one can fill Jensen's leather jacket.” (No One Can Fill Jensen's Leather Jacket). With 60 direct subordinates, there are virtually zero successors. Bernstein analyst Stacy Rasgon lamented, “Where is he supposed to find the time?”
The real concern is that the AI ecosystem financing system built by Jensen Huang will come into question after his departure.
Goldman Sachs: Departure is Meaningful but Manageable—Like Apple After Jobs
Goldman Sachs chose to wait until the press release was officially issued before commenting. Analyst James Schneider characterized Huang's departure as “a meaningful but manageable negative event.”
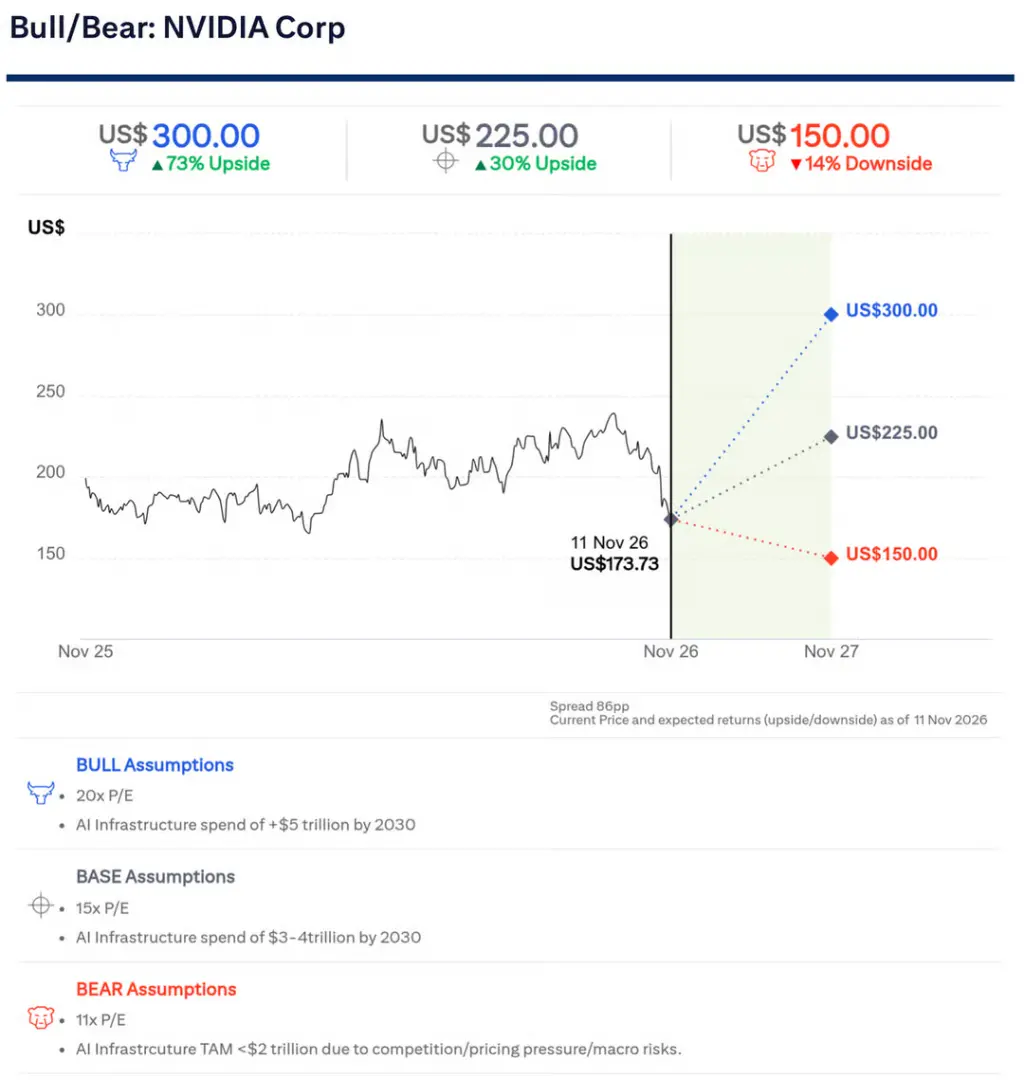
He maintained a buy rating but lowered the target price from $300 to $220. His valuation logic is evident: the EPS forecast remained unchanged at $10.00; however, the valuation multiple decreased from 30 times to 22 times due to decreased visibility and increased execution risk during the management transition.
To summarize the sell-side consensus in one sentence: E (earnings) remains unchanged, P/E (valuation multiple) has been significantly reduced.
Schneider compared this event to Apple's loss of Jobs. For approximately 18 months before and after 2011, Apple’s forward P/E fell from about 17 times to 12 times, eventually touching a low of 9 times in 2013, before the market confirmed that the iPhone machines did not stop working after Jobs' departure, gradually increasing the valuation back to around 15 times.
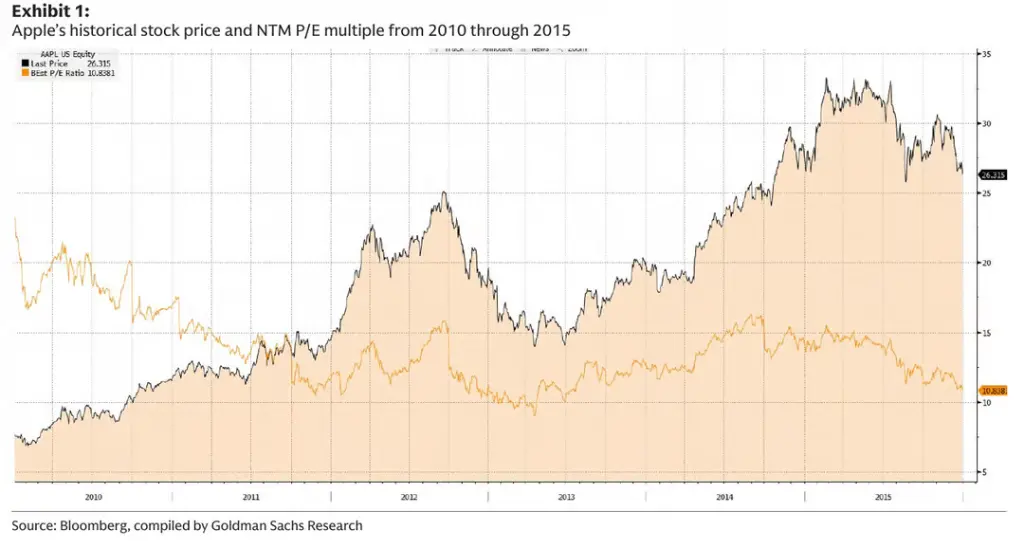
Schneider believes that NVIDIA's market will undergo a similar “search for a reasonable multiple” process until the leadership and business momentum regain clarity.
However, Schneider himself admits that this comparison is not perfect—Apple had a predefined successor, no Department of Justice investigations, and no congressional subpoena threats.
Bernstein's Long-term Bull Turns: “Where is he supposed to find the time?”
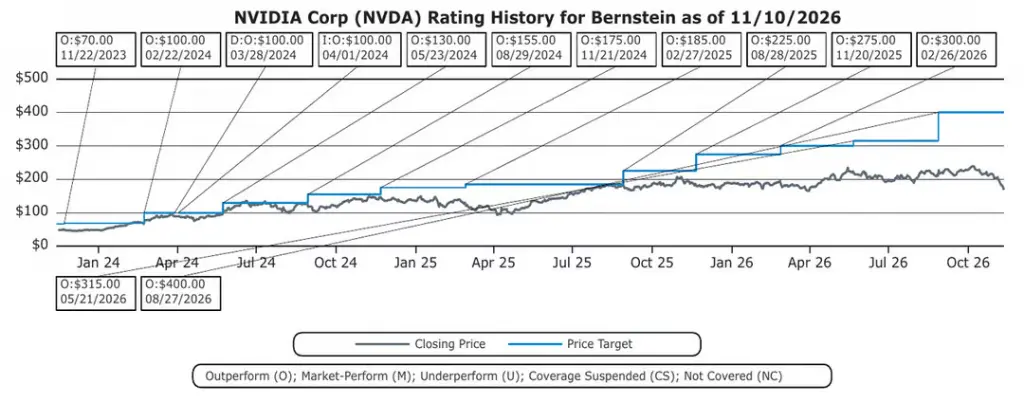
Stacy Rasgon from Bernstein has been one of Wall Street's most respected NVIDIA bulls for years. This time, he downgraded the rating to market perform and cut the target price from $400 to $200. The report's title was just one line: “Where is he supposed to find the time?”
He wrote:
New allegations make us feel that the board can no longer allow him to stay in this position (we have seen other CEOs fired for far lighter things...). If the board does not take action now, the subsequent risks will only increase, as more allegations seem to be on the horizon.
He also used a metaphor, which might be the most memorable line for NVIDIA holders this week:
If you find two ants in the kitchen, the best estimate of the total number of ants in the kitchen is definitely not two...
The implication: more allegations, more investigations, and what new discoveries the new leadership might find—uncertainty is far from bottoming out.
“Sold Out Until 2028”—Core Argument of Bulls
Bernstein, KeyBanc, and William Blair opted to downgrade NVIDIA; Bernstein, JPMorgan, RBC, Cantor, Goldman Sachs, and Citigroup all lowered target prices, with reductions ranging from $60 to $200.
However, the average target price provided by 13 investment banks still remains around $260 (median $250). Both Wedbush and BNP Paribas set their target prices at $345, which is more than double the pre-market price.
The majority of firms still maintain a buy rating. The only sell rating came from Seaport’s Jay Goldberg, with a target price of $180—ironically, this price is still higher than the market price now.
So, why are almost all still bullish?
The bull logic boils down to one point: Jensen Huang is gone, but the orders remain.
Piper Sandler's David O'Connor (overweight, target price $300) made it very clear:
The platform and architecture decisions for the next two generations of products have already been made, and the company’s orders for 2027 are sold out, with 2028 largely the same. What we are discussing with clients now are matters for 2029 and beyond.
Chris Caso from Wolfe (outperform, target price $275) was even more direct:
If the CEO is required to step down, we believe that for at least until 2028, the fundamentals and earnings will remain completely unaffected—because NVIDIA is basically sold out during this period. The CEO transition will not impact orders or even the product roadmap, which has been clearly planned beyond 2028.
RBC estimates that current demand exceeds supply by about 50%. JPMorgan pointed out that the mass production ramp-up paths for Vera Rubin, Rubin Ultra, and Feynman have been clarified.
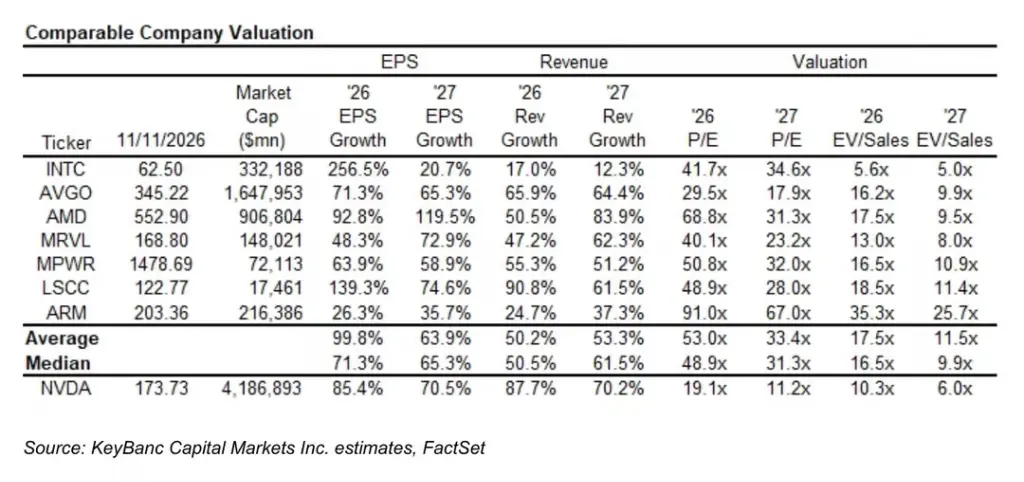
In other words, E is fine; the only thing moving is P/E. Moreover, there is very little multiple left to compress: at Wednesday's close, NVIDIA's expected P/E ratio for 2027 was about 10 times, which Piper referred to as a 20-year low, and William Blair called it a historical low (only 7 times based on the 2028 consensus earnings).
“No one can fill Jensen Huang's leather jacket”: 60 direct subordinates, zero successors
If the next two years are safe, what does Wall Street genuinely worry about?
A major concern is the organizational structure. Seaport's Goldberg characterized it in one sentence:
Simply put, no one can fill Jensen's leather jacket. no one can fill Jensen's leather jacket
He acknowledged that there are many executives capable of running NVIDIA, but no one carries the same weight across the industry. The problem is both personal and structural:
This island-like structure will lead to any internal candidate diving deeply into their respective fields, while being completely unaware of the majority of the other businesses. This will not be a permanent obstacle, but it will take many quarters to reorganize the company around a new leader. Moreover, it will be a different company—competent, but far less vibrant than it is now.
Wells Fargo provided a number: about 60 executives report directly to Jensen Huang. Analyst Quatrochi stated that this structure is “unsustainable and cannot be replicated,” and it may impact the speed of coordination and time to market for products.
As for the list of successors, the most frequently mentioned internally is Ian Buck—who has worked at NVIDIA for 22 years, is responsible for large-scale and high-performance computing business, and is widely regarded as the creator of CUDA, with Piper describing him as "well-regarded by investors." William Blair also added Jonathan Ross (founder of Groq, TPU architect, who just joined NVIDIA in December last year). Regarding external candidates, media reports have mentioned Apple's Cook, AMD's Su, Arm's Rene Haas, and Micron's Sanjay Mehrotra.
JPMorgan divided this issue into short-term and long-term dimensions:
We believe that the most critical question for stock prices in the near term is whether NVIDIA's board can successfully form an interim management team capable of maintaining the company’s strong execution and continuing to advance the existing roadmap. However, beyond the next 2-3 years, the focus will shift to whether the management team possesses a forward-looking vision and can identify the next inflection point in the accelerated computing space and build a comprehensive system encompassing not just chips, but also ecosystem and platforms.
In other words: a temporary team might still be able to send out the Rubin product line; but predicting the “next CUDA” a decade in advance is the true reason for this company to become a $5 trillion valued entity.
Wedbush examined historical precedents: Marvell (which thrived under an external CEO after the founding family exited), Apple (where Cook excelled under an existing succession plan), HP and Intel (both abruptly lost CEOs due to executive misbehavior without ready successors, subsequently falling into what Bryson called "catastrophic periods").
However, Wedbush's conclusion is that there is no single case that fully fits the current situation:
In this case, uncertainty may further escalate because we cannot think of any historical precedent meeting all of the following conditions: a founder CEO who has a comprehensive dominant influence on the company direction, a company (and its CEO) that is so pivotal in technology and technology policy, and the absence of a clear succession plan during the transition period.
NVIDIA is the “central bank” of AI, and that bank only has one credit officer
Another major concern on Wall Street is: what about the money?
NVIDIA is not just a chip-selling company. Over the years, Jensen Huang has continuously injected NVIDIA's free cash flow—about $50 to $60 billion every quarter—into the entire AI ecosystem: equity investments in OpenAI, Anthropic, xAI, providing asset backing to emerging cloud computing companies like CoreWeave, and pre-paying and holding shares in fiber optic device suppliers like Lumentum, Coherent, and Corning.
UBS's Tim Arcuri placed it at the top of three major influencing factors:
NVIDIA has become a key source of funding for numerous AI industry participants, including emerging cloud service providers, large language model developers, ecosystem partners, and suppliers. We have always believed that Jensen Huang is the driving force behind this effort. Even if the new leader ultimately maintains a similar approach, a 'pause period' is very likely to occur… We estimate NVIDIA generates about $50 to $60 billion in free cash flow each quarter, a large portion of which is being looped back into the entire system. This could easily withdraw $50 billion or more from the system—and this is happening at a crucial time when interest rates are rising, and liquidity is tightening in certain areas of the credit market.
William Blair's conclusion is more direct, and this is the core reason for its rating downgrade:
Existing contracts will continue to be executed after the CEO transition, but the real risk lies in the next round of deals—and NVIDIA's ability to defend its market share in 2027 and beyond. Without Jensen Huang, or if he is severely restricted due to investigations and reviews, we believe NVIDIA may open a larger gap for competitors like Broadcom and AMD.
Seaport's Goldberg went further, pointing out that a $500 billion financing platform plan announced by Jensen Huang two months ago, involving six private equity funds, has yet to be finalized. He believes that without Huang, this plan may very well dissipate.
On the day the news broke, CoreWeave's stock fell over 11%—ironically on the same day it was promoting a more than $4 billion investment-grade loan to the market.
Government investigations have not disappeared with the resignation
Jensen Huang's resignation does not mean regulatory pressure has eased.
The independent board investigation chaired by Wachtell law firm Joon Kim is still ongoing, the Department of Justice’s Megaspeed investigation is still in progress, and the House of Representatives is requesting a closed-door briefing on November 18, with Senators Warren and Coons demanding related records.
Two investment banks quantified this into specific financial assessments:
Goldman Sachs indicated that NVIDIA's FY26 report shows a total sales exposure to mainland China, Hong Kong, Taiwan, and regions outside the US of about 11%, and expects business in jurisdictions like Singapore to face more scrutiny.
UBS believes that stricter rules may impact shipments to places like Singapore and Malaysia, estimating that about 10% of revenue is at risk.
RBC pointed out that China accounted for about 1% of data center revenue in the last quarter and has been excluded from the performance guidance.
Wolfe, on the other hand, holds a different view, arguing that export concerns are exaggerated, as the shipments of AI chips to China have already been minimal.
NVIDIA's Pain, Competitors' Opportunity
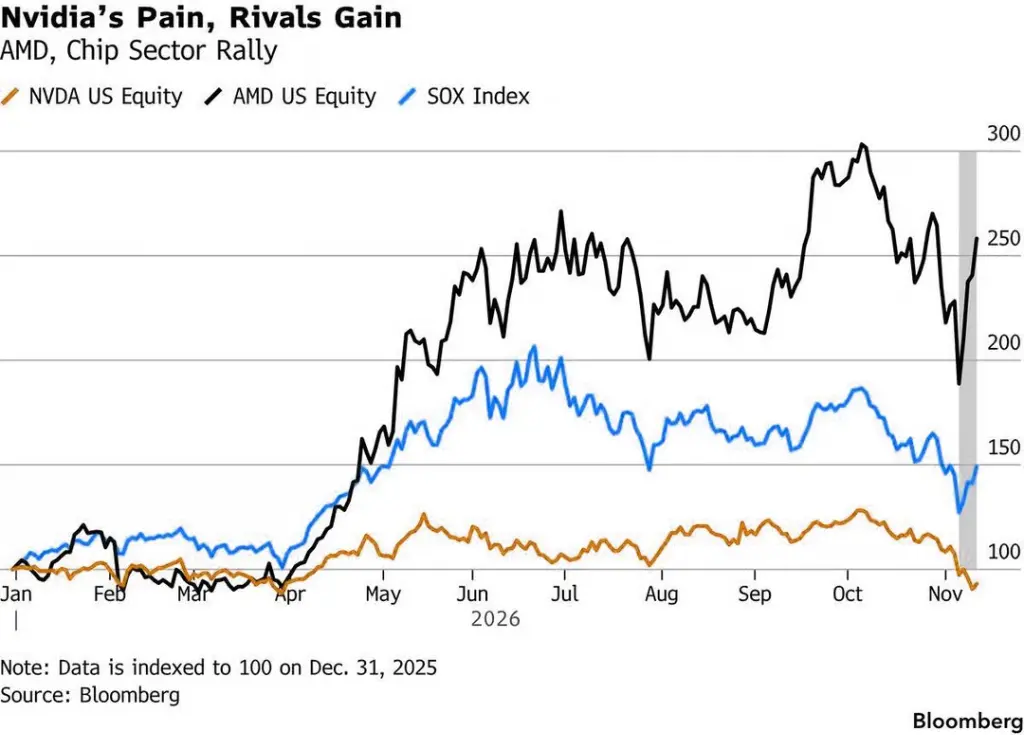
Almost all firms agree on one thing: competitors will benefit.
BNP Paribas, Seaport, and William Blair all named AMD and Broadcom as the most direct beneficiaries, as hyperscale cloud vendors and AI laboratories now have more reasons to diversify their chip sources. BNP Paribas expects that by 2030, custom chips may account for nearly three-quarters of AI accelerator shipments.
William Blair also pointed out a deeper logic: the moat of CUDA is essentially built on the high costs of porting code to other chips. However, now, AI programming assistants are rapidly lowering those porting costs. Anthropic noted in its IPO roadshow materials that previously it took 6 to 12 months to get a new accelerator up and running, while its Claude Mythos Preview model reportedly took only about three days to achieve prompting on AMD MI355X.
Analyst Naji cautiously noted that this case is rather limited. But in the same week that the founder departed, such news spread, which is inherently intriguing.
Everyone Points to the Same Bottom
So where is the stock price bottom?
The answer from Wall Street is surprisingly unanimous—and based on experience, this consensus itself is not a good omen.
Cantor believes that a multiple of 9 times the expected EPS for 2027, corresponding to about $150, is a reasonable bottom. Piper set $150 as the support for a 10 times cyclical bottom valuation. KeyBanc's bear case scenario is also $150. Citigroup is similarly aligned, corresponding to an 11 times valuation.
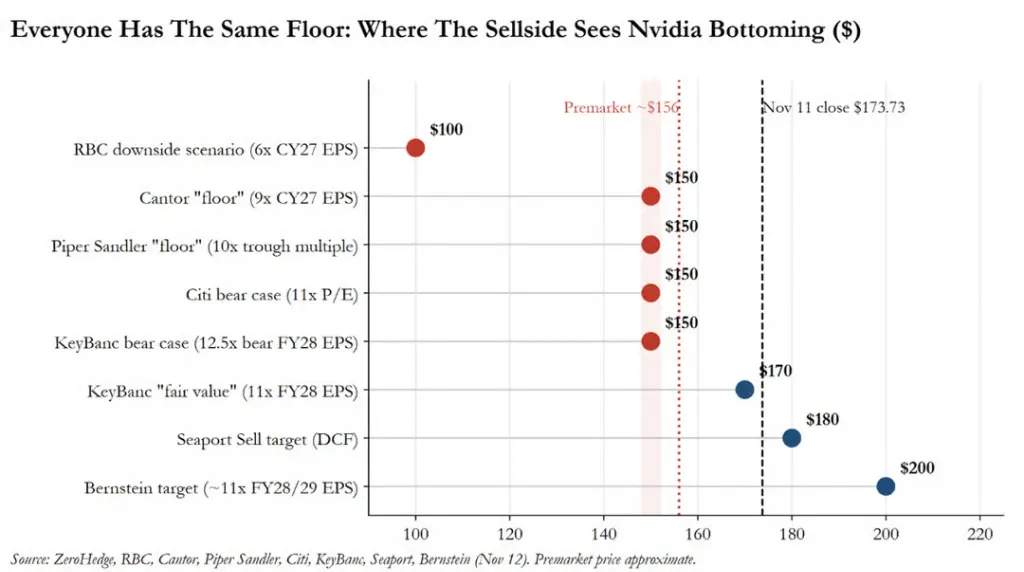
The pre-market stock price of $156 is only a 4% buffer away from Wall Street's consensus bottom. The only lower target is given by RBC, with a bear case of $100, corresponding to 6 times the expected EPS for 2027, which is below NVIDIA's five-year historical valuation low.
Goldman Sachs refused to provide a bottom number and used that Apple chart to remind the market: cyclical bottom valuations can be maintained at low levels for years.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


