Today is actually a very critical time, after the Nasdaq's sharp drop last Thursday, it is roughly around the annual line.
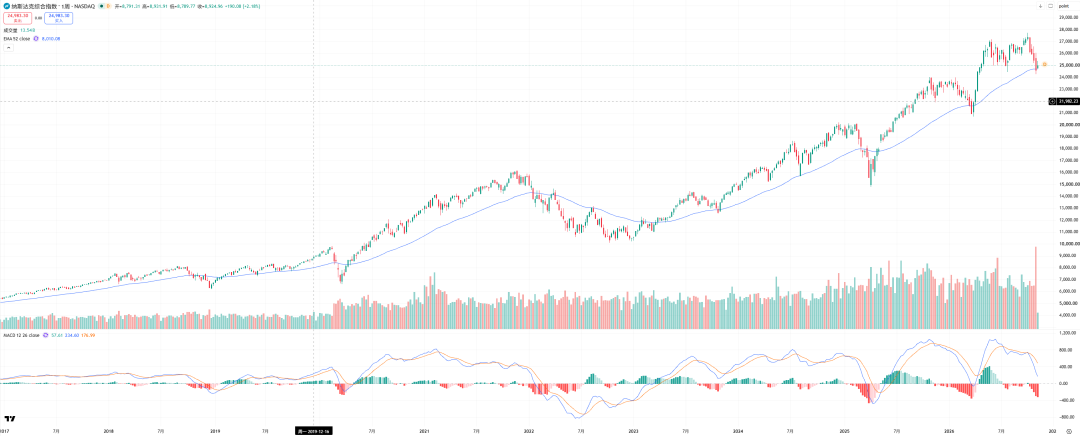
In the past decade, the Nasdaq has been below the annual line very rarely; it has happened during two rate hike cycles: in 2018 when Powell mentioned leaving monetary policy space for the future, and in 2022 during the interest rate hikes to combat inflation. Shorter periods include several crises, March 2020, April 2025.
Therefore, it is very simple; here the bearish view hinges on either the belief that there will be a period of sustained interest rate hikes, or on the perception of risk events similar to March 2020, April 2025, or March 2026.
This morning, my thought was that as long as today's CPI reading meets expectations, I don’t even need it to be lower than expected; I would be willing to risk on here. And frankly, when I saw Waller's speech, I genuinely thought he was expecting a lower than expected CPI number.
I had even planned that if the inflation data came in a bit lower, the risk of Fed rate hikes would ease and that during a Risk on phase, I thought gold would rise alongside risk assets. But this unexpectedly high inflation figure complicated matters a lot.
In the past, when stocks bounced back from such positions, it wouldn’t be too complicated, so the current mindset has shifted to whether, in the next three trading days, if the trading volume amplifies + the rise is relatively healthy, then we could talk about Risk on, rather than expecting data to bring about a shift in expectations early this Tuesday morning. I feel like today the market is a bit confused.
If U.S. stocks remain close to this annual line this week, I will become more cautious about the future; U.S. stocks typically do not linger too long at such critical positions. Once they hesitate at such levels, there are often some strange occurrences later.
So let’s wait; if these three days show better technical patterns and higher trading volumes, there may still be much bullish space ahead. If it doesn’t rise in these days or if it is still in a range next week, then I think it will be hard to say what happens next.
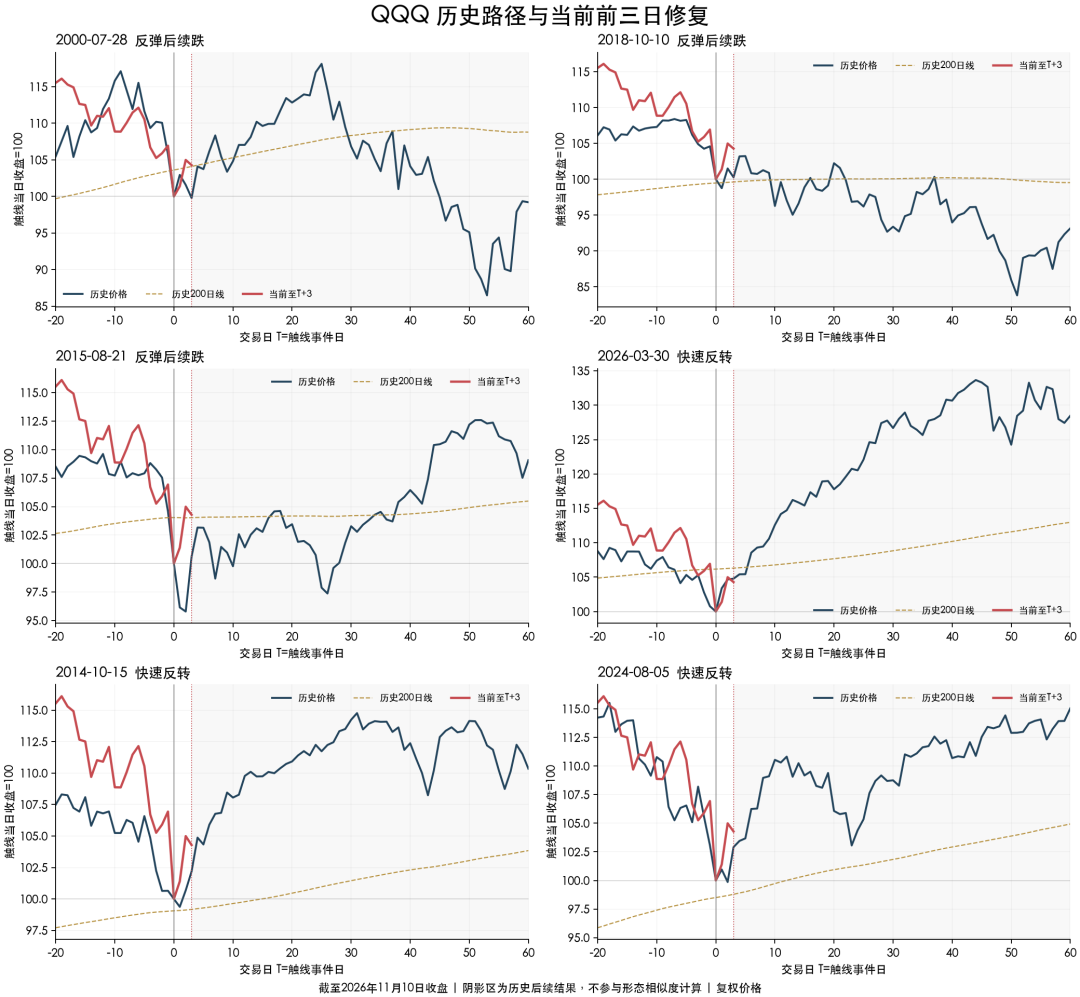
Some comparisons near the annual line show that when it breaks below the annual line with substantial trading volume, a subsequent reversal often requires external help, and if trading volume does not recover, the trends in July 2000, October 2018, and August 2015 become more likely.
From a macro perspective, I believe the Fed has already stated its position; the rate hike in December is basically a done deal. Previously, I thought that after a drop in U.S. stocks, if the Middle East had hope for resolution, even if the Fed raised rates, it could still adopt a more dovish stance regarding future hikes in December. But to be honest, faced with the current employment and inflation situation, as Waller said, it is understandable that some FOMC members support a 50bp hike.
I want to add that I understand Waller’s remarks. He set a tone that there would be an option for a 50bp hike among the three options (A, B, C) presented by Warsh to the committee in December. This implies that a 25bp hike has become a certainty. As long as U.S. stocks don’t crash from today until December, we will see a rate hike in December.
Moreover, it wasn't just Waller speaking today; several Fed officials expressed hawkish views. I believe they do not want to repeat the errors of 2024-2025 by lowering rates before inflation is under control.
Disregarding the technical analysis aspect, this is absolutely the situation you least want to see: the current state is good, but the outlook is deteriorating, while the Fed indicates that inflation limits rate policy.
Today, the U.S. Treasury yield curve clearly flattened; positively, this indicates a restoration of confidence in the Fed, while negatively, it suggests that people no longer think the U.S. economy has sufficient resilience.
To summarize, my previous caution about copper, including the belief that gold might be at a bottom but uncertain if the second leg is lower than 3850, is based on the premise that both the Fed and the government are targeting inflation as their objective. I see no need to go long on base metals while the Fed is trying to lower inflation, but I did indeed hope this morning that if inflation was a bit lower, it would lead to a favorable scenario where the Fed raises rates in December but expresses a dovish stance, and inflation weakens alongside expectations of the end of war.
I believe that hope has diminished; it may still require enough patience to await the economic turning point, which is when inflation needs to fall to a level that satisfies the Fed before they will turn towards supporting the economy.
As for copper, the macro selloff of the past few weeks might have positioned half of the total holdings.
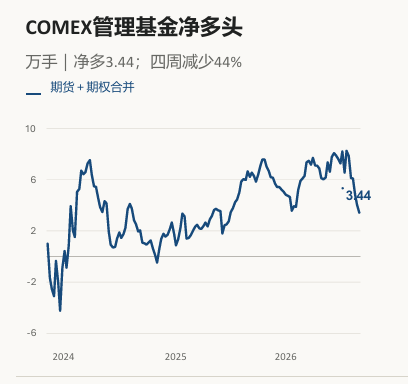
If there are no good macro news today, then this net long position may not necessarily stop declining, or you have to see U.S. stocks stabilize before asserting that this net long position will hold steady. For copper in 2027, I believe the trading logic in the first and second halves might be
- In the first half, the core narrative centers around China's inventory story under low stocks.
Of course, there are issues related to tariffs, macro factors, and timing, which need to be discussed one by one. However, while China is replenishing inventory, as long as U.S. tariffs remain, the macro trading headwinds will end, and buying copper on dips should be fine.
- But in the second half, the core narrative might shift to demand stories following a global economic slowdown. If the Fed considers a 50bp option at the December rate hike, then I believe the chances of rate cuts in H1 next year will significantly diminish.
I think during the next Fed rate-cutting cycle, copper is likely to fall. The year 2024 will be the only one in the past 40 years where copper rose significantly during a rate cut, and this is one of the points I am most proud of, whether in the forced squeeze in the first half of 2024 or the rise after the rate cut in the second half of 2024, I did not get stuck in historical experience. At a time when everyone thought buying copper in a rate-cutting cycle was foolish, I did not short it.
And today, I think many friends may feel that buying copper during a rate-cutting cycle is reasonable, but I believe that the rate-cutting cycle in 2024, whether due to tariffs or industrial narratives, may be non-replicable. When manufacturing PMI is not low globally, I feel that if a rate-cutting story arises in 2027, copper may fall at that time.
I do not think copper is at a very low position in a cycle. Here, I would like to quote a friend's perspective Cross-metal Cycle Research (1): A New Perspective on Determining Metal Cycle Position to redraw the diagram.
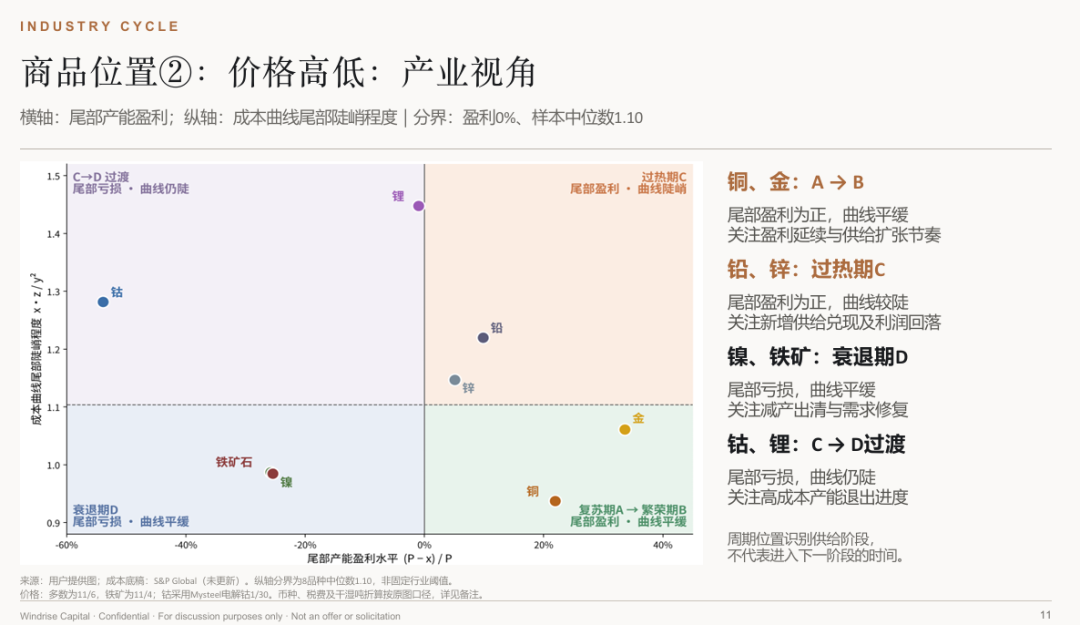
If you ask me what I most want to see among base metals in the next few years, I think if lithium carbonate prices can drop below 80,000 and nickel stays below 16,000 USD, these two things in my eyes hold much greater attraction over 3-5 years compared to copper at 13,500 USD.
I believe I have said enough about gold, so I won't repeat myself. The reason I was hesitant to take a heavy position earlier was out of fear that the Fed would give you a rate hike in December, and currently, it seems this probability is already a done deal; gold is certainly not at the best moment now.
To conclude with gold, I initially expected today's CPI to be a bit lower, allowing U.S. stocks to take on more assets Risk on, but it seems this idea has fallen flat, and in the coming days, further watching may be necessary. It is not immediately time to go Risk on.
Finally, we have arrived at the chit-chat moment. Recently, I've been observing Xu Fei and Li Na. Xu Fei was also a singer I really liked; I think their relationship is very sincere. I have always held a view that may not be accepted by most people, which is that I believe kinship, romantic love, and friendship are entirely the same in the end. I think the deepest emotions of a person are quite similar and cannot distinguish the objects. It is merely the form of expression that differs.
Digressing, I think people should pursue and enjoy such genuinely sincere emotions, which is a very beautiful thing in life. One day, you will realize that having a family member, partner, or friend whom you can trust and love unconditionally is a very wonderful thing. This may bring you more happiness than money, status, or honor.
I originally wanted to title this section "Once the seas have been changed, the water cannot be the same," but I feel that this poem is too pessimistic. Yan Jidao's poem expresses a similar sentiment, but there is a sort of nonchalance amidst the sadness. I indeed wish to express this sentiment, just like this pair of friends: when you encounter a wonderful friend when you are young and invest a lot of sincere feelings, the advantage is that you will probably never be deceived in matters of the heart again, but the downside is that you may never have such sincere feelings again.
I have been extremely fortunate in this regard; whether in family ties, romantic love, or friendships, I have no regrets. I have truly experienced the help of these sincere emotions. This is certainly often due to my good luck, but I also have some small tricks that I think can help everyone.
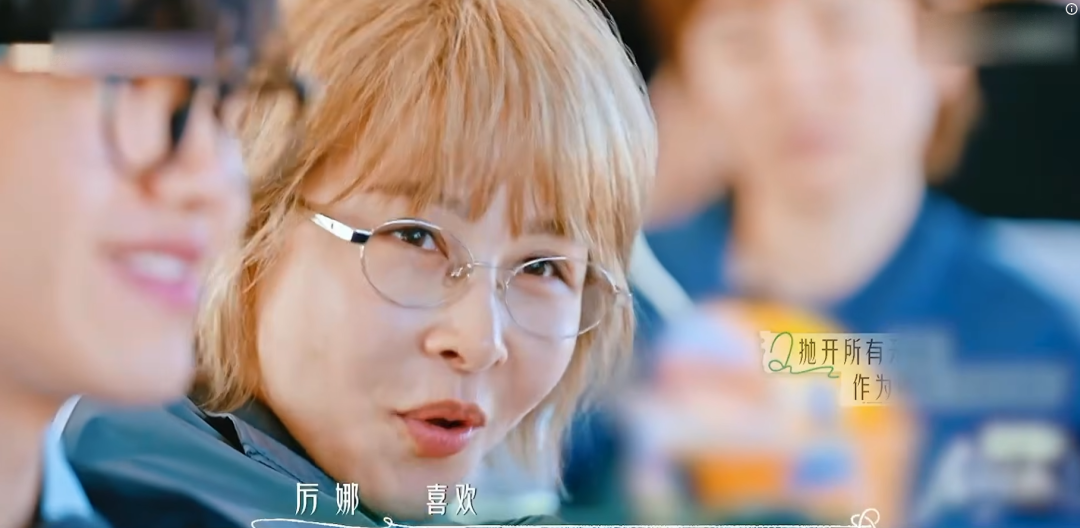
The first is to be brave in expressing love and praise to your family, partner, and friends, just like Li Na had Xu Fei tilted her head. When asked if she likes the current Xu Fei, she hesitated for a moment and then firmly said yes.
Many friends who work with me know that I am a person who praises others. In fact, I am even more so when I am with family and friends. This stems from my parents praising me since childhood; many years later, I discovered that my knowledge is actually secondary, and this habit has helped me far more than my intellect and abilities.
The second is to treat people differently; do not bring a spirit of public ownership into family and friend circles. When my friends have conflicts with others, I generally support my friends unconditionally, unless it’s truly something that warrants universal condemnation. In our Chinese tradition, subordinates praise superiors more and subordinates support superiors more, rather than the other way around. Therefore, many times, people are unwilling to praise or support their friends because there is a kind of barrier, making it seem as if they are lower in status. I think this is something that needs to be overcome.
The most fitting image to accompany this is
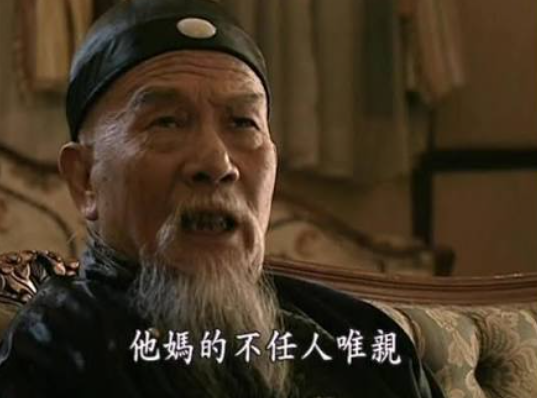
But Li Na’s view on this issue is completely in line with Zhongtang’s.
In friendship and love, people are always attracted to those who are different from themselves, but they often trust those who are similar to themselves. So if you can meet a person who is completely different from you when you are young, and your trust is built not because of your similar personalities but because of the many experiences you shared as childhood friends, then you will possess a perfect friendship or love.
Thus, when literary youth and illiterate youth go through too many beautiful experiences together, it will turn into an unforgettable bond for a lifetime.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


