Author: ChainCatcher
Overview
In the third quarter of 2026, Bitcoin rose by about 43%, yet the crypto primary market continued to cool down. RootData recorded a total of 199 financing transactions, with a disclosed amount of $4.46 billion; the number of transactions has now decreased for four consecutive quarters. However, the market has not stalled, with significant changes in the direction of funds and the investors involved.
VC activity has greatly cooled down, with transaction counts decreasing by 5% quarter-on-quarter, and disclosed amounts down 24% quarter-on-quarter.
Funds are flowing towards later and strategic rounds, with strategic rounds and private placements reaching about $1.75 billion, whereas early rounds obtained only about $730 million. Excluding the issuance from listed companies, IPO / de-SPAC, mergers and acquisitions, token public offerings, OTC financing, and debt financing, this quarter saw 144 equity financing transactions with a disclosed amount of about $3.38 billion, up 12% quarter-on-quarter and 35% year-on-year.
The corresponding equity financing transaction count decreased by 14% quarter-on-quarter and 36% year-on-year. The total amount decreased by 74% year-on-year, primarily due to the high base from the issuance and IPO of listed companies in the third quarter of 2025.
The median amount has rebounded, but large transactions have decreased. The median disclosed amount rose from $6 million to $8 million; transactions over $100 million fell from 17 to 13, while the share of the top ten deals dropped from 62% to 57%. The most notable decrease was in disclosed smaller transactions below $5 million.
Funds were mainly invested in centralized financial companies such as exchanges and brokerages. CeFi recorded 31 transactions, accounting for 32% of the disclosed amounts; DeFi had 51 transactions, the highest number, but only secured 8%.
The amount of transactions solely involving crypto native capital has decreased by nearly 60%. The disclosed amount for such transactions dropped from $2.57 billion to $1.05 billion; transactions with traditional finance or general capital participation increased from 39% to 45% in share.
The outlook for the next round of financing is pessimistic. This quarter, only 3 new crypto venture funds completed fundraising, totaling about $1.3 billion, the fewest new funds since Q3 2019.
Bitcoin Price Rises, Primary Market Cools
This quarter, RootData recorded a total of 199 financing transactions, of which 116 disclosed amounts, totaling $4.46 billion. The number of transactions decreased by 5% from Q2, and the amount fell by 24%; compared to a year ago, the amount decreased by 74%.
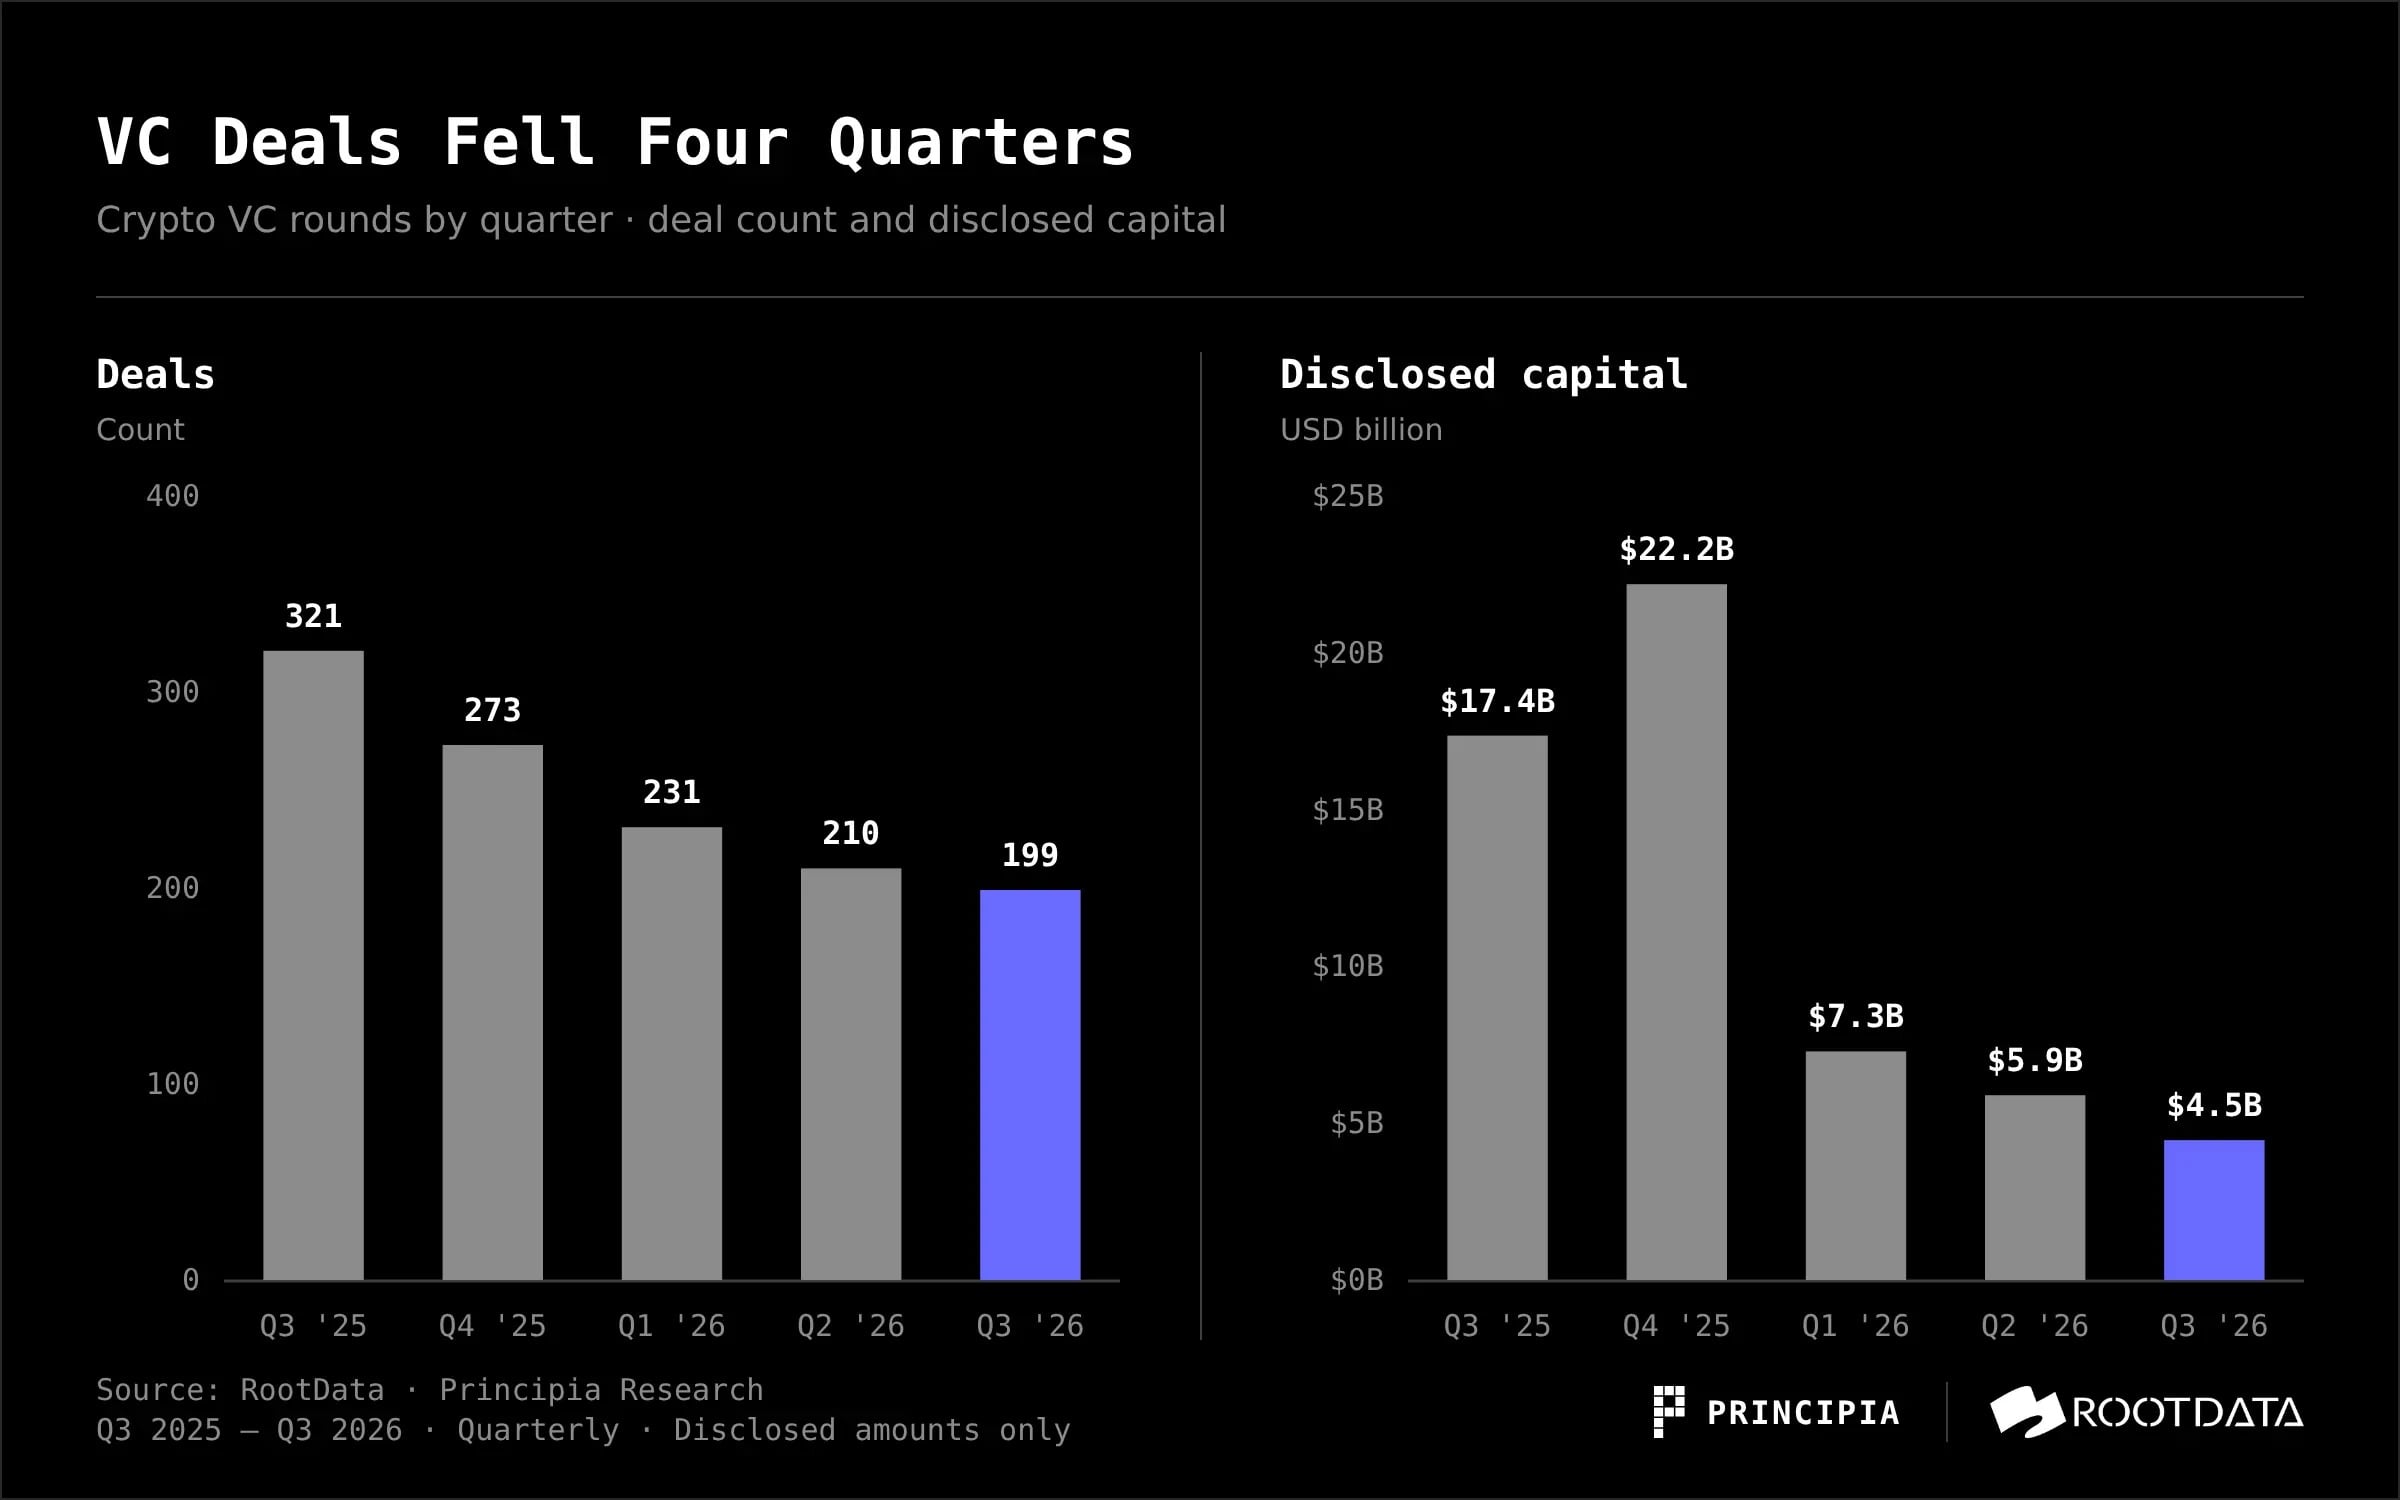
Figure: Changes in the number of crypto VC financing transactions and disclosed amounts quarterly from Q3 2025 to Q3 2026 (Source: Principia Research & RootData)
In the base of Q3 2025, there were a large number of listed company private placements and IPOs: Strategy raised about $2.52 billion, Forward Industries about $1.65 billion, Galaxy about $1.4 billion, and Bullish IPO about $1.11 billion.
After this wave of "coin-stock" financing, there was a significant year-on-year decline of 74%. The $22.19 billion in Q4 2025 was similar, with nearly half coming from a single $10.3 billion acquisition by Dunamu.
Looking only at equity financing, the conclusion is the opposite. Excluding listed company private placements (Post-IPO), IPO / de-SPAC, mergers and acquisitions (M&A), token public offerings, OTC, debt financing, and community rounds, and removing large stock transfers over $100 million, pre-sales of tokens, or financing for listed companies and debts that were not marked,
adjusting for this, this quarter's equity financing consisted of 144 transactions, with a disclosed amount of about $3.38 billion, higher than Q2's approximately $3.02 billion (168 transactions) and Q3 2025's approximately $2.5 billion (226 transactions), with a quarter-on-quarter increase of 12% and a year-on-year increase of 35%, while the number of transactions fell by 14% quarter-on-quarter and 36% year-on-year. There were fewer transactions, but they were larger on a per-transaction basis.
It's worth noting the divergence between the price of cryptocurrencies and financing. Bitcoin rose from about $58,600 in early July to about $83,600 in early October, an increase of approximately 43%, yet the primary market did not warm up accordingly.
We believe a significant reason is the absorption of capital by AI: the demand for funding for AI computing power and models is enormous, and market expectations for its growth potential are also higher; with limited allocation for LPs, some funds originally directed toward crypto venture capital are now shifting towards AI.
The actions of leading crypto native institutions also confirm this: on July 8, Paradigm announced the completion of a $1.2 billion fourth fund, expanding its investment scope from crypto to cutting-edge fields like AI and robotics, while stating it would continue to invest in crypto.
Additionally, IOSG founding partner Jocy Lin set up a focused AI initiative named IOSF Ventures; on October 22, a16z Crypto was renamed to a16z Frontier, with its new fund's investment scope extending to AI, autonomous machines, and other cutting-edge technologies while continuing to invest in the crypto field.
The quarterly fluctuations were mainly due to a few large deals. July was the hottest month with $2.37 billion across 72 transactions, with Crypto.com, Ionic Digital, and Securitize each receiving $400 million.
August was the coldest, with $720 million across 63 transactions. September bounced back to $1.37 billion across 64 transactions, primarily from Polymarket's $300 million and Felix's $200 million.
Funds Flowing to Later and Strategic Rounds
This season, nearly 40% of funds were allocated to strategic and private rounds, amounting to about $1.75 billion. Early rounds had the highest transaction count, but only accounted for about one-sixth of the total amount.
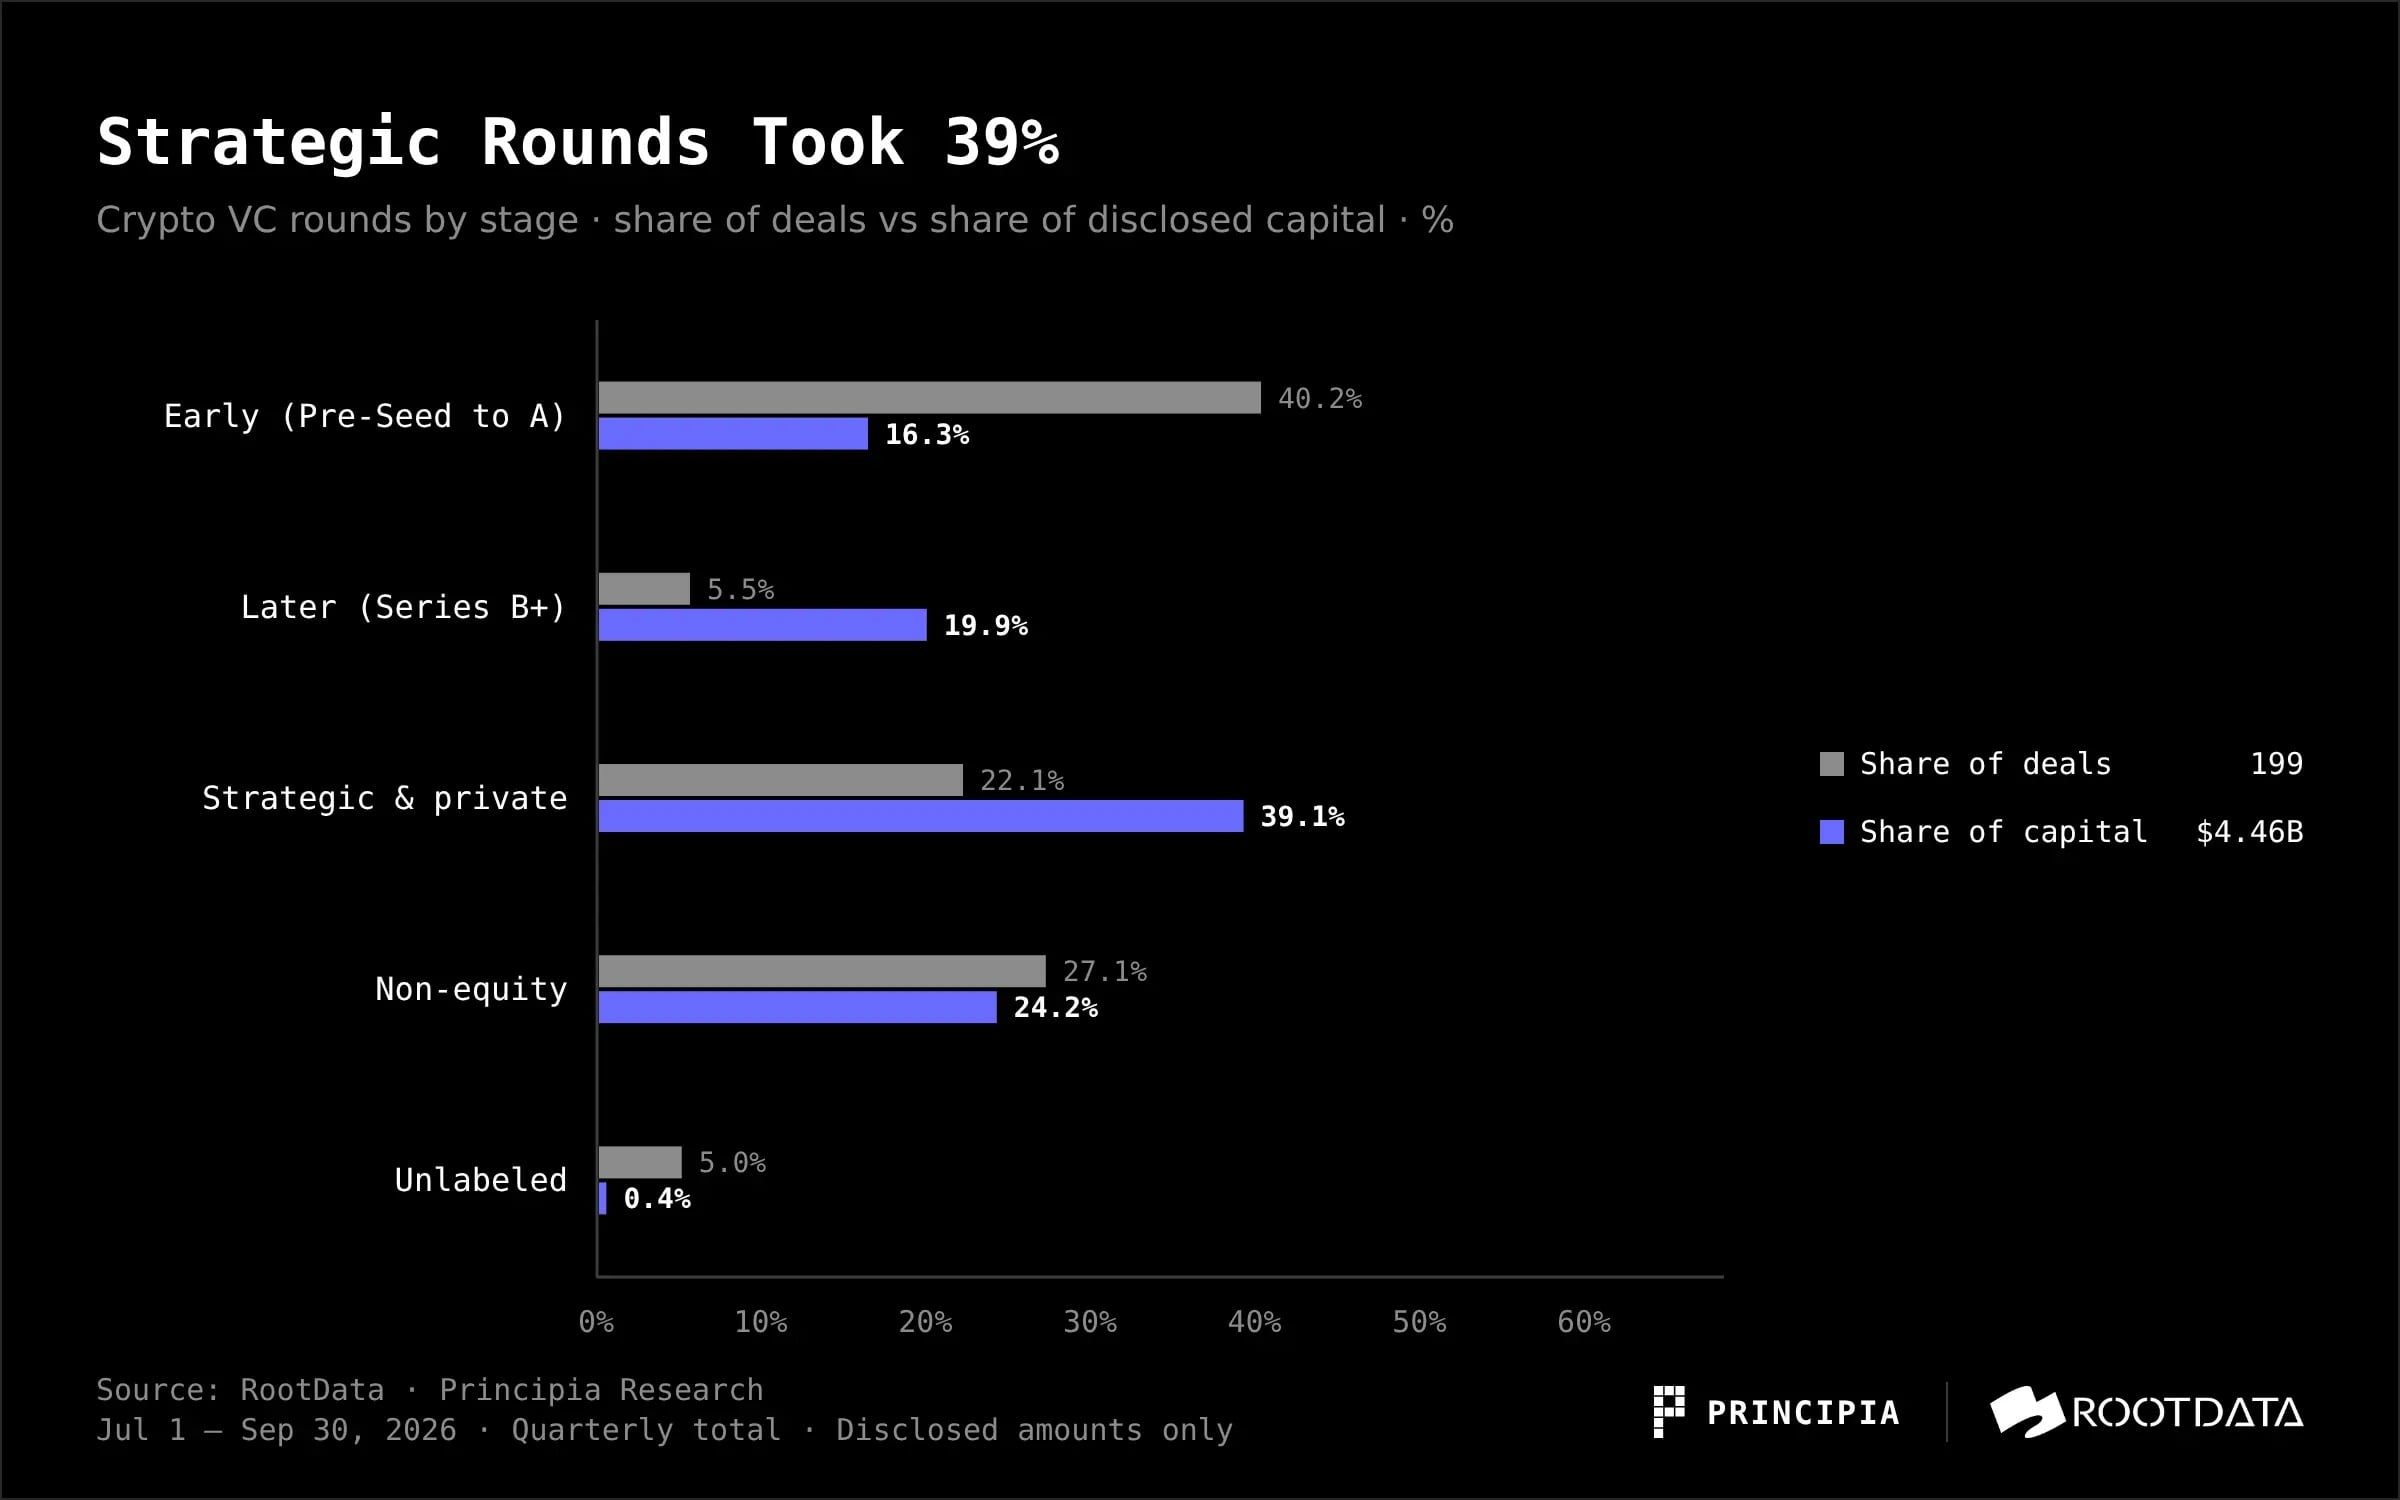
Figure: Distribution of crypto financing transactions and disclosed amounts by round in Q3 2026 (Source: Principia Research & RootData)
Early rounds remained the most active, with 80 transactions, accounting for 40% of all deals, but in terms of amounts, they were just a supporting role: transactions outside early rounds took about 84% of the disclosed amounts.
In terms of individual transaction size, there were 25 mid-range transactions between $20 million and $100 million (excluding $100 million), with a total disclosed amount of about $1.15 billion, higher than Q2's 19 transactions totaling about $770 million.
However, within this range, 7 of the transactions belonged to OTC, debt financing, public placements from listed companies, or mergers and acquisitions; looking only at equity financing, mid-range transactions amounted to 18 deals, totaling about $870 million, with the number remaining the same as in Q2 (18 transactions, around $730 million), but a growth of about 19% in amount, and still lower than Q3 2025 (31 transactions, around $1.03 billion).
This not only reflects a decrease in risk appetite but also relates to changes among funding parties: some crypto native investment institutions have ceased new investments, liquidated, or shifted to AI. In December 2025, Shima Capital was sued by the SEC, after which it was reported that the founder announced his departure in an internal email to the projects, and orderly liquidation of the fund.
In June 2026, Arbitrum DAO's gaming investment plan AGV proposed to stop new investments and manage only the existing portfolio, which was approved in early July, and approximately 143.7 million ARB tokens would be gradually returned to the DAO's treasury.
In October, Deus X Capital ceased operations and will formally liquidate on January 31, 2027, with CEO Tim Grant transitioning to become CEO of the AI company TensorX.
At the end of the same month, Verda Ventures, which focuses on stablecoin infrastructure, halted investments in new projects due to the founder joining Tether, shifting to only serve the existing portfolio.
Meanwhile, traditional finance and strategic capital are stepping in. Citadel Securities invested $400 million in Crypto.com at a $20 billion valuation.
Nasdaq's Nasdaq Ventures has agreed to invest $100 million in Kraken's parent company Payward, with a reported corresponding valuation of about $21 billion.
1789 Capital led a round of approximately $1 billion for Polymarket, contributing about $300 million, leading to a valuation of $21 billion.
Tiger Global led a $180 million Series B for Augustus; SBI Holdings led a $76 million Series C for EDX Markets and a $125 million Series C for Gauntlet.
These funds are directed towards licenses, clearing, and trading access rather than new narratives.
Tracks: Funds Buying "Financial Channels"
According to RootData's main tags, CeFi had 31 transactions this season, taking $1.44 billion, accounting for 32% of the disclosed amount, ranking first. DeFi had 51 transactions, the highest number, but only took $370 million, accounting for 8%.
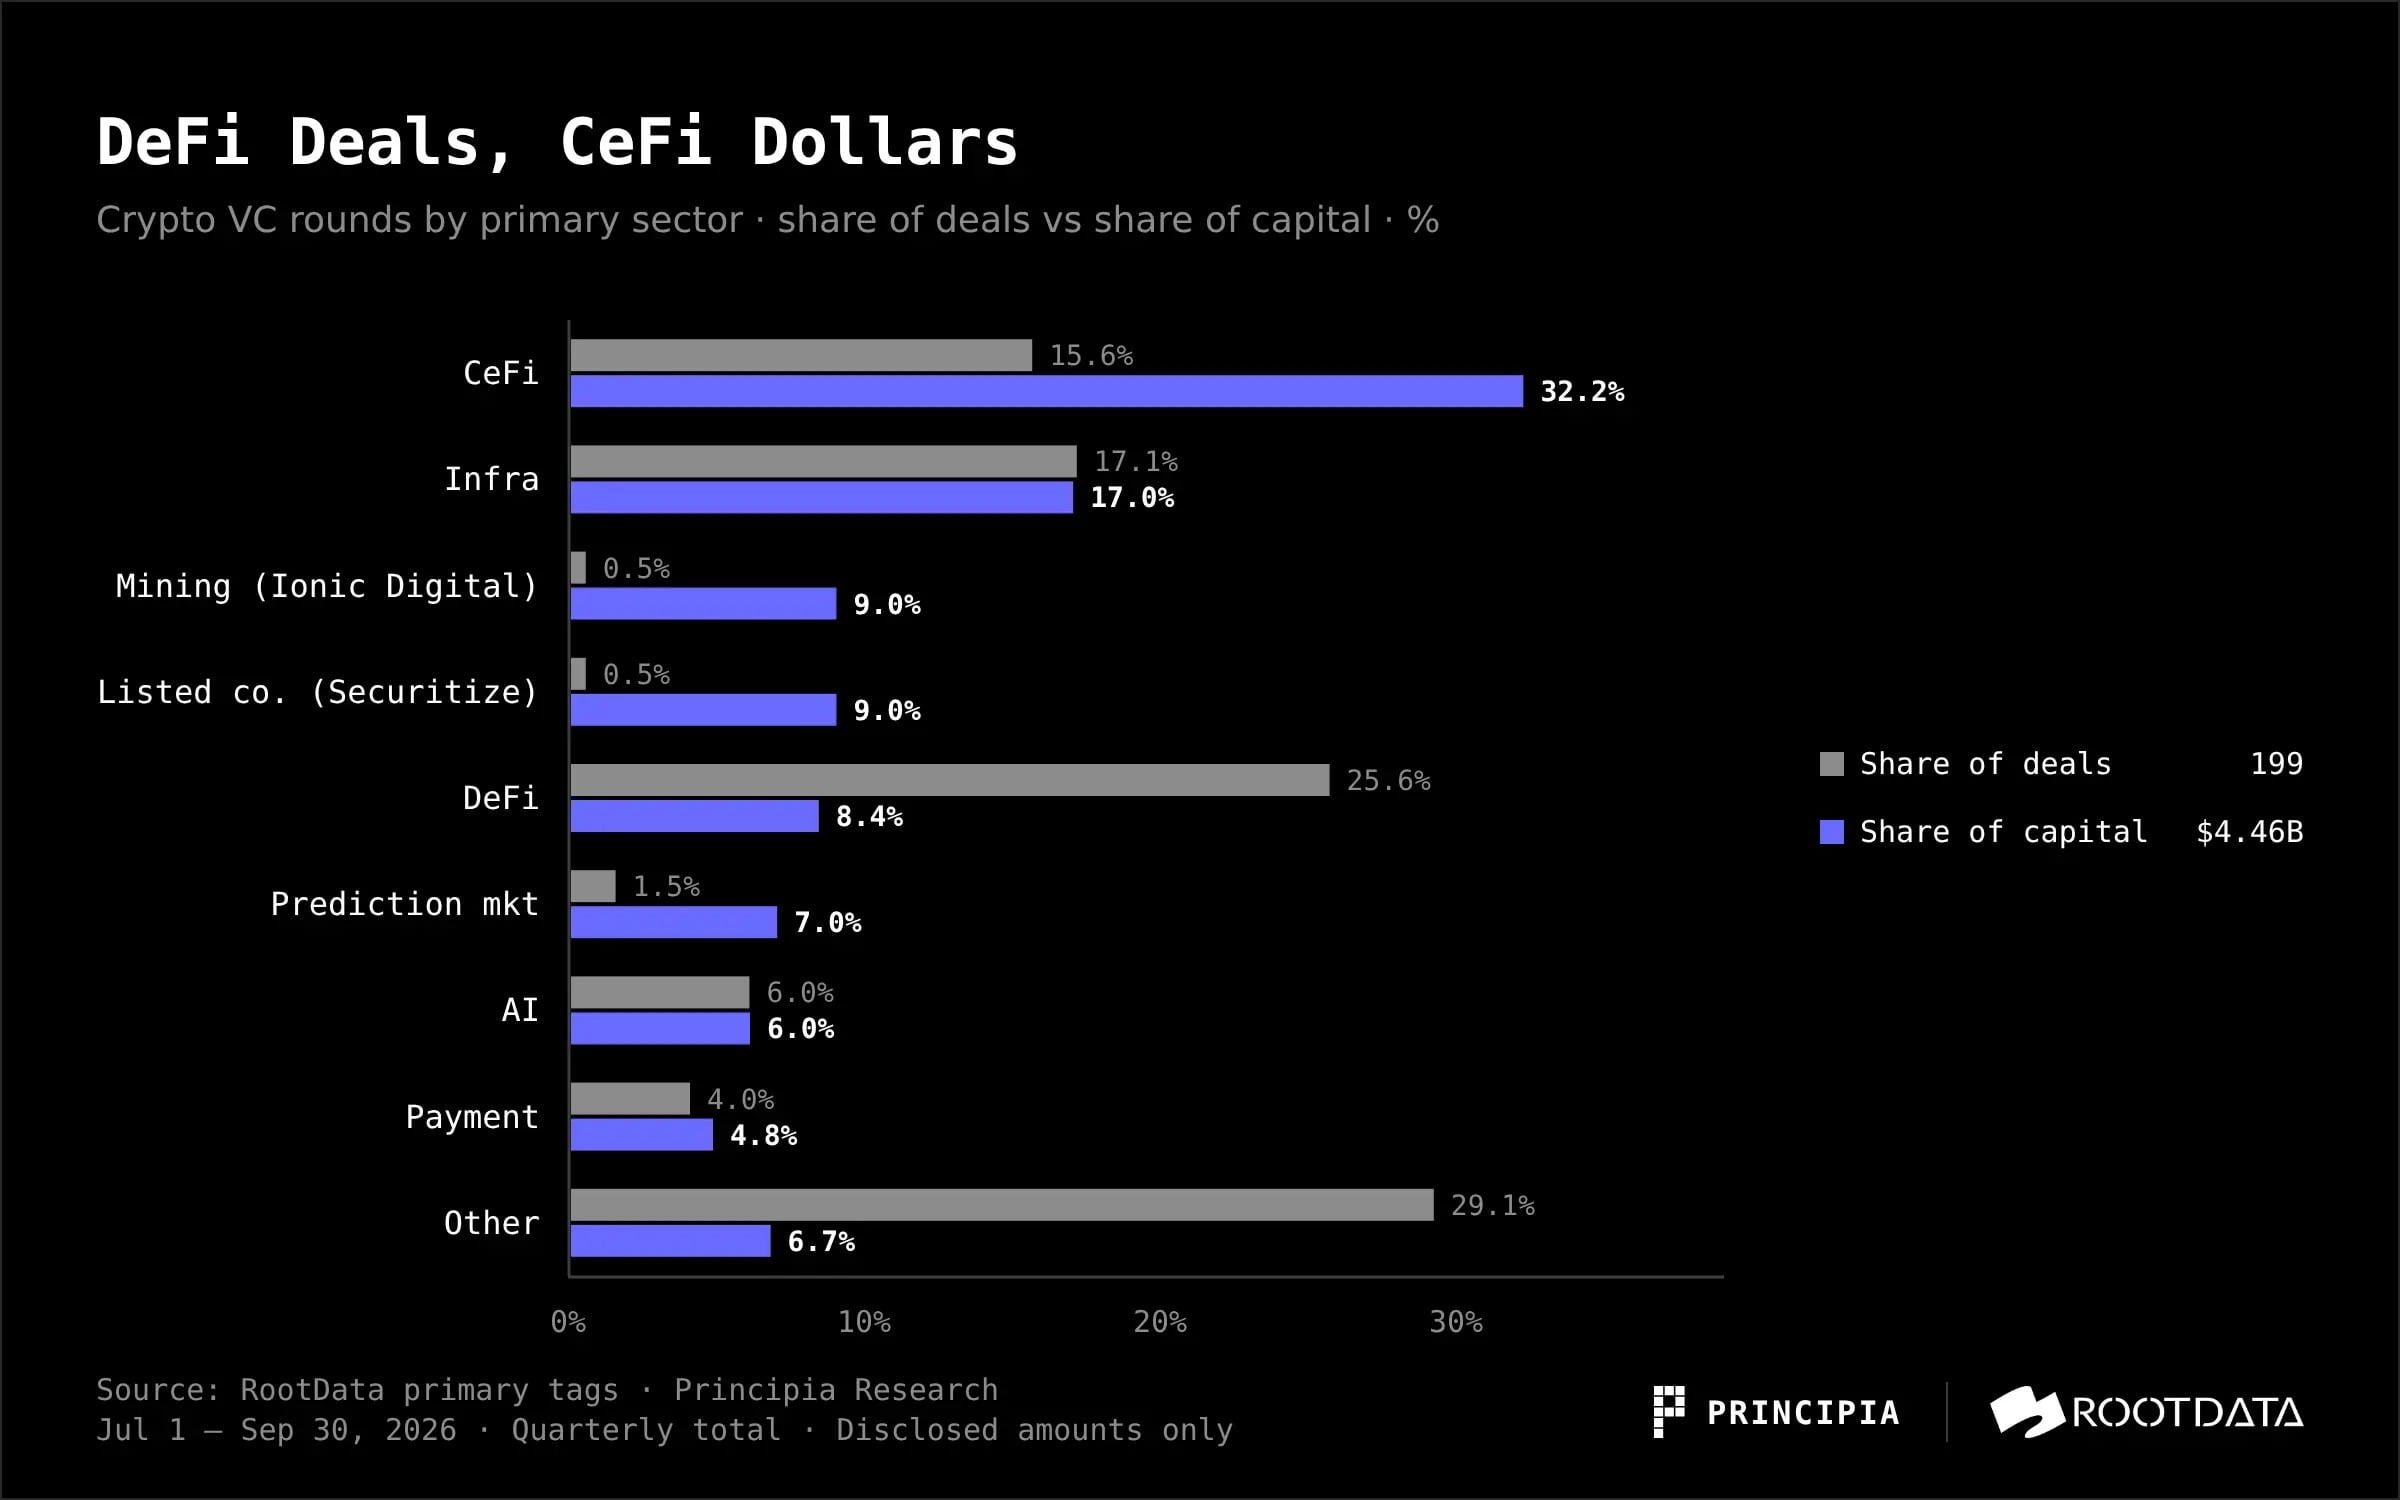
Figure: Distribution of crypto financing in Q3 2026 by main track in terms of transaction counts and amounts (Source: Principia Research & RootData)
Most of the large transactions in CeFi were related to trading, brokerage, and clearing access: Crypto.com, Kraken, Augustus, Alpaca, EDX Markets.
Infra ranked second with 34 transactions totaling $760 million, represented by Ripple (Ripple Prime $275 million senior unsecured note), Prime Intellect, and Gauntlet.
Additionally, two $400 million individual transactions each supported a separate tag: Bitcoin mining company Ionic Digital and Securitize, which went public on the NYSE via SPAC.
DeFi's amount is relatively low, partly due to insufficient disclosures: only 25 of the 51 transactions disclosed their amounts. Even considering this, DeFi clearly consists of smaller, early-stage, protocol-oriented transactions. Consumer categories are nearly empty: the gaming main tag had only 3 transactions amounting to about $5.9 million.
Transactions Solely Involving Crypto Native Capital Decrease by Nearly 60%
Transactions solely involving crypto native capital this quarter disclosed amounts dropped from $2.57 billion in the previous quarter to $1.05 billion, with shares decreasing from 44% to 24%; transactions involving traditional finance or general capital increased from 39% to 45% in share.
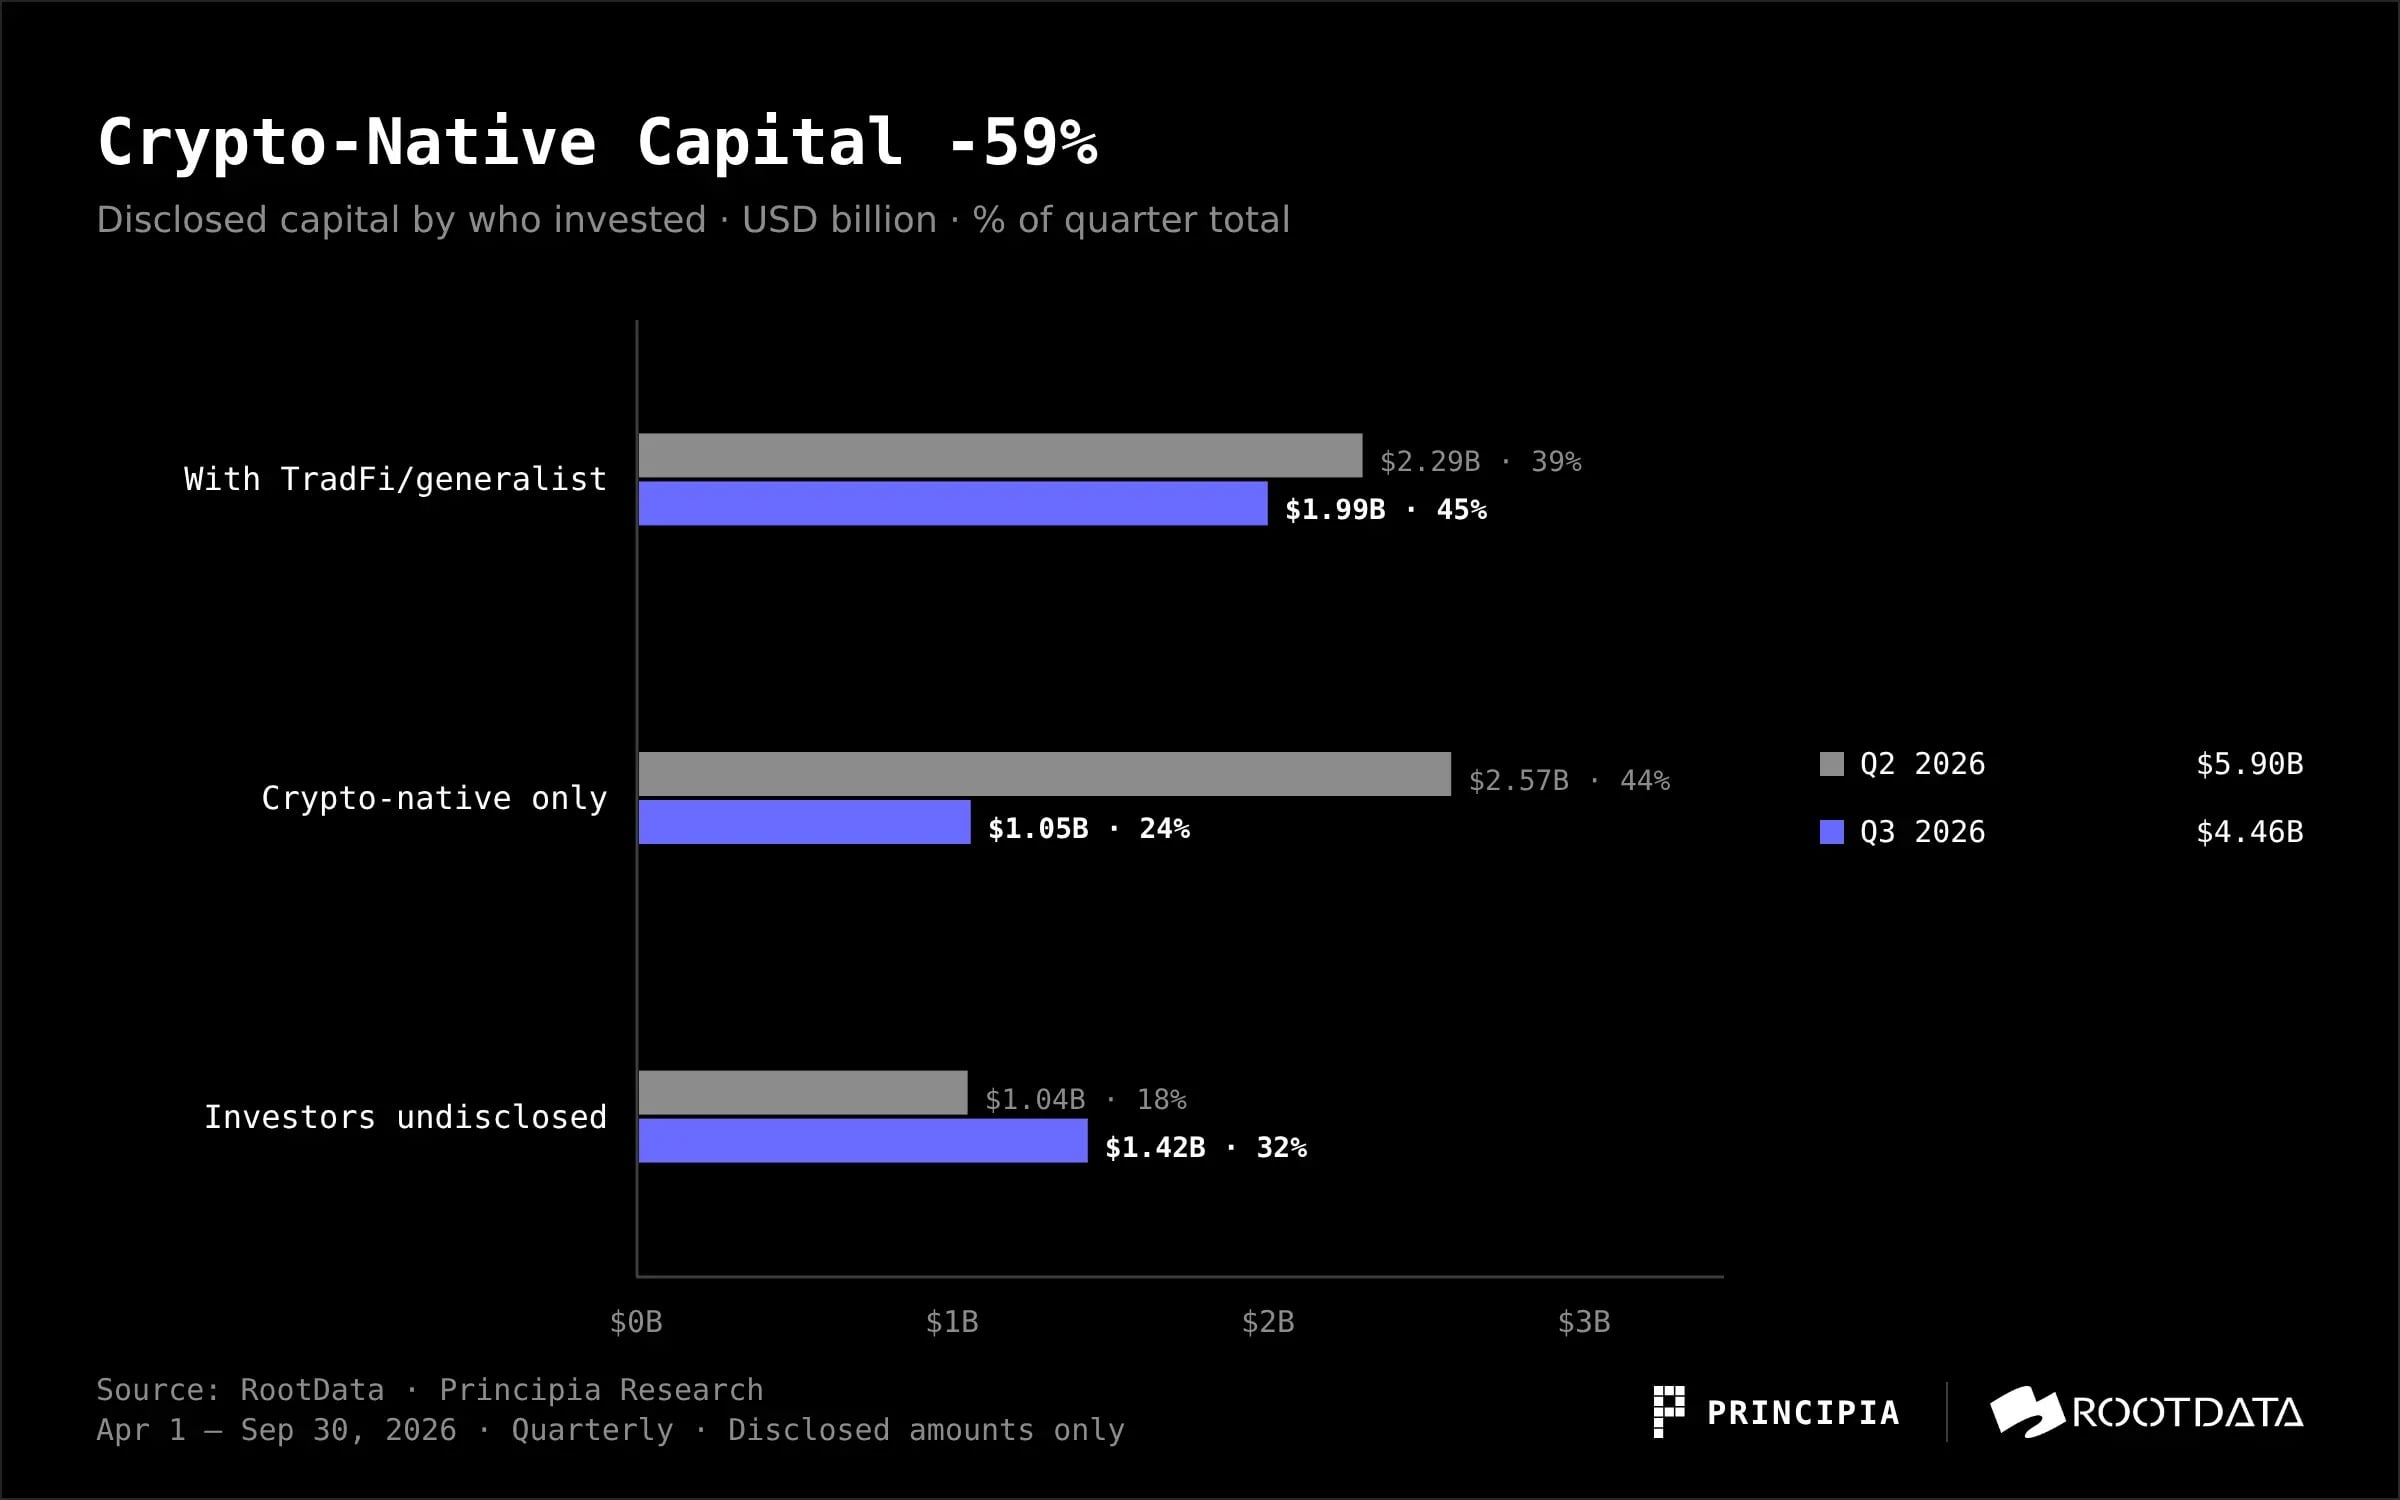
Figure: Comparison of participation shares of crypto native capital and traditional/general capital in Q2 and Q3 2026 (Source: Principia Research & RootData)
“Traditional finance or general capital” refers to banks, exchanges, and market infrastructure, brokerages, asset management companies, tech giants, trading firms, as well as comprehensive and fintech VC.
Crypto native capital is contracting, while in this quarter, several of the largest transactions were backed by Citadel Securities, Nasdaq, 1789 Capital, Tiger Global, Peak XV, SBI, Intel Capital, and ICONIQ.
In terms of frequency, the picture is different. The most active are YZi Labs and Coinbase Ventures, but both primarily focus on incubating and co-investing, with hardly any lead investments.
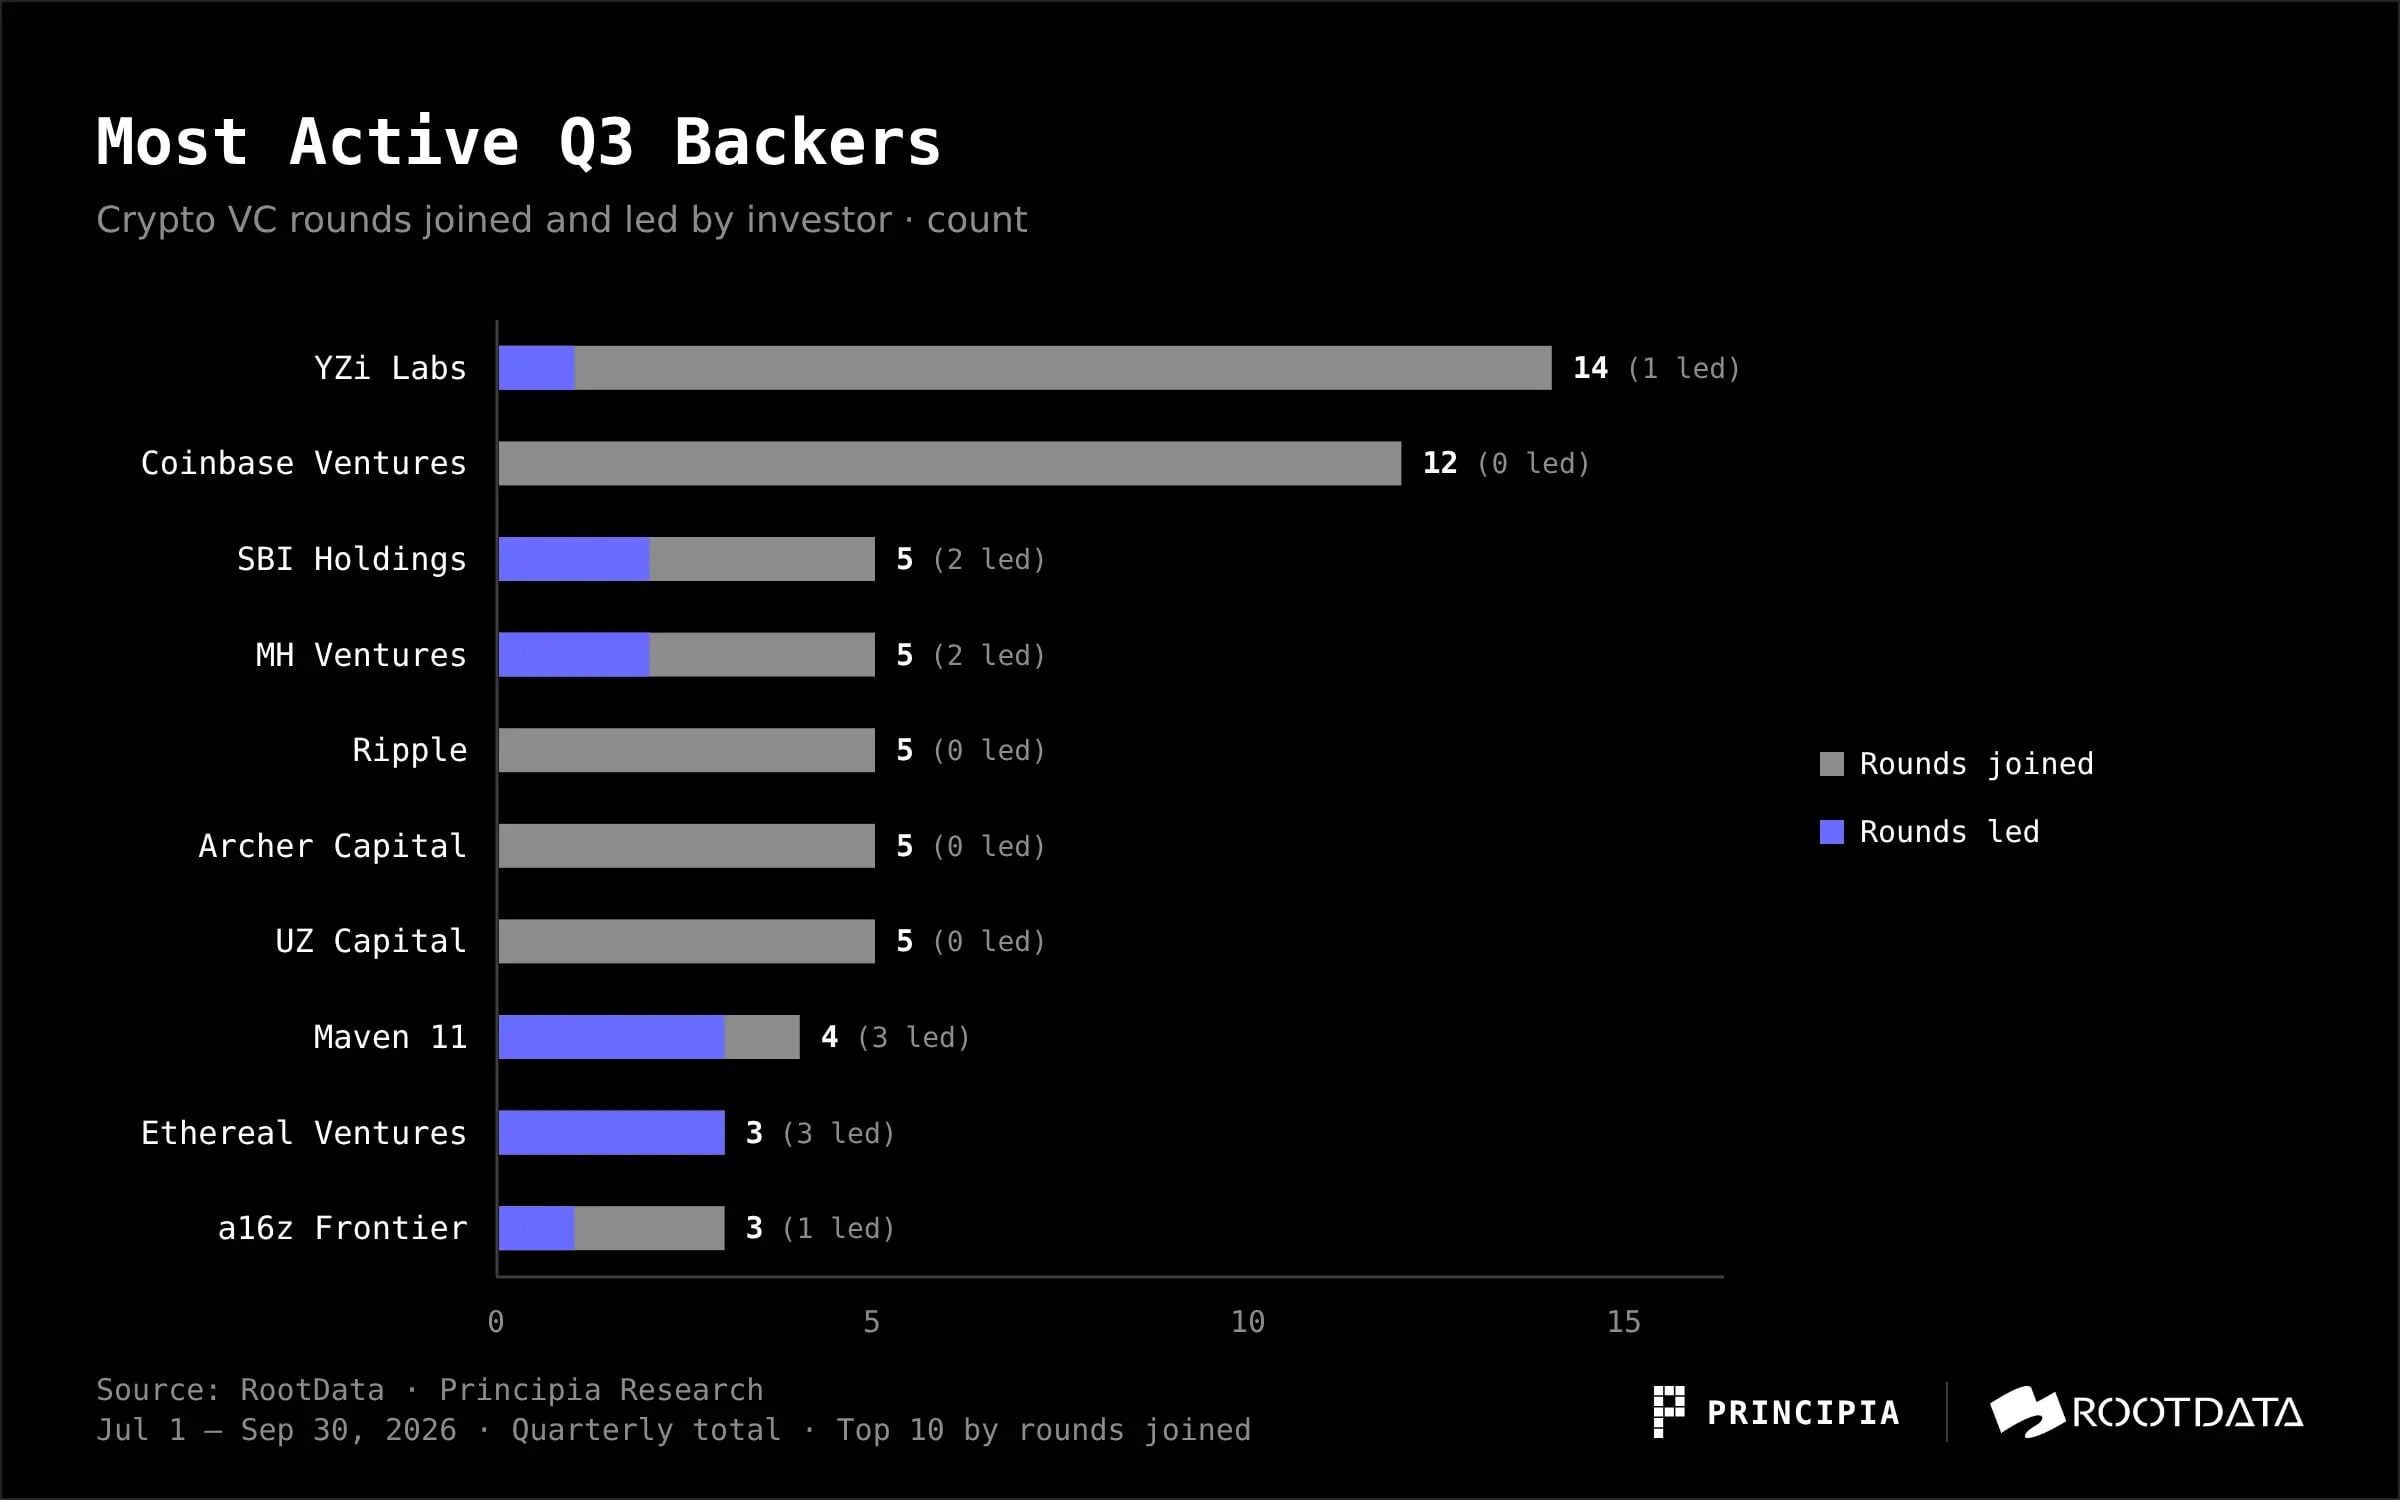
Figure: Ranking of the most active crypto investment institutions by number of participations and leading investments in Q3 2026 (Source: Principia Research & RootData)
Compared to Q2, the leaders have changed. Q2's most active were Coinbase Ventures (13 times), Animoca Brands (12 times), and a16z Frontier (formerly a16z Crypto, 8 times), with Paradigm also leading 4 transactions.
This season, more pricing power has been handed to the aforementioned traditional financial institutions.
Many New Companies, Established Companies Securing Big Funds
Companies established in or before 2021 secured financing for 51 transactions this quarter, taking $2.3 billion, accounting for more than half of the disclosed total amount. New companies established after 2025 had the most transaction counts at 67, yet only obtained $630 million.
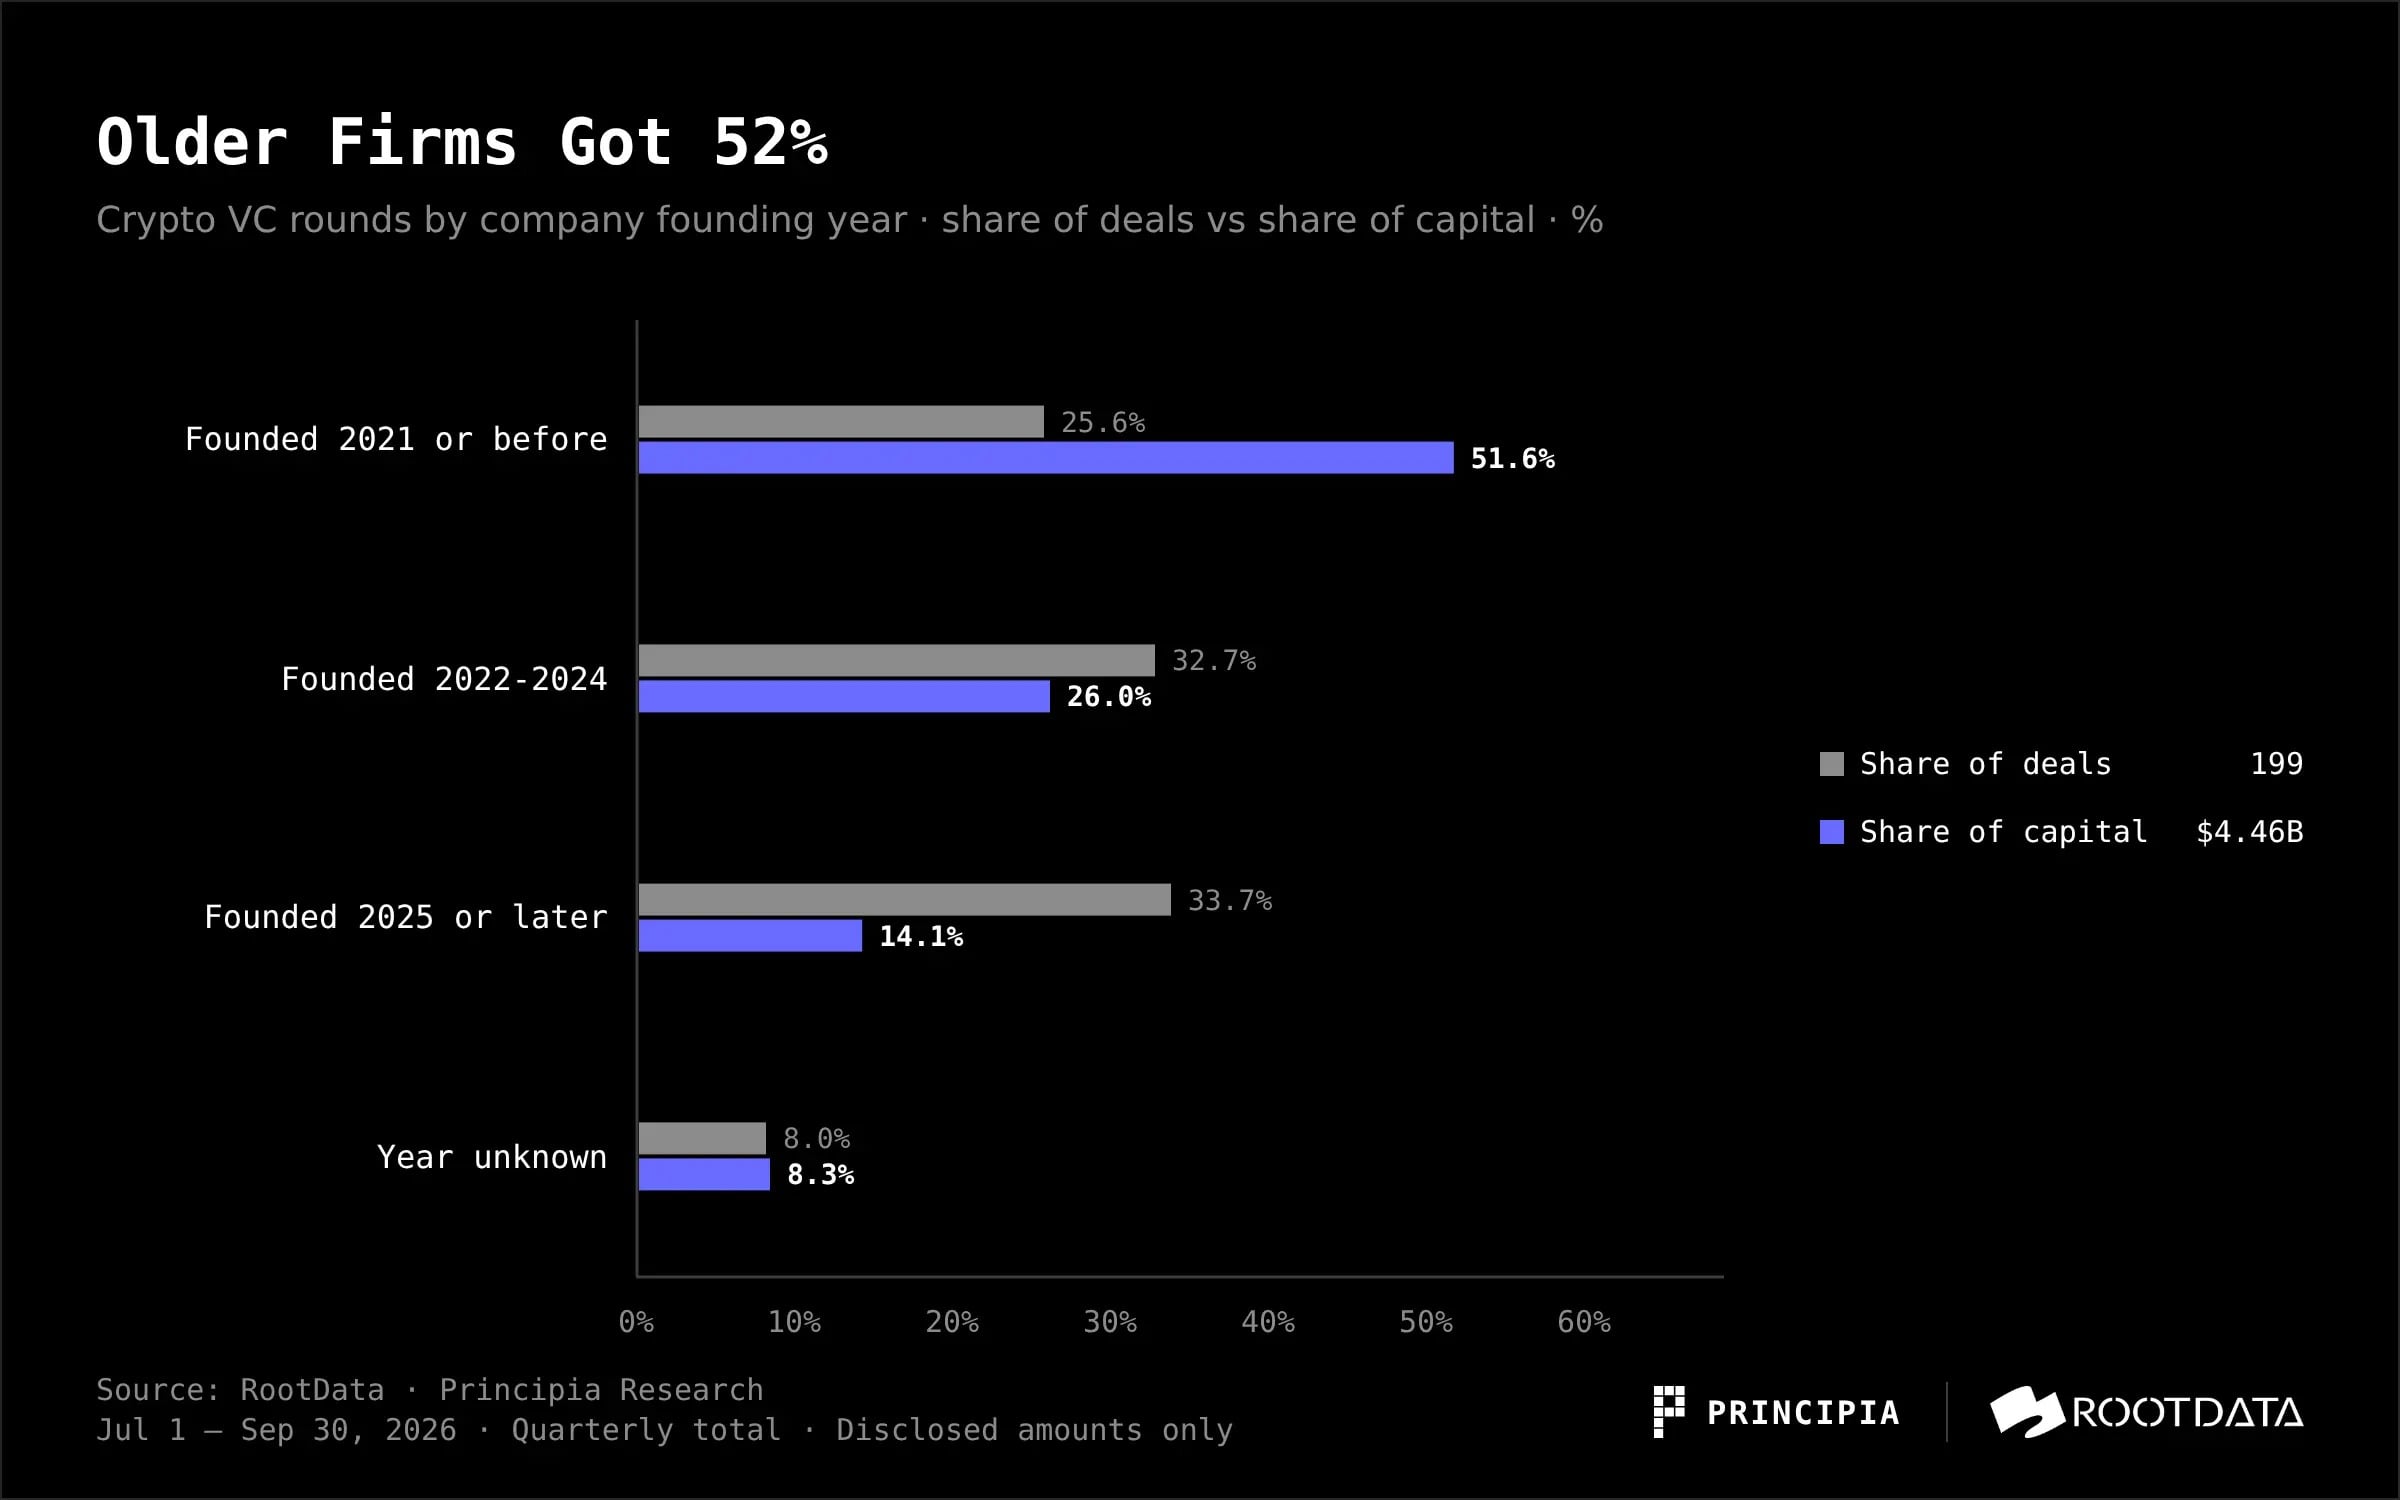
Figure: Financing projects by date of establishment in Q3 2026 by transaction counts and amounts (Source: Principia Research & RootData)
The list of established companies securing large financings is familiar: Crypto.com (established in 2016), Kraken (2011), Ripple (2013), Securitize (2017). They have revenue, licenses, and valuatable businesses, aligning well with this season's funding preferences.
Regionally, the U.S. Remains Dominant
RootData's country field only covers 53 out of 192 projects (28%), corresponding to 55 transactions totaling $2.19 billion, approximately half of the disclosed total amount for the season. In this sample, the U.S. accounted for 28 transactions totaling $1.52 billion; Singapore had 10 transactions totaling $444 million, of which Crypto.com alone accounted for $400 million.
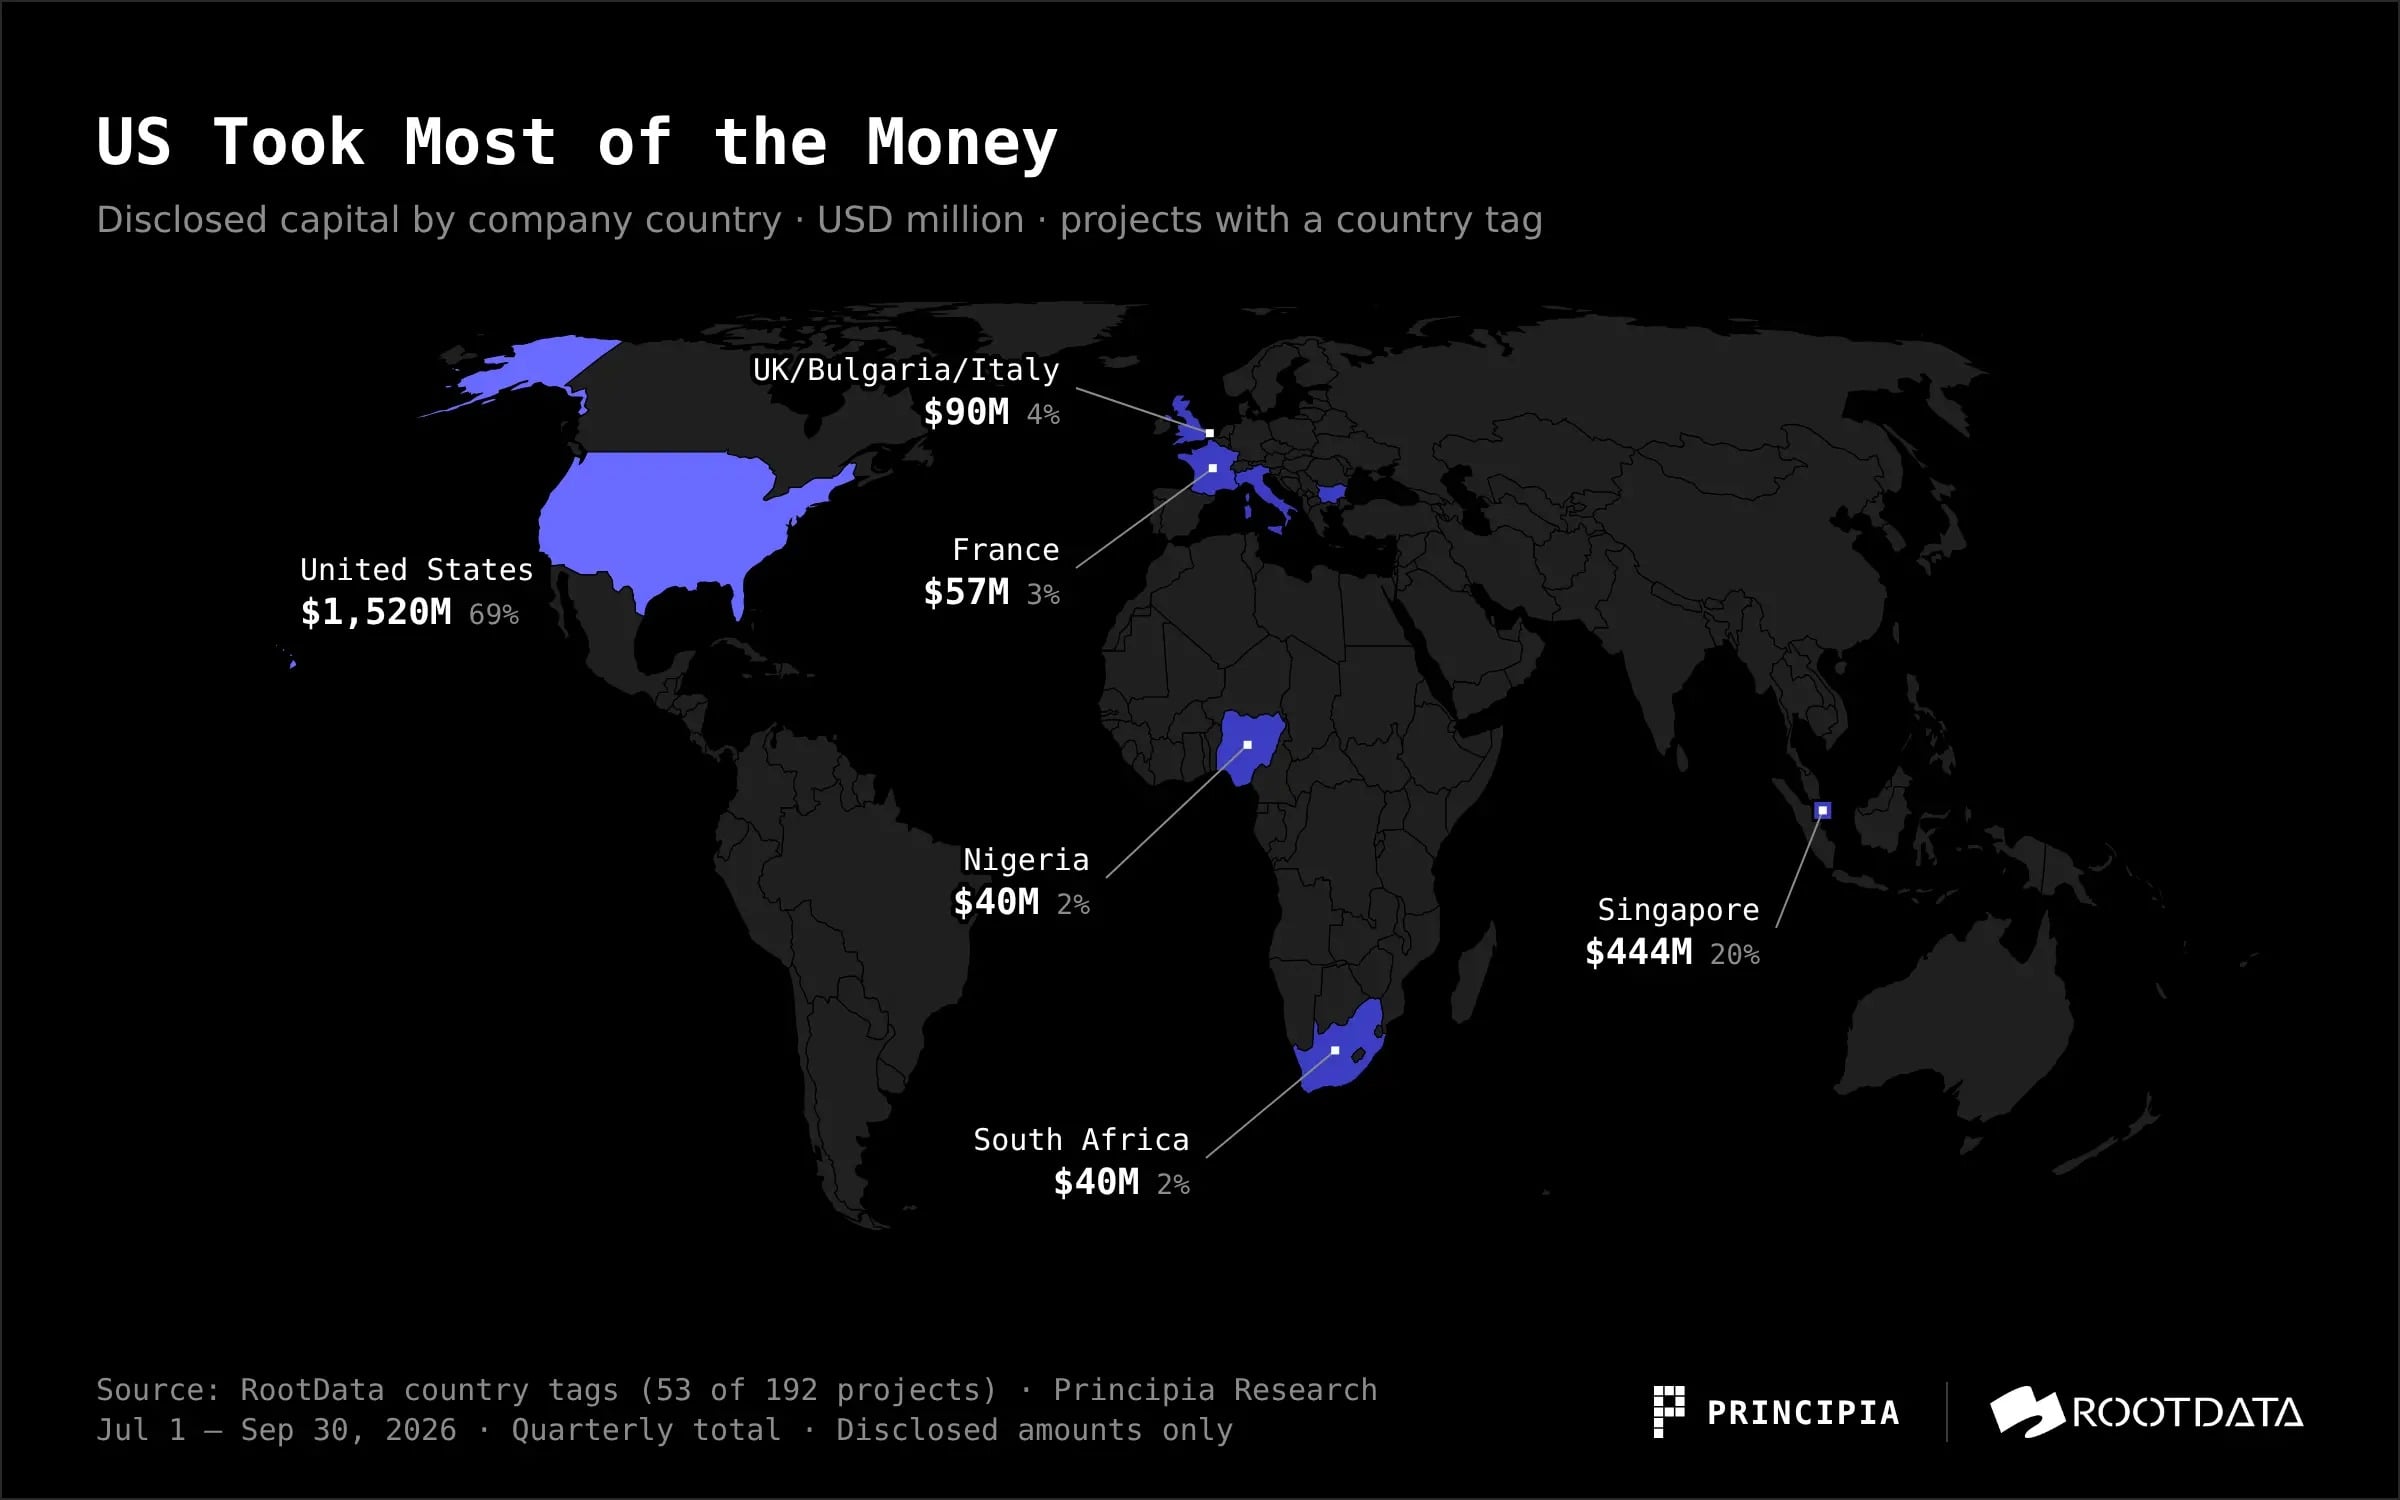
Figure: Distribution of disclosed financing amounts by country/region for Q3 2026 (Source: Principia Research & RootData)
The other countries were quite scattered. The UK, Bulgaria, and Italy each had around $90 million, France $57 million, Nigeria and South Africa $40 million each; Hong Kong had 3 transactions, Japan 2 transactions, with both amounts being small.
Although coverage is very low, it still indicates that funds remain highly concentrated in the U.S., with significant transactions from Asian countries mainly coming from exchanges in Singapore.
Fundraising: Next Round of Ammunition Tightening
The amount that can be invested in the primary market ultimately depends on how much funds can be raised by venture capital. According to Galaxy Research, this season only 3 new crypto venture funds completed fundraising, totaling about $1.3 billion, making it the least number of new funds since Q3 2019.
On an annualized basis, this year’s fundraising is approximately $8.2 billion, slightly lower than 2025's $8.75 billion. The average size of funds this year has been around $386 million, with the median only $71 million: most new funds are small, while a few large funds have raised the average.
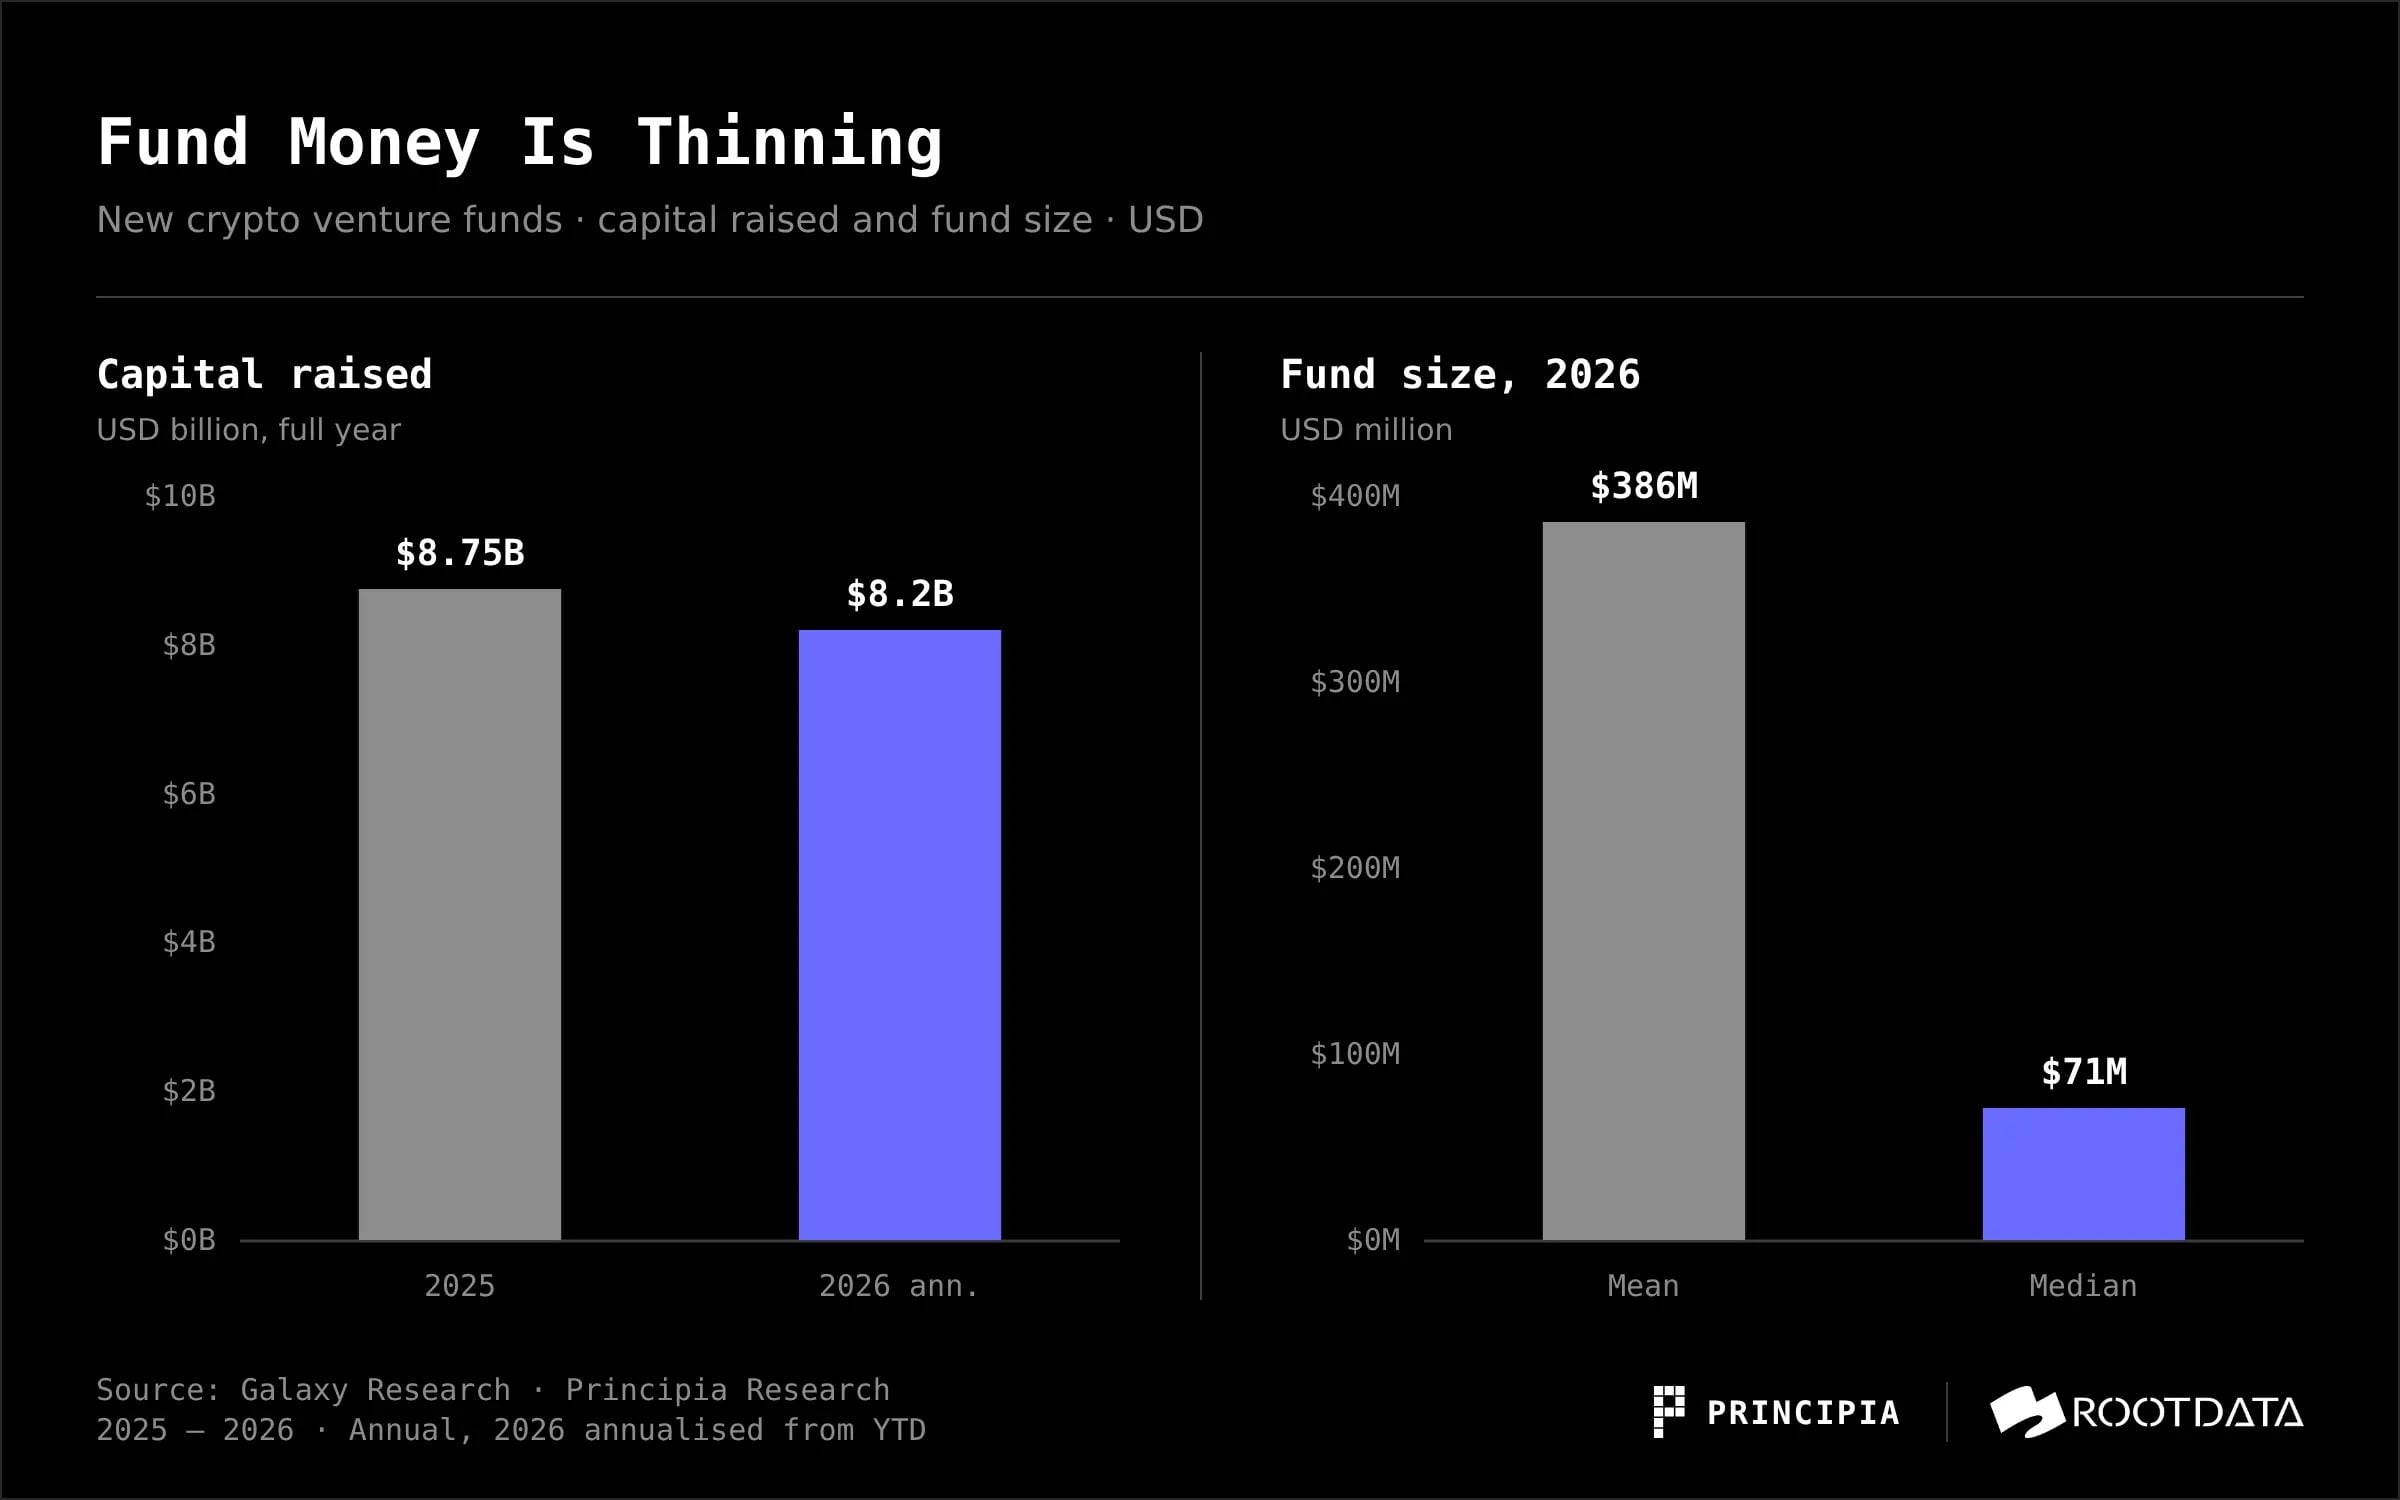
Figure: Annual comparison of new crypto venture fund fundraising amounts and average/median sizes for 2026 (Source: Galaxy Research & Principia Research)
The difficulty in fundraising and the cooling on the investment side are two sides of the same coin: spot ETFs, digital asset treasury firms, and AI are competing for LP allocation quotas.
Our judgment is that tightening financing on the LP side will make GPs more cautious: prioritizing support for follow-up rounds of already invested projects and more bets on companies with revenue, licenses, and distribution channels may bring more valuation. This also reflects the form of investment seen this quarter.
Conclusion
In Q3, overall, VC investment activities are cooling down; funds are flowing towards financial channels that can charge fees, hold licenses, and provide clearing, with pricing power increasingly handed to traditional financial institutions; VC LP financing is facing a chill, and the follow-up financing situation for startups is not optimistic.
For entrepreneurs, the timing to secure large amounts of funding has become later, and requirements are closer to those for mature companies: revenue, licenses, and distribution channels can garner valuation more than narratives. Early-stage financing has significantly decreased, with VCs less risk-tolerant, so it's necessary to be ready to speak with product data and accept smaller first rounds.
For investors and LPs, the increase in cryptocurrency prices has not automatically translated to the primary market. This season, Bitcoin's price increased about 43%, yet financing continues to decline, and the old script of "prices rise, venture capital thrives" is temporarily failing.
Transactions in the mid-range of $20 million to $100 million rebounded quarter-on-quarter, but the number of equity transactions remained flat, indicating a need for more quarterly data to confirm the trend.
What to watch for in Q4:
· Will traditional finance continue to participate: 45% of disclosed amounts this season involved traditional finance. Is this a structural change or just a coincidence of several large transactions? Q4 will provide answers.
· Can cryptocurrency price increases translate to early rounds: Only a rise in the number of small early rounds will indicate a true warming on the entrepreneurial side.
· Policies and fundraising: The progress of the CLARITY Act, and whether new funds can complete fundraising by the end of the year.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


