Author: Zhang Jinyi, DeepTech
On November 3, local time, the voting for the U.S. midterm elections concluded. The Democratic Party regained control of both the House and the Senate, winning gubernatorial elections in traditionally Republican-dominant states like Texas and Georgia. Although some districts are still counting votes, the political landscape in the United States has already shifted.
In the next two years, Trump will face a Congress controlled by the Democratic Party. The Democratic Party can impose more restrictions on White House policies through legislation, budget reviews, and congressional investigations. At the same time, several state government leaders are also changing, and industry policies at both the federal and local levels may also be adjusted accordingly.
The technology industry will be one of the critical areas affected by these policy changes. The rapidly expanding data centers in recent years may face stricter approvals, AI companies need to cope with new regulatory requirements, and semiconductor subsidies and chip export controls to China will enter a new round of policy games.
On November 4, the U.S. stock market showed divergence. The S&P 500 index rose by 1.6%, and the NASDAQ index increased by 1.4%, but the AI infrastructure sector generally declined. The Philadelphia Semiconductor Index fell by 3.1%, power company Vistra Energy plummeted by 13.83%, data center temperature control equipment provider Vertiv dropped by 12.89%, and fuel cell company Bloom Energy also fell by 6.36%.
Market concerns are mainly focused on the construction of data centers. In the past few years, U.S. tech companies have invested heavily in procuring chips and expanding computing infrastructure, with many project delivery plans already extending to 2028 or even later. As multiple key states change government, the approval progress, construction costs, and investment returns of these projects are all beginning to face new uncertainties.
Furthermore, as an important political donor to the Republican Party, Musk's enterprises have also been impacted. On November 4, Tesla's stock price fell by about 3.3%, and SpaceX fell by about 3.8%. Musk invested about $474 million in this midterm election, but many Republican candidates he supported ultimately lost.
Among them, Texas, where Musk's business layout is highly concentrated, welcomed a Democratic governor after more than 30 years.
Data Center Construction May Be Affected First
On November 3, Democratic candidate Gina Hinojosa defeated incumbent Republican Governor Greg Abbott, becoming Texas's first Democratic governor in over 30 years.
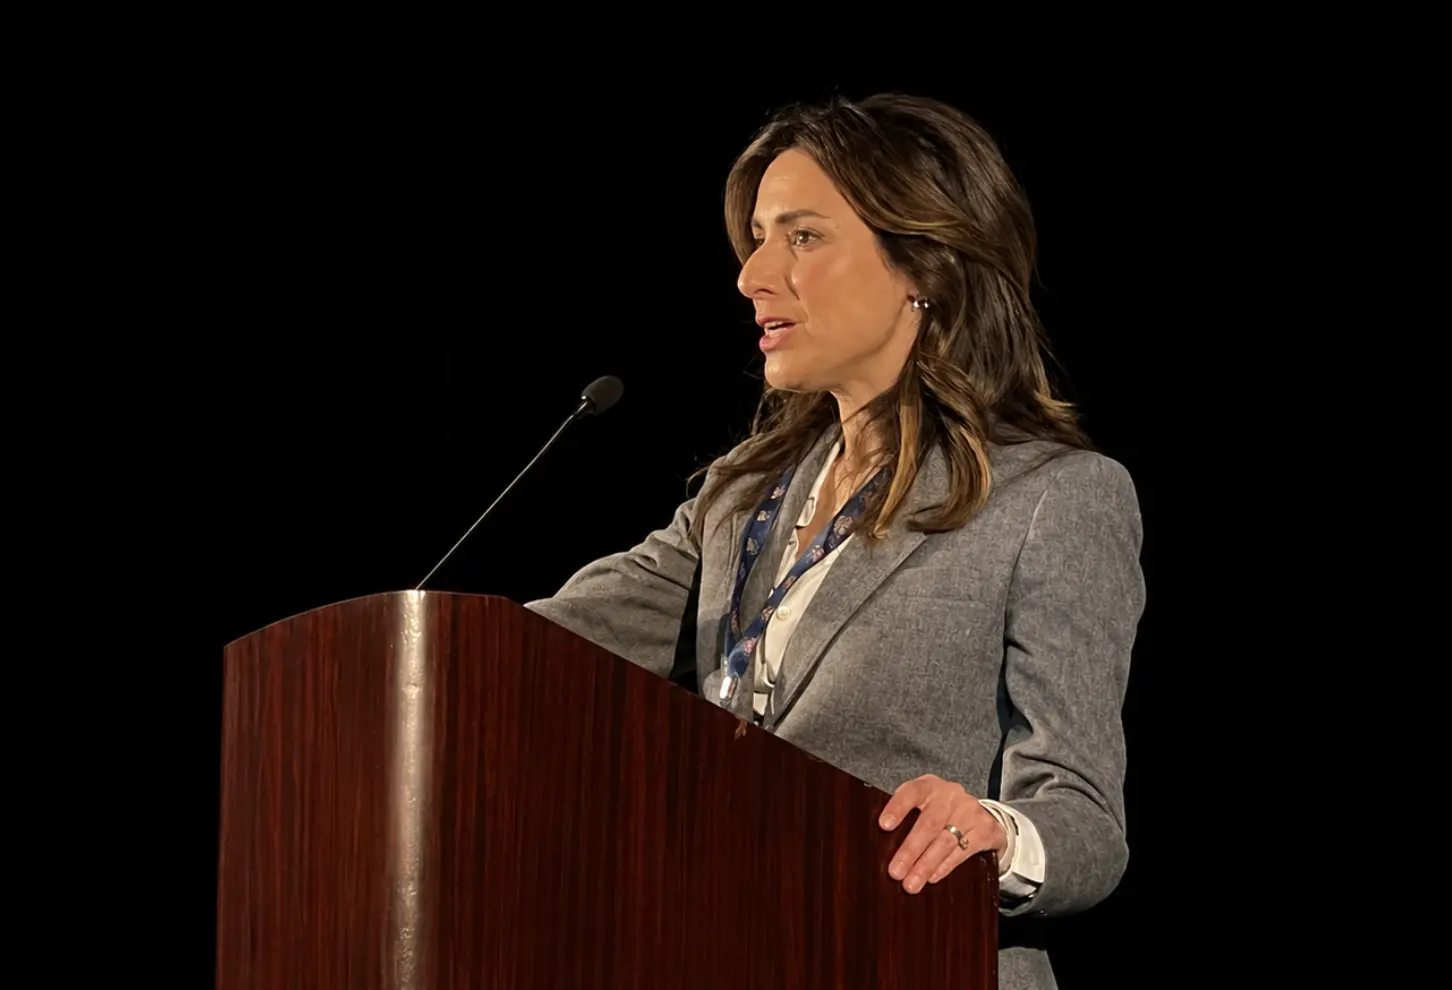
Image | Gina Hinojosa (Source: Wikipedia)
During the campaign, Hinojosa explicitly stated that approvals for new data centers should be paused until new regulatory regulations are issued and required developers to bear more costs for power grid expansion while cutting related tax incentives. If these policies are implemented, the large-scale computing construction plans being promoted in Texas will be directly affected.
In recent years, Texas has attracted a large number of tech companies and infrastructure developers due to ample land, relatively low electricity prices, and tax incentives provided by local governments, becoming one of the most active regions in the U.S. for AI data center construction. However, as large data centers have been concentrated, local residents have begun to worry that the spike in electricity demand will drive up household electricity prices, cooling facilities will consume water resources, and the substantial tax incentives have not brought corresponding benefits to surrounding communities.
Similar controversies have also arisen in other regions of the U.S. For example, Pennsylvania introduced regulations in August this year requiring data center developers to bear their electricity costs and eliminated fast-tracked approval channels for some projects; Georgia's newly elected Democratic Governor Keisha Lance Bottoms also previously supported pausing certain data center approvals.
Among the 45 local votes related to data centers that have been announced, 33 favor strengthening restrictions.Requiring constraints on data center expansion has become a bipartisan issue in local U.S. politics.
Musk will also face pressure from policy changes in Texas. In recent years, he has moved the headquarters of Tesla and SpaceX to Texas and has continued to expand local manufacturing and computing infrastructure investment. Currently, the capacity of data centers planned and under construction by SpaceX has exceeded 9 gigawatts, with some projects located in Texas.
Previously, Hinojosa publicly opposed the plan to transfer some state land resources to SpaceX. Now, with the change in state government, new construction projects by Musk's companies in the region may face longer approval cycles and higher infrastructure costs.
However, the impact of new policies on the entire U.S. data center industry mainly depends on the construction stage of the projects.
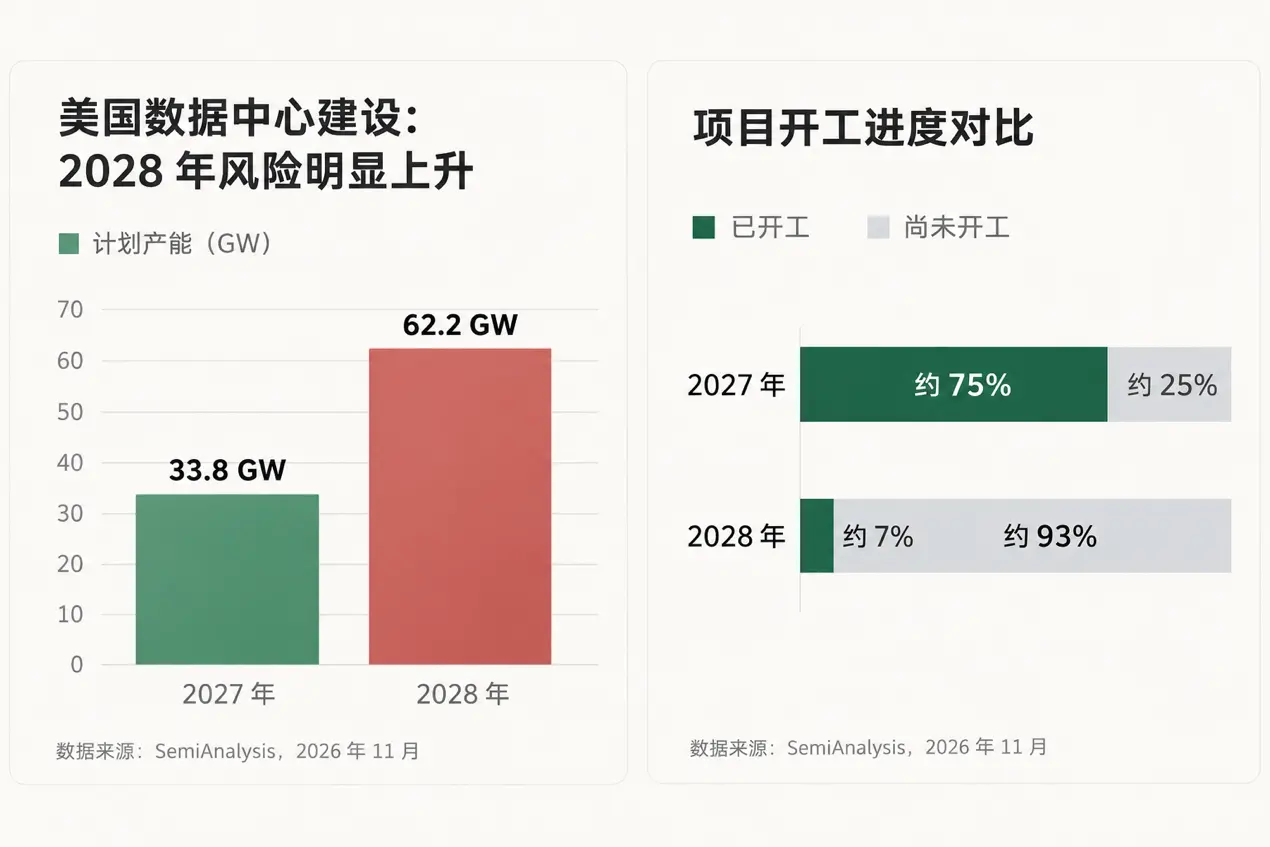
Aside from construction timeliness, costs may also rise. A report published in early November by the semiconductor and infrastructure research organization SemiAnalysis, which tracks 20 entities, indicated thatthe construction risk of data centers in the U.S. mainly focuses on the year 2028. In contrast, the capacities scheduled for delivery in 2027 have mostly entered the construction stage, with limited impact from local policy adjustments.
According to the report, the top 20 states in terms of data center construction scale plan to deliver approximately 33.8 gigawatts (GW) of capacity in 2027, of which about three-quarters are already underway. Most of these projects have completed site selection, approvals, and equipment procurement, leaving little room for adjusting construction plans in the short term.
In 2028, however, numerous projects are still in the planning stage. The U.S. is expected to net an increase of about 62.2 gigawatts of data center capacity that year, and in the 13 key states being tracked, approximately 93% of planned capacity has yet to commence construction, with 10 states having just elected new governors.
(Source: DeepTech Graphics)
Texas accounts for nearly 30% of the newly planned capacity in the U.S. for 2028.Given that many projects have yet to complete approvals, if the new government extends the licensing periods or raises requirements related to electricity use and environmental protection, some data centers originally scheduled to commence operations in 2028 may need to delay their delivery.
Out of the 20 gubernatorial candidates, 15 advocate that data center companies should bear more costs for power grid expansion, and 12 support reducing or eliminating tax incentives. For developers, these additional expenses will further compress project profits.
Large cloud service providers have relative financial leeway and mature data center networks, allowing them to manage some delays by adjusting project arrangements. However, for data center developers and new cloud vendors reliant on external financing, longer construction cycles will further increase financial pressure. Especially for companies that have already invested heavily in procuring GPUs but are unable to finish construction and connect to the power grid in time, they cannot generate income from their equipment while still needing to pay ongoing loan interest.
Anthropic Set to Go Public, Will AI Companies' Financing Environment Change?
If data center construction is delayed, the companies relying on these facilities for computing power will also be affected.
In recent years, companies like OpenAI and Anthropic have continuously expanded their training and inference clusters, signing long-term procurement agreements with cloud service providers and data center operators to lock in computing resources for the coming years. These contracts ensure computing power supply but also burden companies with substantial long-term expenditures.
Anthropic, which is preparing for an IPO, will be an important sample for testing this high-investment business model.
On October 26,Anthropic submitted an S-1 prospectus to the U.S. Securities and Exchange Commission (SEC)and updated its financial data on November 2. The company may go public as early as mid-November.
According to the prospectus, Anthropic's revenue for the first three quarters of this year was approximately $33.2 billion, a year-on-year increase of about 12 times, while the operating loss during the same period still reached $1.26 billion.Despite rapid revenue growth, the company still needs to invest a lot of capital in model research and computing power procurement.
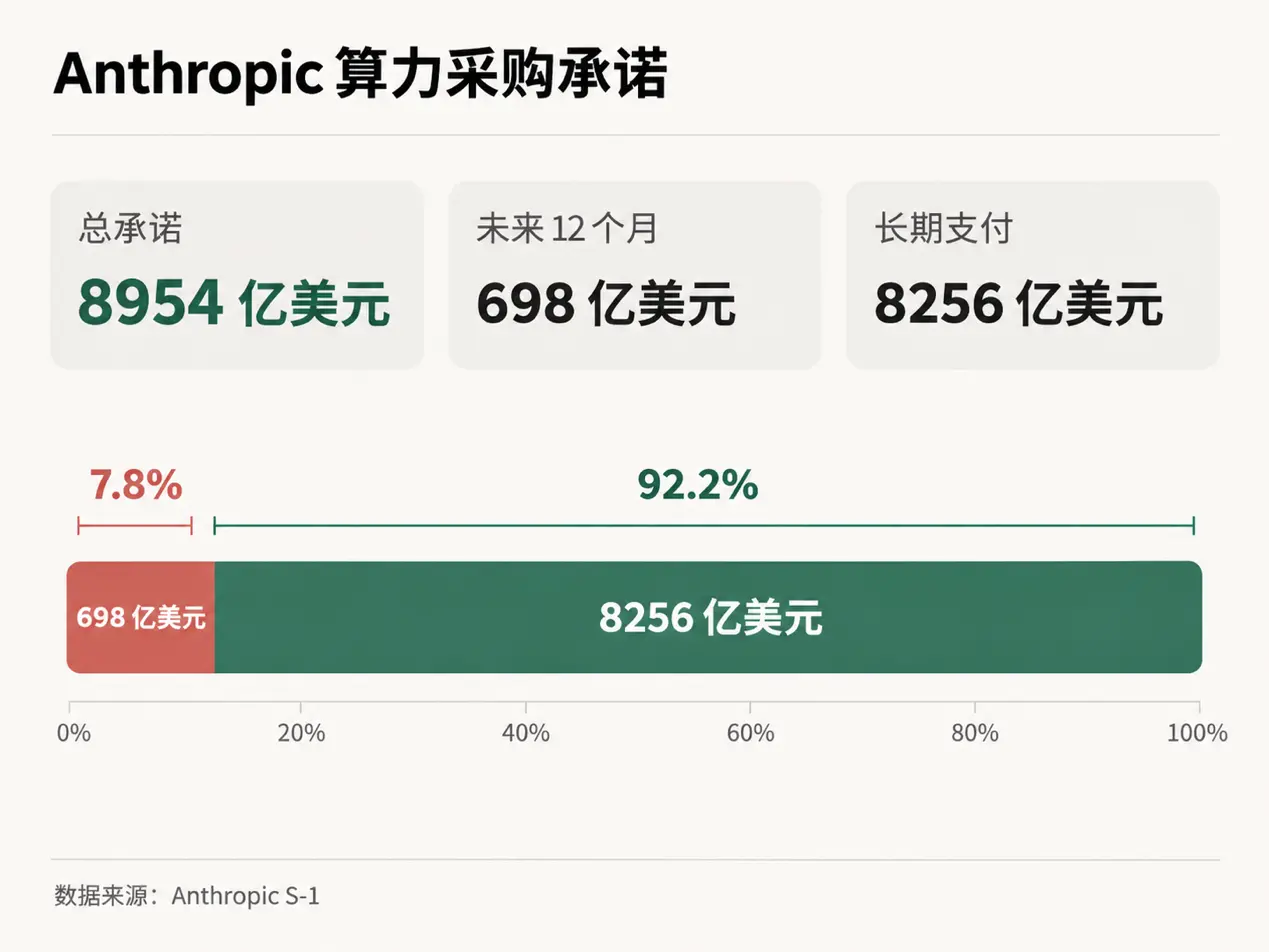
One important data point is its future commitments for purchasing computing power. As of the end of September and after, the total amount of computing power procurement and leasing commitments reached $895.4 billion, of which about $69.8 billion needs to be paid within the next 12 months, with the remaining expenditures spread over longer contract periods.
(Source: DeepTech Graphics)
This massive long-term procurement plan requires timely delivery from data centers as support. Once new data centers face delays due to approval or power grid connection issues, model companies may need to purchase temporary computing power at a higher price or adjust their training and product release schedules. If relevant contracts also include fixed payment obligations, delays in computing power delivery will further increase companies' cash flow pressure.
Investors have begun to reassess the risks associated with such huge investments. The Wall Street Journal recently reported that some institutional investors preparing to participate in Anthropic's IPO are inclined to give the company a valuation of about $1.5 to $1.6 trillion, lower than the approximately $2 trillion previously discussed in the market.
As local governments may further tighten data center approvals, computing power construction costs and delivery risks will also rise, increasing financing and valuation pressure on model companies like Anthropic and OpenAI that rely on external computing power. In contrast, large tech companies like Microsoft, Amazon, Alphabet, and Meta have more ample cash reserves and self-built infrastructure, making them better able to absorb these costs.
What Adjustments Might Occur in AI Regulation and Semiconductor Policy?
In addition to local government management of data center construction, the change in congressional control will also affect federal-level technology policy.
The new Congress will officially take office in January 2027.By then, the Democratic Party will control the leadership of the major committees in Congress, allowing them to strengthen investigations on AI safety, data privacy, and market competition issues through congressional calls to tech company executives, review of internal documents, and organization of hearings.
Previously, the Trump administration advocated for loosening AI regulations and promoted establishing a relatively unified federal regulatory framework to reduce the compliance burdens created by differing state regulations.However, many Democratic lawmakers support imposing stricter safety requirements on cutting-edge models, including regulations on risk assessments, information disclosure, and corporate liability.
In September of this year, Democratic Senator Mark Warner and others even proposed establishing a dedicated AI safety committee to enhance government oversight of technological risks. Some newly elected Democratic lawmakers also emphasized during their campaigns the impact of AI on employment, local economies, and public resources.
With the Democratic Party regaining control of Congress, these issues may receive more discussion opportunities, forcing tech companies to respond to more frequent hearings and investigations.
However, advancing regulatory legislation still faces political obstacles. Trump holds veto power, and Congress needs two-thirds support from both houses to overturn a veto. There are also internal disagreements among Democrats regarding the scope and specific requirements for AI regulation. Therefore, the changes that are likely to occur in the next two years may be Congress exerting continuous pressure on tech companies and the executive branch through investigations, hearings, and budget reviews.
Semiconductor subsidies are also connected to congressional budget arrangements.The CHIPS and Science Act passed in 2022 provided approximately $39 billion in incentives for domestic semiconductor manufacturing in the U.S. Following this, companies like TSMC, Intel, and Samsung built new factories or expanded capacity in the U.S., but the existing funds have now mostly been allocated.
The U.S. Congressional Research Service noted in July of this year that fiscal year 2026 is the last year of statutory allocations for this program. As existing funds enter the execution stage, Congress needs to discuss whether to continue providing support and how to evaluate the implementation effects of previous subsidies.
With the Democratic Party controlling Congress, there may be increased scrutiny on whether companies meet their commitments to build factories, create jobs, and the efficiency of government fund utilization. For semiconductor companies, whether to obtain new subsidies in the future and what labor and environmental requirements will accompany future allocations will affect their investment plans in the U.S.
Will There Be Any Easing of Chip Restrictions on China?
For China's technology industry, the Democratic Party regaining control of Congress may lead to stricter congressional oversight of U.S. export controls on advanced chips to China.
There has long been significant bipartisan consensus on restricting China's access to advanced AI chips and semiconductor manufacturing equipment. Both parties diverge on specific execution methods, but they regard advanced computing power and semiconductor technology as important areas of technological competition with China.
In January of this year, the Trump administration adjusted relevant policies to allow NVIDIA H200, and AMD MI325X and other products to undergo case-by-case approvals if they met safety requirements. This approach was subsequently criticized by some Democratic lawmakers.
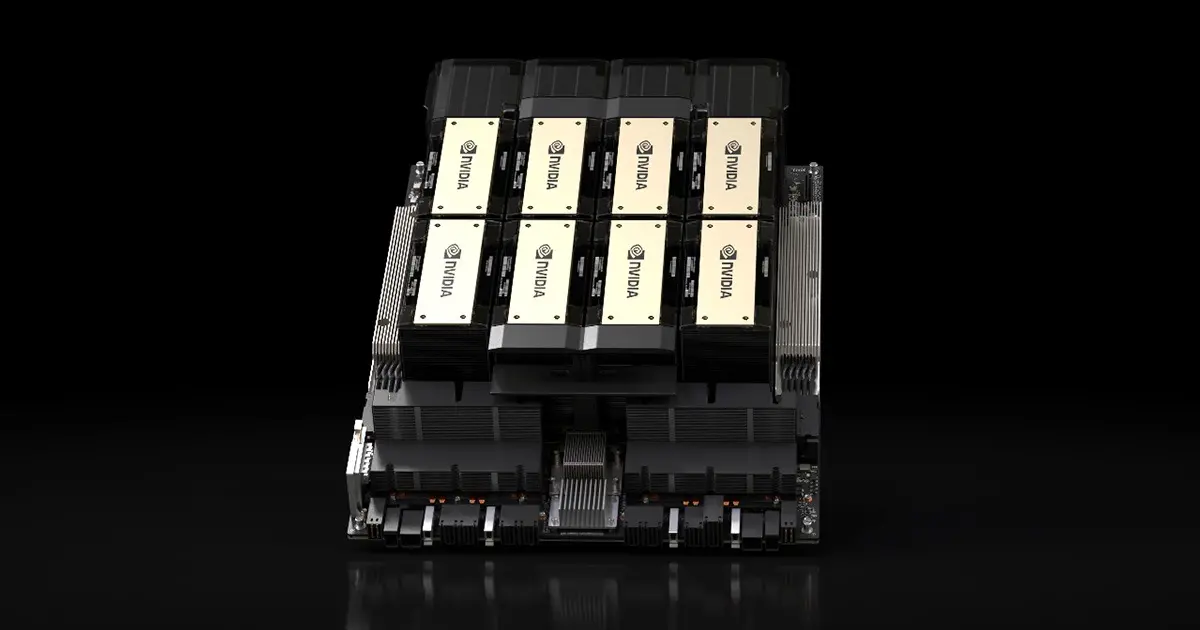
Image | NVIDIA H200 GPU (Source: NVIDIA)
By September, Democratic Senators Elizabeth Warren, Chuck Schumer, and others again called for strengthening export restrictions on advanced chips and semiconductor equipment, and some Republican lawmakers also supported similar claims.
After the new Congress takes office, Democratic lawmakers will have more opportunities to review the Department of Commerce's export licensing policies, demand government disclosure of approval situations, and promote stronger verification of the final uses and actual flows of chips.The specific export licenses will still be approved by the Trump administration, while Congress mainly exerts influence through legislation, oversight, and budget measures.
At the same time, changes in the pace of U.S. data center construction may also transmit to Chinese enterprises along the global supply chain.
If some U.S. data center projects are postponed, the originally scheduled procurement of GPUs, memory, servers, and optical modules may also adjust their delivery times accordingly.For Chinese enterprises involved in the global AI hardware supply chain, especially those with a high proportion of North American customers, order scheduling and inventory management may change as a result.
The impact on different products varies. Power and cooling equipment directly used for new data centers is more sensitive to project construction progress; some servers, memory, and optical communication products can be used for upgrades to existing data centers, and their demand is more dependent on customers' equipment upgrade plans.
Overall, the impact of this midterm election on the U.S. AI industry may first manifest in the costs and delivery timelines of infrastructure construction. Data centers scheduled for delivery in 2027 have mostly begun construction, while projects still in the planning stage for 2028 will face new approval requirements from local governments.
Changes at the federal level will take more time to manifest. Whether it's AI safety regulation, semiconductor subsidies, or chip export controls to China, they all involve ongoing coordination between the White House and Congress.
In recent years, U.S. tech companies have continuously expanded their computing power scale through substantial capital investments. As more projects enter the actual construction phase, power supply, local approvals, and financing costs are beginning to impact companies' expansion plans. In the next two years, whether the investment scale of the U.S. AI industry can smoothly translate into actual capacity will become an important indicator to observe the influence of this election.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


