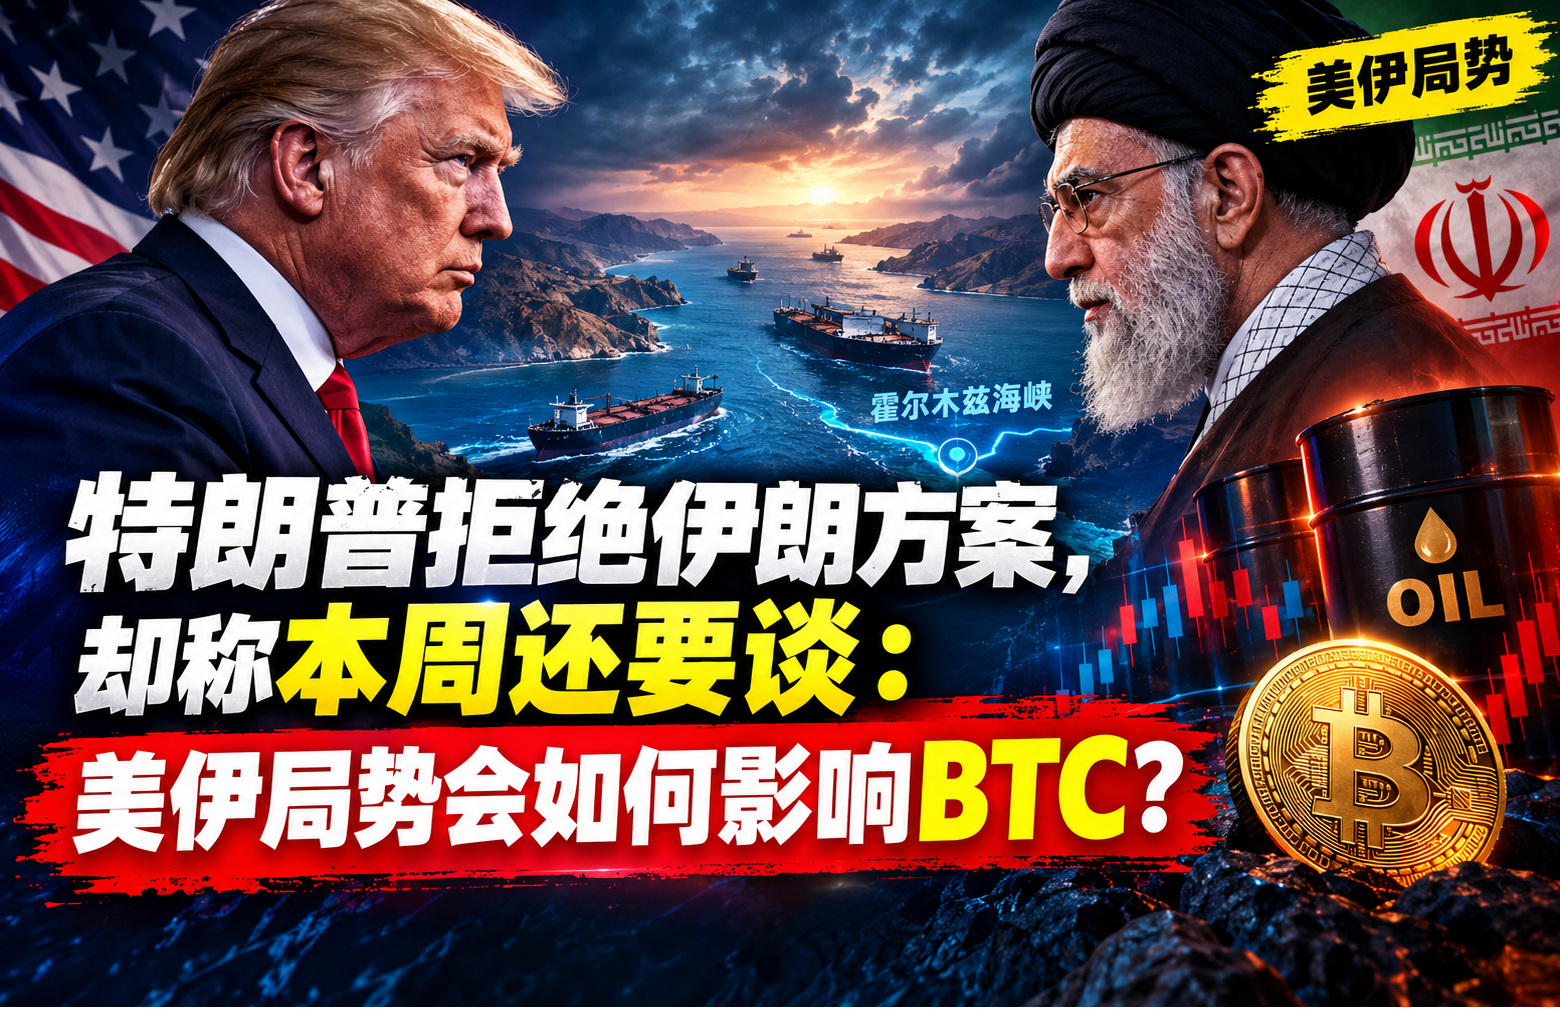
The story took a turn at the Strait of Hormuz. Recently, Trump rejected Iran's latest proposal to reopen this critical shipping route, and the market immediately responded with oil prices: on Monday during the Asian session, crude oil surged, and traders began to factor in the risks associated with Middle Eastern supply and a new wave of inflation into their models. Inflation concerns layered with the already heightened expectations for interest rate hikes led to a new round of sell-offs in U.S. Treasury bonds. According to the data from the same source, the 2-year yield rose to about 4.9%, and the 10-year yield approached 5.2%, increasing by about 5 and 4 basis points respectively in a single day, while the 10-year yield is still close to its highest level since 2007; even more striking is that the spread between the 2-year and 10-year yields once shrank to about 17 basis points, the narrowest level since early 2025, highlighting the yield curve warning often associated with recessions, which was further amplified into a global signal by the sell-off of sovereign debt in Japan, Australia, and elsewhere. Under the dual pressure of "high risk-free rates + potential recession," funds began to reprice risk assets: when U.S. Treasury bonds offer nearly 5% locked returns, how much risk premium can BTC, ETH, and other on-chain assets priced in dollars still achieve, or will some funds treat them as alternative positions to hedge against inflation and economic downturn? This is the question that the entire trading chain must confront going forward.
Tensions in the Strait of Hormuz Push Up Oil Prices, U.S. Debt Is Forced to Give Way
The trigger for this new round of interest rate increase was not new economic data, but a "refusal" from the Middle East. In the previous week, the expectation that the Federal Reserve would maintain a tighter policy had already pushed yields on U.S. Treasury bonds of various maturities to multi-year highs, setting the stage for a high-interest-rate environment, but there was a lack of a story that could reignite inflation expectations. Recently, U.S. President Trump rejected Iran's latest proposal to reopen the Strait of Hormuz, and the market immediately interpreted this as an increase in Middle Eastern energy supply risks. After the news broke, oil prices rose during Monday's Asian session as traders began to reprice future inflation: not only were current oil prices pushed higher, but concerns over whether "high oil prices could bring inflation back down" were quickly incorporated into interest rate expectations.
In this narrative, U.S. Treasury bonds are no longer the "safe haven" in the traditional sense, but have become a sell-off chip under inflationary pressure. Inflation concerns layered on top of already high expectations for rate hikes resulted in a new round of sell-offs in U.S. Treasuries: the 2-year yield rose to about 4.9%, and the 10-year yield approached 5.2%, increasing by about 5 and 4 basis points respectively in a single day, with both ends pushed higher; the 10-year yield still hovers near the high levels not seen since 2007, and the spread between the 2-year and 10-year yields shrank to about 17 basis points, marking the narrowest level since early 2025. Meanwhile, the prices and yields of sovereign bonds in Japan and Australia also rose, indicating that this is not just a U.S. story, but a collective elevation of long-term risk-free rates in the global bond market under the same inflation and interest rate fears. High long-term rates mean a recalculation of the future cash flows and narrative premiums of global stocks, credit assets, and crypto assets, putting all risk assets under a tighter ceiling imposed by high rates.
Spread Narrows to 17 Basis Points, Ghost of Recession Returns to Wall Street
When the 10-year yield was pinned at about 5.2%, what truly made traders anxious was the corresponding 2-year yield, which had risen to about 4.9%, with only about 17 basis points remaining between the two, marking the narrowest spread since early 2025. The short end increased by about 5 basis points in a single day, and the long end by about 4 basis points, indicating this is not a simple case of "long end out of control," but rather an overall upward shift of the entire curve at high levels, while the steepness continues to flatten. For veteran traders on Wall Street, this type of "high position flattening" has a clear historical scale: according to data from a single source, in the past eight U.S. economic recessions, the spread between the 2-year and 10-year yields always first narrowed from a wide positive range before eventually inverting, dragging the real economy into a downturn. This current round of narrowing has thus quickly been interpreted as "the recession signal is lighting up again."
Under this spread structure, the thought framework of traditional asset traders often shifts: from "how to bet on the interest rate hike path" to "how to lock in returns and reduce risks before a recession." One side presents a risk-free return of nearly 5%, while the other side faces possible valuation compression in stocks, credit assets, and highly volatile crypto assets as the economy slows down. Portfolio managers begin to adjust according to textbook strategies—lengthening the duration of high-rated bonds to hedge against recession risks, reducing exposure to high-beta tech and growth assets, and reallocating some funds that were originally chasing narrative and liquidity premiums back to short-term U.S. Treasury bonds and cash equivalents. Within cross-asset funding pools, this defensive rotation effectively opens up a "second discount factor" for risk assets: not only must future stories be discounted at a higher risk-free rate, but there's also the assumption of a weaker economic backdrop, leading BTC, ETH, and their dollar-pegged liquidity pools to be repriced under this unified framework of "high rates + recession expectations."
High Rates Lock In the Dollar, Bitcoin's Hedge Story Faces Test
When the 2-year U.S. Treasury yields around 4.9% and the 10-year rises to about 5.2%, approaching highs not seen since 2007, the so-called "risk-free yield" starts to create real competition with all high-volatility assets. For global funds, stopping dollars in short-term U.S. Treasuries no longer feels like a passive hedge, but rather an attractive active allocation choice. When the yield curve spread narrows to about 17 basis points, and once again, historical warning lights associated with recessions are lit, those who had been willing to pay high volatility premiums for BTC and ETH will be forced to evaluate their positions against the yield curve and historical volatility of crypto assets.
The contradiction lies in the fact that, in the current warming of recession expectations, Bitcoin is framed both as a hedge against inflation and currency devaluation, and yet in previous macroeconomic shocks, it has repeatedly been treated as a liquidity-driven high-beta risk asset. The result is that the same chain of liquidity is being pulled by two entirely different frameworks: short-term funds, upon seeing a 4.9% short-end yield and signs of a potential recession, are more inclined to reduce exposure to high-volatility coins, increase futures shorts or protective options as hedging positions, converting some chips into U.S. Treasuries and cash equivalents; while funds with a longer-term perspective might interpret "high rates + recession expectations" as laying the groundwork for a future looser monetary environment, choosing to gradually allocate BTC and ETH during fluctuations and corrections, betting on the elasticity premium of risk assets upon the next wave of liquidity return. Ultimately, which narrative the market stands behind will determine the next pricing anchor point for Bitcoin.
Dollar-Pegged Coins and On-Chain Yields: Is It Worth Overnight Risk?
When the 2-year and 10-year U.S. Treasury yields rise to about 4.9% and 5.2%, respectively, and maintain high levels in the global bond market sell-off, the role of dollar-pegged coins within the crypto ecosystem is being forced to be re-evaluated. In recent years, they have acted more like a "zero-interest cash position": pegged to the dollar, available for instant transactions in the spot and derivatives markets, occasionally generating some annualized returns in on-chain lending and market-making pools as compensation for "zero-interest dollars." Now that risk-free rates themselves are approaching 5%, with yields on sovereign bonds in Japan and Australia also rising, the overall yield curve of safe assets is shifting upward, raising the question: is it worth continuing to bear contract risk, protocol risk, and de-pegging risk for those slight on-chain extra yields?
In the relative return framework, the cost-benefit ratio of many strategies is beginning to invert. Assuming that a certain mainstream lending or staking strategy can only hover around single-digit annualized returns, it must offer sufficient risk premium above the risk-free rate to have a reason to maintain large positions in dollar-pegged coins; otherwise, the rational funding path will likely shrink first from high-leverage DeFi and long-duration mining, reverting to pure dollar-pegged token positions, treating on-chain as a short-term liquidity transit point, and then connecting to U.S. Treasuries and related products through over-the-counter channels to lock in that "visible" 4.9%-5.2%. Under the combination of "high risk-free yields + recession expectations," once this reconfiguration inertia forms, dollar-pegged coins will shift from yield tools back to purer settlement and margin-bearing vehicles, with their pricing anchor shifting from "how much interest" to "can it quickly and safely access that 5% yield off-chain."
The Real Tipping Point: What Happens to Crypto If Inversion Occurs
After Trump's refusal, the risk in the Strait of Hormuz pushed oil prices and inflation expectations up, with U.S. long-term yields again nearing their highs since 2007, while the spread between the 2-year and 10-year yields shrank to about 17 basis points. Even before the formal inversion, the market has started to pre-trade the script of "high risk-free rates + future recession," while synchronously rising yields in major economies including Japan and Australia have turned this pressure into a common constraint for the global bond market. Currently, the pricing of crypto assets is being simultaneously constrained by two chains: one is the policy uncertainty brought about by oil prices and inflation—any signals of "longer and higher" or "starting discussions on a pivot" from the Federal Reserve, in the absence of clear recent statements, will directly change the required risk premiums for BTC and ETH; the other is the yield curve itself—historically, prior to the last eight recessions, the curve has typically narrowed before inverting, making every narrowing of the spread and subsequent sustained inversion a risk preference switch. For traders, the framework must break down positions into three parts: while rates hover at high levels and the economy has yet to enter an actual recession, BTC tends to be retained as "the core holding among high-volatility risk assets," ETH is primarily used as a leveraged bet on spread and liquidity expectations, while dollar-pegged coins revert from being "interest-earning" tools back to "settlement and off-chain yield bridge" roles; leverage should revolve around a simple principle: as long as the spread has not inverted and macro data has not clearly weakened, short-cycle, low-multiple leverage still has room; once the 2–10 year spread truly inverts and sustains, and the combination of oil prices and Federal Reserve communication points to "high rates suppressing growth," the core strategy must switch to reducing leverage and increasing the proportion of dollar-pegged coins and off-chain risk-free yield assets, using time instead of leverage to withstand the recession exam signaled by the curve.
Join our community to discuss and get stronger together!
Exclusive Hyperliquid benefits for AiCoin: https://app.hyperliquid.xyz/join/AICOIN88
Exclusive Aster benefits for AiCoin: https://www.asterdex.com/zh-CN/referral/9C50e2
On-chain Telegram community: https://t.me/AiCoinWhaleData
On-chain community: https://www.aicoin.com/link/chat?cid=N6OVMor5g
AiCoin on-chain Twitter: https://x.com/aicoinwhaledata
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。