Written by: Rita
Market concerns indicate the storage cycle has peaked, yet Goldman Sachs presents an 87.4% upside potential. In a report released on September 22, 2026, following an online meeting with SK Hynix's management, Goldman reaffirmed its buy rating, setting a 12-month target price of 3,500,000 KRW. The current price is 1,868,000 KRW, representing an upside potential of 87.4%. Goldman believes that high bandwidth memory (HBM) and dynamic random access memory (DRAM) supply tightness will continue, and SK Hynix's pricing and profit margins will further increase in 2027, with long-term agreements (LTA) providing demand visibility.
Goldman analyst Giu Lee outlined five key points in the report. There is a positive outlook for recent pricing growth and HBM pricing growth next year. The technology migration focuses on existing capacity with limited cleanroom space. A positive view on LTA is reiterated. Exchange rate fluctuations may pose short-term profit impacts. Plans to further update shareholder returns are underway.
HBM Pricing Upside in the Second Half
SK Hynix expects quarterly pricing growth to continue for the remainder of 2026, driven by supply tightness, an increased high-end HBM portfolio, and a low pricing base in Q2. The pace of growth may slow. In terms of HBM, the revenue share of HBM4 is increasing, with the average selling price (ASP) and profit margin of HBM expected to rise in the second half compared to the first half. In 2027, the supply of traditional DRAM and HBM is expected to tighten, with an improved high-end product mix leading to an anticipated increase in HBM ASP.
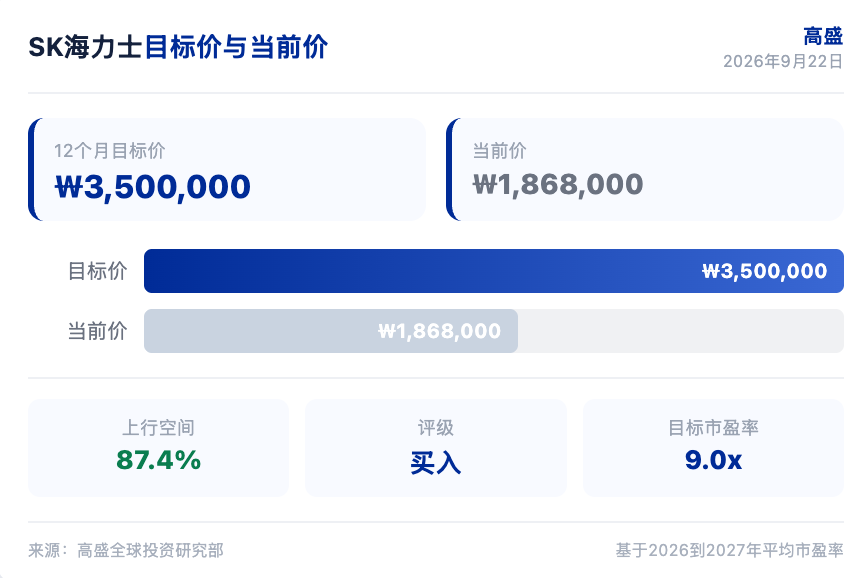
Goldman’s earnings forecast for SK Hynix reflects an expected earnings per share (EPS) of 399,504 KRW in 2026, 491,918 KRW in 2027, and 560,997 KRW in 2028. The corresponding price-to-earnings ratios are 4.7x, 3.8x, and 3.3x respectively. The target price is based on a 9x average price-to-earnings ratio from 2026 to 2027. Goldman believes the current valuation does not reflect the sustainability of the HBM pricing increase.
Technology Migration Focused on HBM
SK Hynix's existing wafer fab capacity is nearing full production. The main capacity of the M15X plant is allocated for HBM production. The Yongin plant is planned to commence operations in February 2027, with output expected only by the end of 2027. In the NAND sector, the company plans to utilize part of the space in the M17 plant and the Solidigm plant. In terms of technology migration, domestic DRAM production is shifting from the 1a nanometer node to the 1c nanometer node, and NAND production is moving from 176 layers to 321 layers, with bit crossover expected to be achieved by year-end.
Goldman points out that cleanroom space is limited, and new wafer capacity expansion is minimal. Technology migration is the main path for enhancing bit output. HBM capacity is prioritized, and the supply growth of traditional DRAM is constrained. This structure supports maintaining high storage prices.
LTA Coverage of At Least 50%
SK Hynix does not have a specific LTA coverage target, but server memory, including HBM, accounts for about 60% of DRAM revenue, and the company believes that achieving at least 50% LTA coverage is not impossible. LTAs provide demand visibility, share risks with customers, match production with demand, and improve capital expenditure efficiency. Goldman reaffirms a positive view on LTAs.
The proliferation of LTAs has changed the business model of the storage industry from spot price volatility to more predictable contract revenues. Goldman believes that increasing LTA coverage will benefit SK Hynix in planning capacity and investments, reducing earnings volatility.
Exchange Rate Impact on Short-Term Profits
Nearly 100% of SK Hynix's revenue is denominated in US dollars, while less than 50% of operating costs are in foreign currencies. Goldman points out that exchange rate fluctuations may affect short-term profits. When the dollar weakens, revenue converted into KRW decreases, while the cost side is less affected by exchange rates, which could pressure profit margins.
Goldman believes that the exchange rate impact is a short-term disturbance and does not alter the mid-term logic of HBM pricing increases and the enhancement of LTA coverage. Investors should focus on the impact of exchange rates on quarterly earnings rather than viewing it as a trend change.
Shareholder Returns Awaiting Update
Details of SK Hynix's next round of shareholder returns will be determined during the Q3 2026 earnings report, as the company balances between buybacks and dividends. Goldman believes that updating shareholder returns is a potential catalyst for stock prices.
If the company announces a large buyback or increases dividends, it will boost market confidence. Goldman points out that during the storage upward cycle, improved cash flow provides room for shareholder returns, but capital expenditure needs remain a priority.
Goldman maintains its buy rating with a target price of 3,500,000 KRW. Key risks include deterioration in storage supply and demand, delays in technology migration, weak demand for smartphones, PCs, and servers, progress of Samsung's HBM business, and decreased AI-related capital expenditure. If HBM pricing continues to rise in 2027, SK Hynix's earnings forecast has upside potential.
Disclaimer
This article is an organization and interpretation by Chao Xiang Research of a third-party brokerage research report (Goldman Sachs, September 22, 2026), combined with public market information. The ratings, target price, earnings forecasts, and related judgments quoted in this article are the views of the brokerage analyst and only represent the position of their respective institution, not the views of Chao Xiang Research, nor does it constitute any investment advice.
Markets are risky, and decisions should be independent. This article should not be relied upon as a basis for buying or selling any securities.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


