Written by: Rita
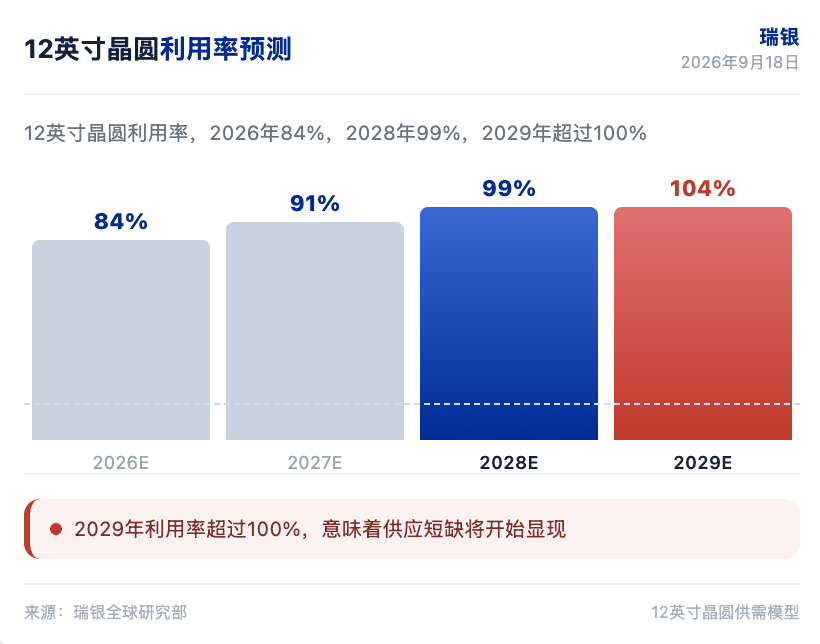
The market views wafers as beneficiaries of the cyclical rebound, but UBS believes that price increases are a prerequisite for expansion. In the global wafer industry report published by UBS on September 18, 2026, it pointed out that the supply-demand outlook for 12-inch and 8-inch wafers will continue to improve over the next two years, with the utilization rate of 12-inch wafers expected to rise from 84% in 2026 to 99% in 2028. However, new capacity expansion requires a price increase of more than 40% to 50% to incentivize manufacturers; otherwise, a severe shortage may occur after 2028. UBS gives a buy rating to Shin-Etsu Chemical, GlobalWafers, and Siltronic, and a neutral rating to SUMCO.
The core judgment of UBS is that wafer manufacturers remain cautious about expansion after experiencing a downturn from 2023 to 2025. The current operating profit margin is only 12.3%, and the return on equity is 6.8%, far below the 18.3% and 19.1% from 2017 to 2022. Major customers need to use higher prices to incentivize manufacturers to expand; otherwise, supply shortages will limit growth across the semiconductor industry.
Tight supply and demand will last until 2028
UBS has raised its demand growth forecast for 12-inch wafers in 2026 from 9% to 11%, with growth rates of 14% and 13% predicted for 2027 and 2028, respectively. Demand for 8-inch wafers is expected to grow by 11% in 2026, with 9.9% and 8.8% growth in 2027 and 2028, respectively. The utilization rate for 12-inch wafers is projected to be 84%, 91%, and 99% from 2026 to 2028, up from previous forecasts of 82%, 88%, and 94%. The utilization rates for 8-inch wafers are expected to be 80%, 90%, and 97%.
The upward revision in demand mainly comes from an increase in customer inventory restocking needs and accelerated expansion of DRAM capacity. UBS points out that supply and demand conditions in 2027 will be tighter than in 2026, and the utilization rate in 2028 will approach full capacity. If manufacturers do not expand, the utilization rate in 2029 will reach 103.7%, and supply shortages will begin to emerge that year.
A price increase of 40% is needed to incentivize expansion
UBS expects that wafer prices may rise by more than 20% per year from 2027 to 2028, similar to the upswing period of 2017 to 2018. However, the key argument is that major customers need to use higher prices to incentivize wafer manufacturers to consider expanding new capacity in 2028 and beyond. Industry feedback indicates that wafer manufacturers may need to see price increases of 40% to 50% before they would consider expanding production.
Major wafer manufacturers remain cautious about expansion due to a significant decline in profitability during the downturn from 2023 to 2025. UBS points out that if manufacturers do not expand, severe shortages may occur after 2028, limiting growth in the semiconductor industry. Under this logic, price increases are not only the result of a cyclical rebound but also a necessary condition for new capacity expansion. The cautious attitude of wafer manufacturers and the expansion demand from customers have created a deadlock that needs to be resolved through pricing.
The impact of Chinese competition is controllable
Chinese wafer manufacturers are actively expanding, but UBS believes the impact on global supply and demand from 2027 to 2028 will be limited. The opportunities in China may mainly be confined to new mature logic wafer fabs, and leading Chinese logic and memory customers, for yield reasons, are more inclined toward overseas wafers. For non-Chinese customers, it is challenging to use a significant quantity of Chinese wafers in mature logic foundry due to the need for re-certification, and the performance of advanced logic and memory is lagging.
NSIG is the largest wafer manufacturer in China, with an average selling price of 12-inch wafers at $54, while the industry price ranges from $100 to $120, reflecting that most of its shipments are still non-production wafers. UBS believes that Chinese manufacturers have limited competitiveness in the high-end wafer sector, and the global supply-demand landscape will not be significantly altered by Chinese expansions. The pace of expansion and product structure of Chinese manufacturers determine that they will find it difficult to enter the global high-end supply chain in the short term.
Buy Shin-Etsu and GlobalWafers
UBS gives a buy rating to Shin-Etsu Chemical, GlobalWafers, and Siltronic, and a neutral rating to SUMCO. The target price for GlobalWafers has been adjusted down from 2000 New Taiwan Dollars to 1750 New Taiwan Dollars, based on a forward price-to-book ratio of 7.5 times, down from 8.5 times. UBS has lowered its earnings per share forecast for GlobalWafers by 7% for 2026 and by 14% for 2027 and 2028, but expects sales growth to accelerate in the fourth quarter of 2026 and in 2027.
The target price for Siltronic has been raised from 105 Euros to 120 Euros. SUMCO maintains a neutral rating with a target price of 4000 Japanese Yen. UBS points out that the price-to-book ratio for the wafer sector has adjusted from 3.3 times in July 2026 down to 2.6 times, which is at the midpoint of the 1.0 to 4.0 times range over the past decade, and this adjustment provides a buying opportunity for the structural upcycle.
If wafer prices rise by over 20% in 2027 but manufacturers still do not expand, the supply shortage in 2029 will become the next bottleneck for growth in the semiconductor industry.
Disclaimer
This article is a整理与解读 of research reports from third-party brokerage firms (UBS, September 18, 2026) by Chao Xiang Research, combined with整理 of public market information. The ratings, target prices, earnings forecasts, and related judgments quoted in this article are all the opinions of the analysts of the brokerage firm and represent only the position of their affiliated institutions, not the views of Chao Xiang Research, and do not constitute any investment advice.
The market has risks, and decisions should be made independently. This article should not be used as a basis for buying or selling any securities.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


