This article is co-produced by PANews and BIT US Stocks, BIT US Stocks offers over 10,000 US stocks and ETFs, supports stablecoin deposits and withdrawals and traditional USD wire transfers, enjoying full shareholder rights and dividend voting rights.
Bitcoin Breaks Above the 50-Week Moving Average, SEC "Innovation Exemption" Sparks the Market
The crypto market has given a clear signal after a period of consolidation, with Bitcoin surpassing $84,000 on September 21, peaking at $84,918 and almost achieving five consecutive daily gains. Altcoins also warmed up, with Ethereum surpassing $2,700, ZEC breaking $1,500, and NEAR soaring to $4.45, nearly doubling within a week. The funding situation also improved: Bitcoin spot ETFs have seen substantial net inflows since August, with a weekly peak of $1.92 billion, reaching a new high in nearly a year; Ethereum spot ETFs recorded positive inflows for three consecutive months starting in July, with a monthly total of $1.85 billion in August. Strategy founder Michael Saylor released another orange signal, hinting that further accumulation may continue; the company has repurchased about 3,000 Bitcoin since the end of August, increasing total holdings to approximately 845,050 Bitcoin, valued at about $68.76 billion. Bitmine's Ethereum holdings have also risen to 5.85 million coins.
Most traders view $80,000 as a key support level, with the $82,000 to $83,000 range seen as major resistance. Galaxy research director Alex Thorn pointed out that Bitcoin reclaimed the 50-week moving average on the weekly chart for the first time in 45 weeks, which historically often confirms the bear market bottom. Glassnode shows that the adjusted SOPR seven-day moving average has returned above 1, indicating that most selling is at a profit, but buying power can still absorb selling pressure, displaying typical bull market characteristics. Doctor Profit believes that if the week closes above about $78,700, which is above the 50-week moving average, it will confirm a new round of upward momentum; breaking through $82,500 to $83,000 will create a stronger signal, targeting $88,000. Traders like Ella emphasize that $82,000 is a critical level for changing the chart structure, with dense short liquidation zones in the $83,000 to $86,000 range; once broken, it may accelerate upward; if it falls below $80,000, it will look back at $78,800 to $79,300. Killa notes that visible short liquidation volumes of about $5 billion are concentrated between $83,000 and $85,000, making chain buying easier to form in an upward trend.
Regarding the upcoming market trends, BIT Asset Management head Daniel YU pointed out three major risks to pay attention to. First is the quarterly crypto options expiration on September 25, which carries about 43% of Bitcoin open contracts; coupled with the "Silver Week" long holiday in Japan leading to thin liquidity, the market is highly susceptible to "pin effects" and violent fluctuations caused by hedging unwinds; second is macro-duration impacts; although regulatory positives temporarily obscure pressures, the reality of the 10-year US Treasury yield returning to 5% cannot be ignored; finally, there is the technical gaming aspect, as the market tests whether $80,000 can convert from resistance to support. Attention should also be paid to the pressure above the $82,000 to $82,300 range from the September 3 peak, while the support range below is $77,500 to $78,500.
Today's Highlights:
Zilliqa will complete the migration of ZIL on exchanges with its second hard fork on September 22
The Sandbox releases claims process for attack incidents, claim window closes on September 22
SPACE ID (ID) unlocks approximately 69.88 million tokens, worth about $2.4 million
Starknet (STRK) unlocks approximately 127 million tokens, worth about $3.6 million
Upbit 24-hour trading volume ranking: XRP, BTC, ETH, G, ZETA
Bitcoin spot ETF saw net inflows of $6.2137 million last week
Ethereum spot ETF experienced net outflows of $140 million last week, ending four weeks of net inflows
HYPE spot ETF saw net inflows of $3.0645 million last week
XRP spot ETF recorded net inflows of $9.5592 million last week
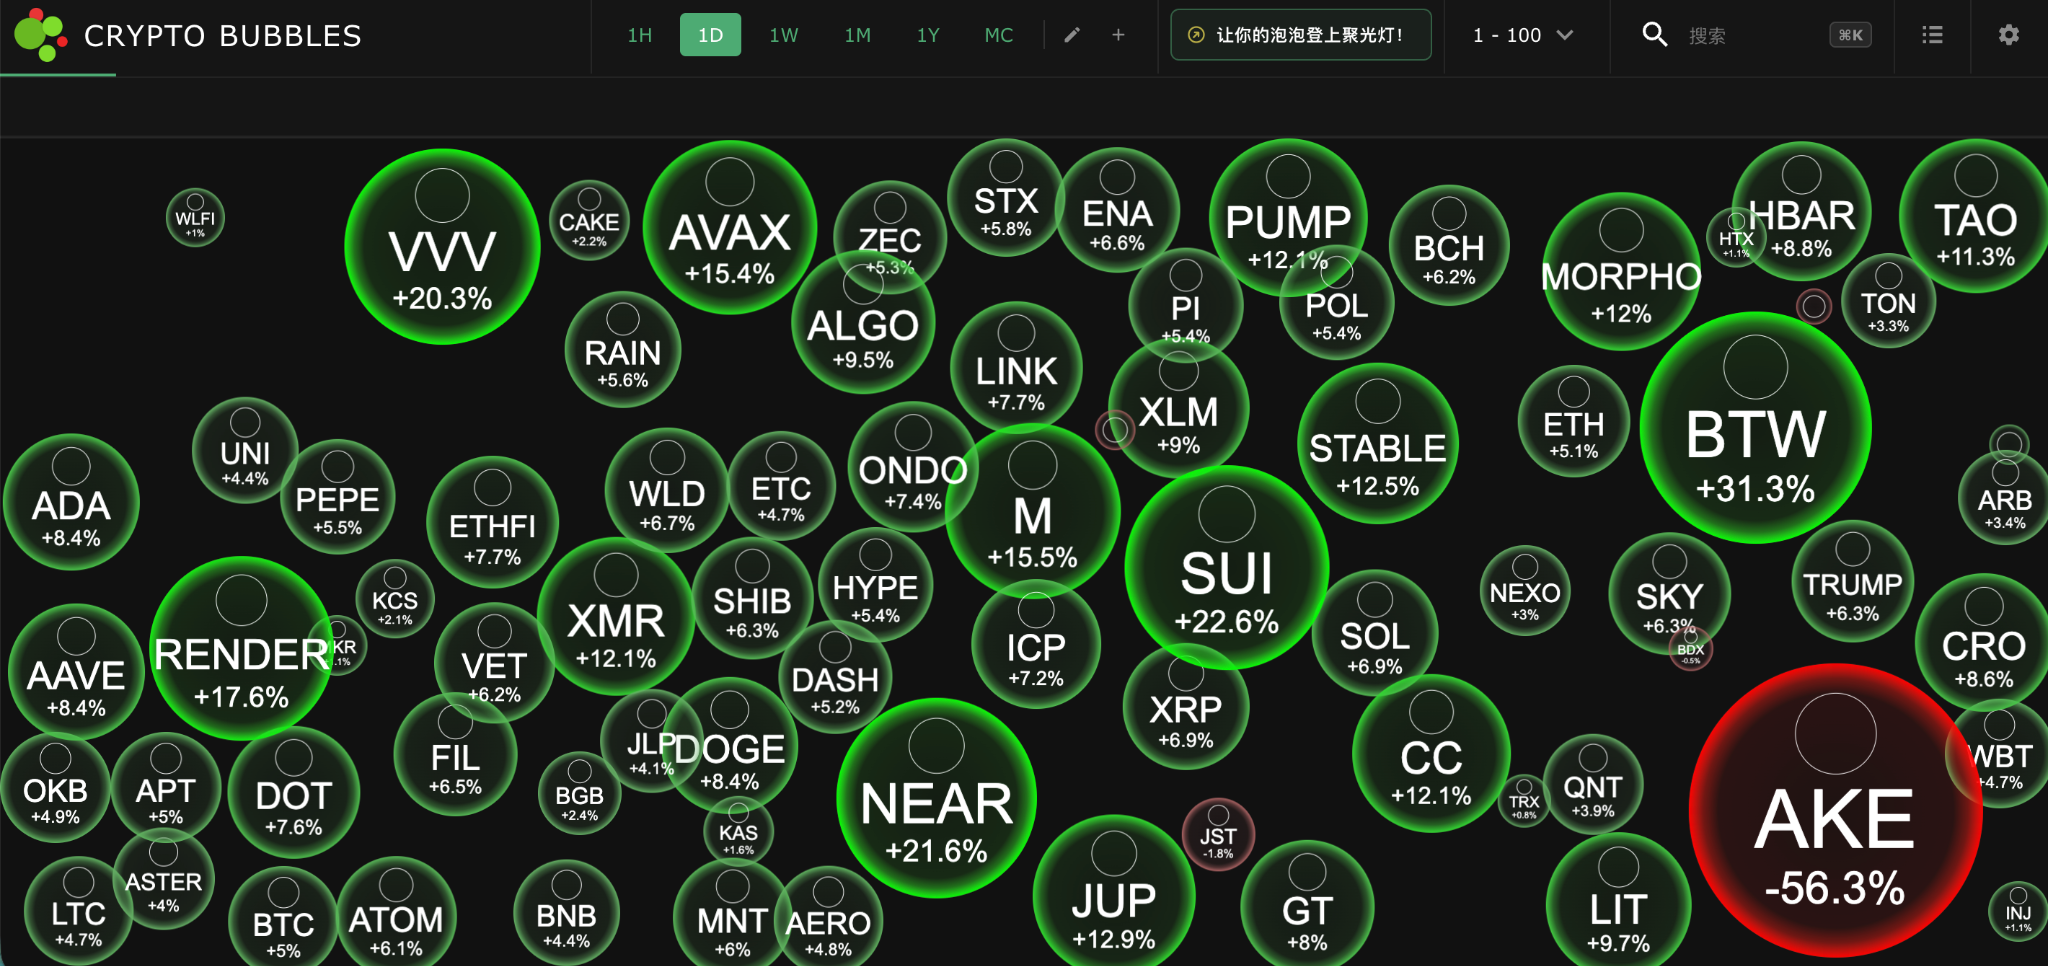
Today, the largest gains among the top 100 cryptocurrencies by market cap: BTW up 31.3%, SUI up 22.6%, NEAR up 21.6%, VVV up 20.3%, RENDER up 17.6%.
NASDAQ Futures Rise Moderately, Semiconductor and Greenland Concept Stocks Surge in After-Hours
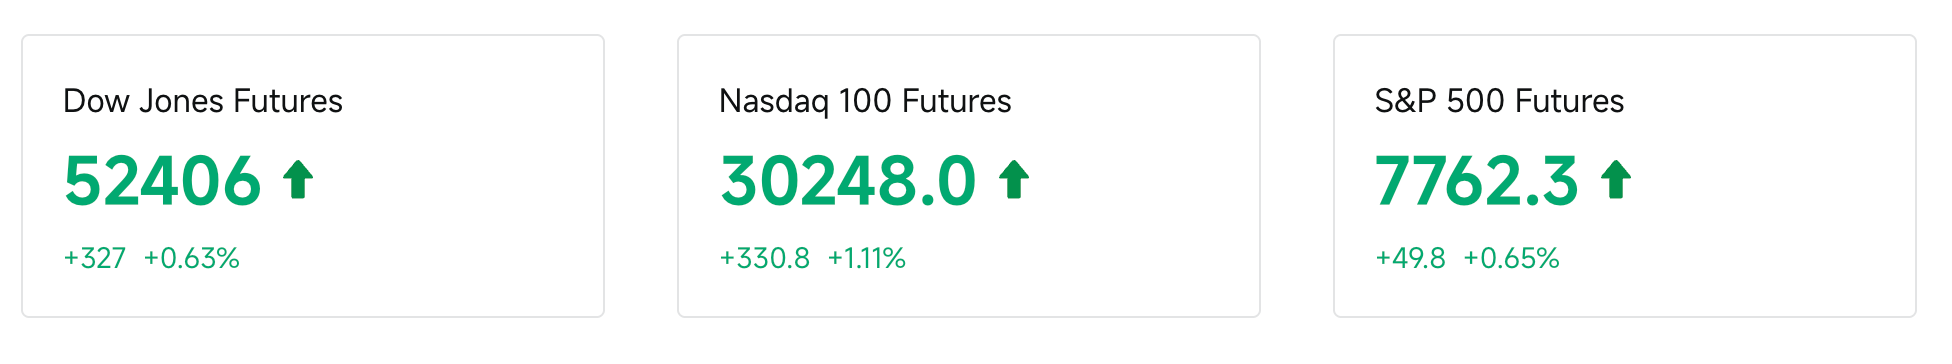
The major US stock index futures rose collectively, with NASDAQ 100 futures up 1.11%, S&P 500 futures up 0.65%, and Dow futures up 0.63%.
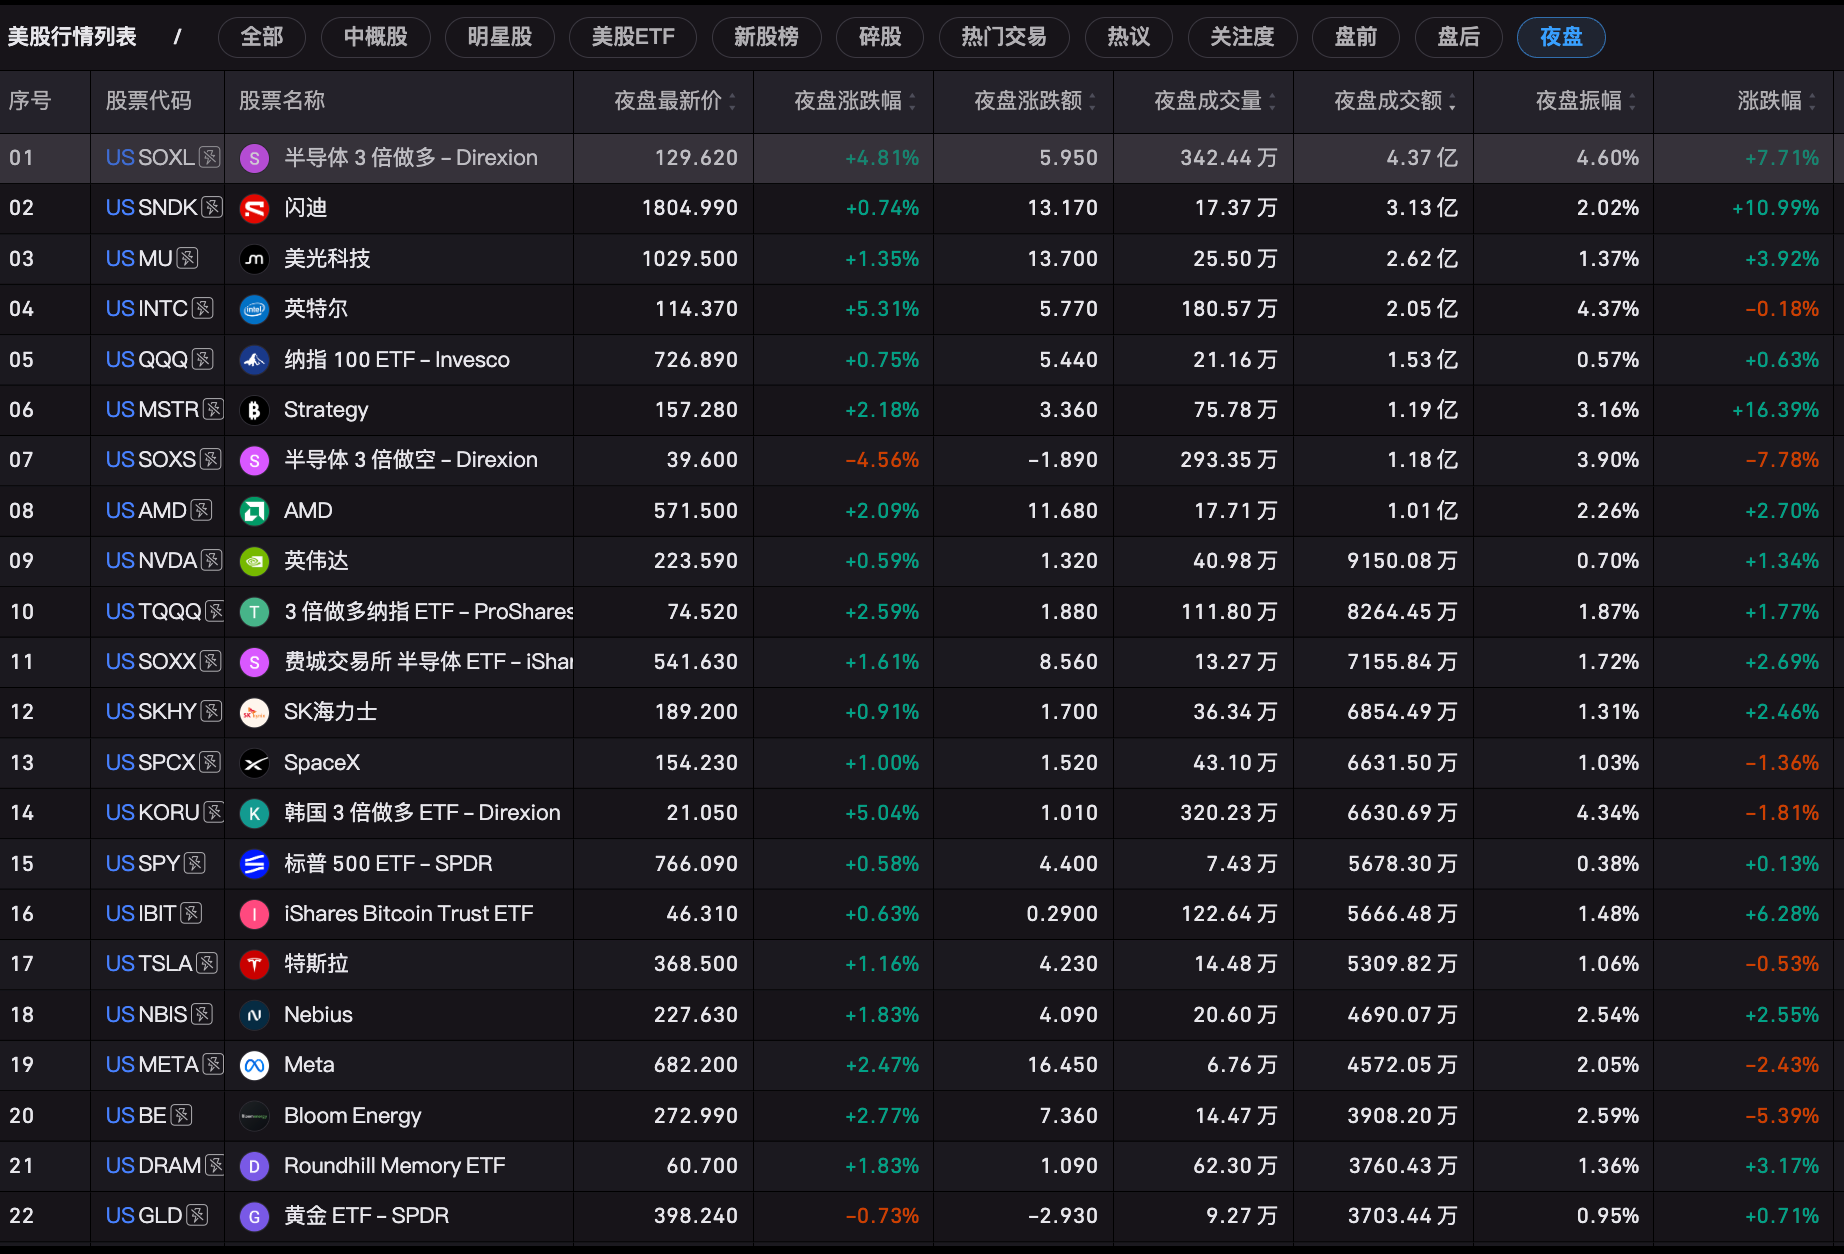
BIT after-hours data shows that chip stocks continued their after-hours rally bolstered by bullish options, with the semiconductor 3x long ETF soaring by 4.81%, AMD rising 2.09%, Micron Technology increasing 1.35%, Meta up 2.47%, and Bloom Energy rising 2.77%.
Intel US stocks rose more than 5%, as the company collaborates with AUO to venture into advanced Micro LED packaging, aiming at CPO and high-density computing integration markets;
Bloom Energy rose nearly 4% as the company is set to be included in the S&P 500 index after adjustments effective Monday;
Accenture rose over 6% as it partners with Anthropic for independent assessments of AI models;
Novo Nordisk fell over 5% as it announced plans to expand oral GLP-1 obesity patient service capacity to 10 times its current level by 2030 and intends to launch over five major products;
Encouraged by the strong security and defense agreements between Denmark and Greenland, Greenland resource stocks surged collectively, with Greenland Energy soaring over 100%, Greenland Mines skyrocketing 58%, and Critical Metals up 40%.
Rate Hikes Fail to Dampen Computing Power Expansion, Crypto Concept Stocks Rally Across the Board
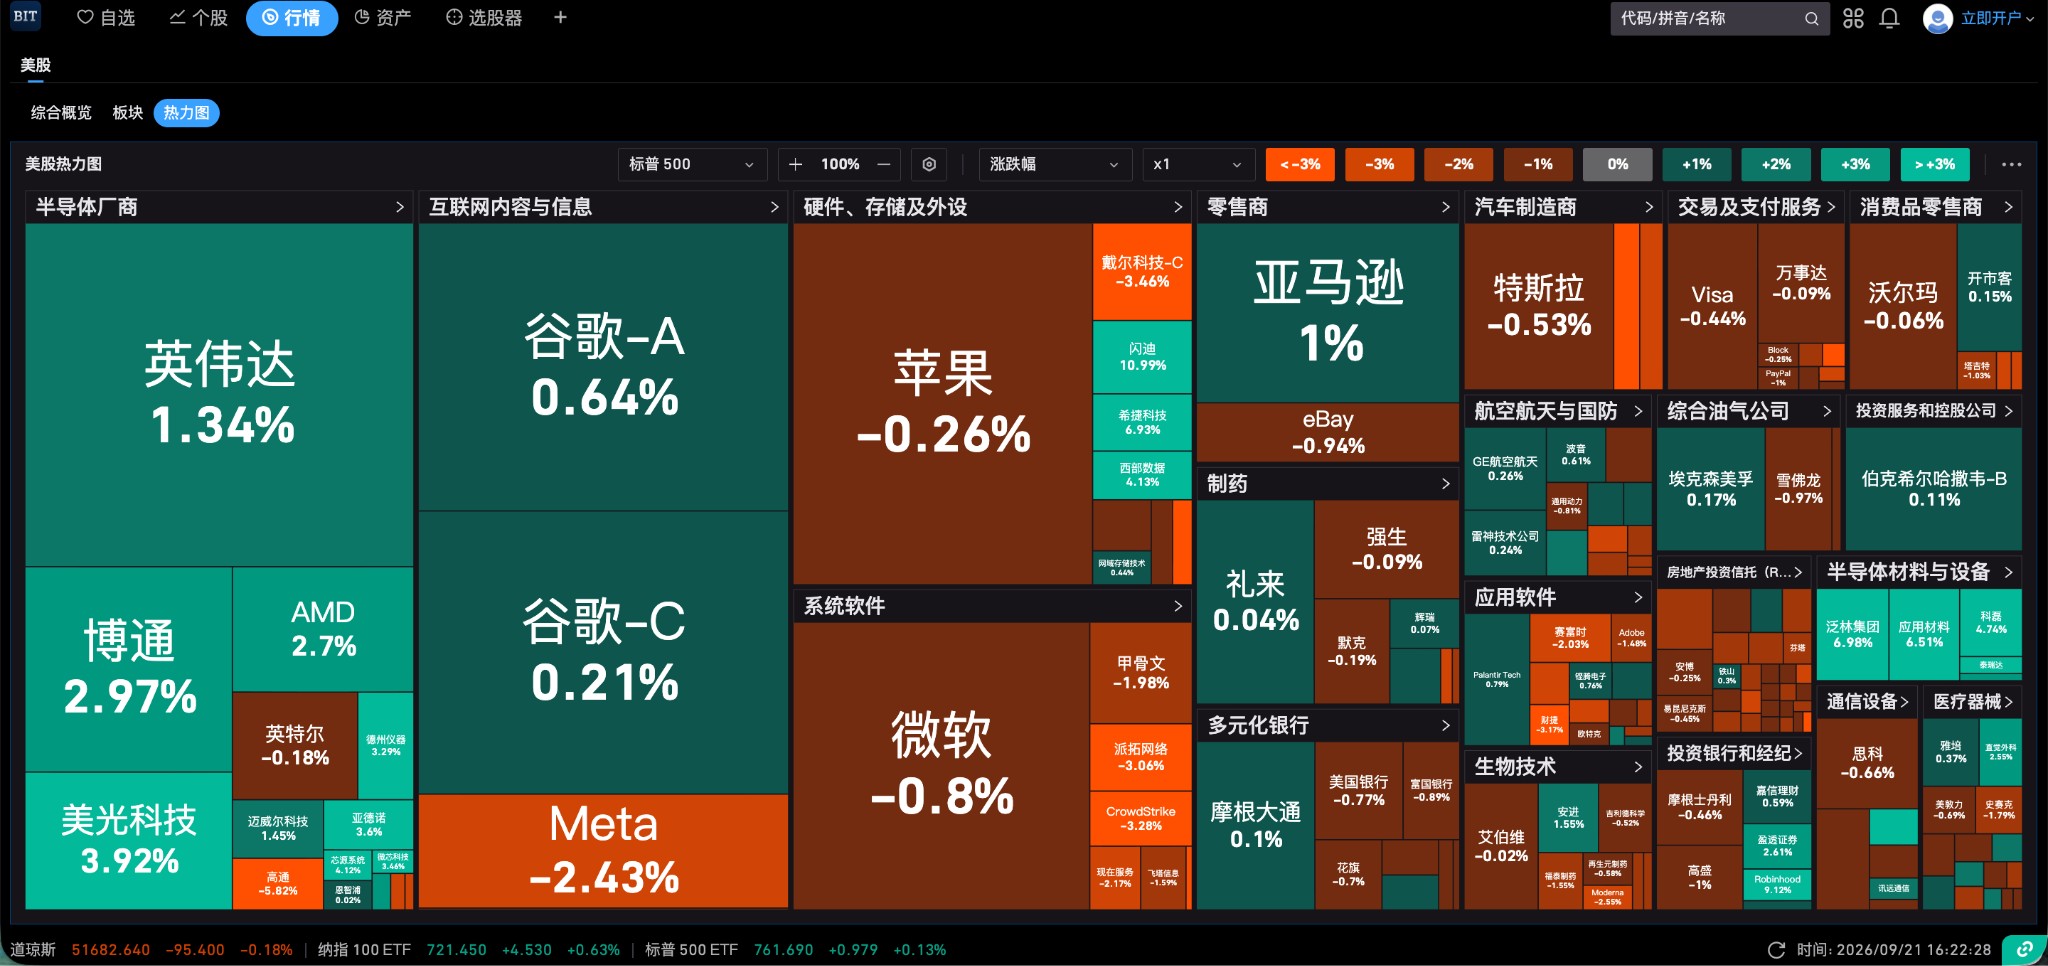
Last Friday, the Dow fell 0.18%, while the NASDAQ rose 0.39% and the S&P 500 gained 0.17%; for the week, the Dow fell about 1.7%, but the NASDAQ rebounded based on chip stocks. The Philadelphia Semiconductor Index grew nearly 2.8%, with nearly $96 million in bullish options concentrated in stocks like Sandisk and Micron.
UBS's latest assessment report further boosts market sentiment, stating that global AI capital expenditures will approach $1 trillion by 2026 and rise to about $1.4 trillion by 2027, with nearly 90% of the increase coming from a significant rise in memory costs, where memory will account for 64% of expenditures, up from 14%. Jensen Huang rebuffed the AI apocalypse theory again, stating that the chance of destroying the world before 2030 is zero, and advocated for speeding up rather than slowing down progress. Trump announced plans to form an "AI Force" and appoint a chief, claiming AI could account for 25% of US GDP. The NASDAQ 100 quarterly rebalancing will take effect before the market opens on Monday, with SpaceX's weight rising significantly from about 1.28% to 2.82%, which passive funds tracking that index must follow up on with purchases.
Additionally, US-China trade discussions opened in New York and deliberated on AI topics, alongside expectations of US-Iran contacts ahead of the UN General Assembly, providing emotional support for risk assets. Wall Street generally believes that a substantial retreat in oil prices and specific agreements being reached are key variables for the next phase.
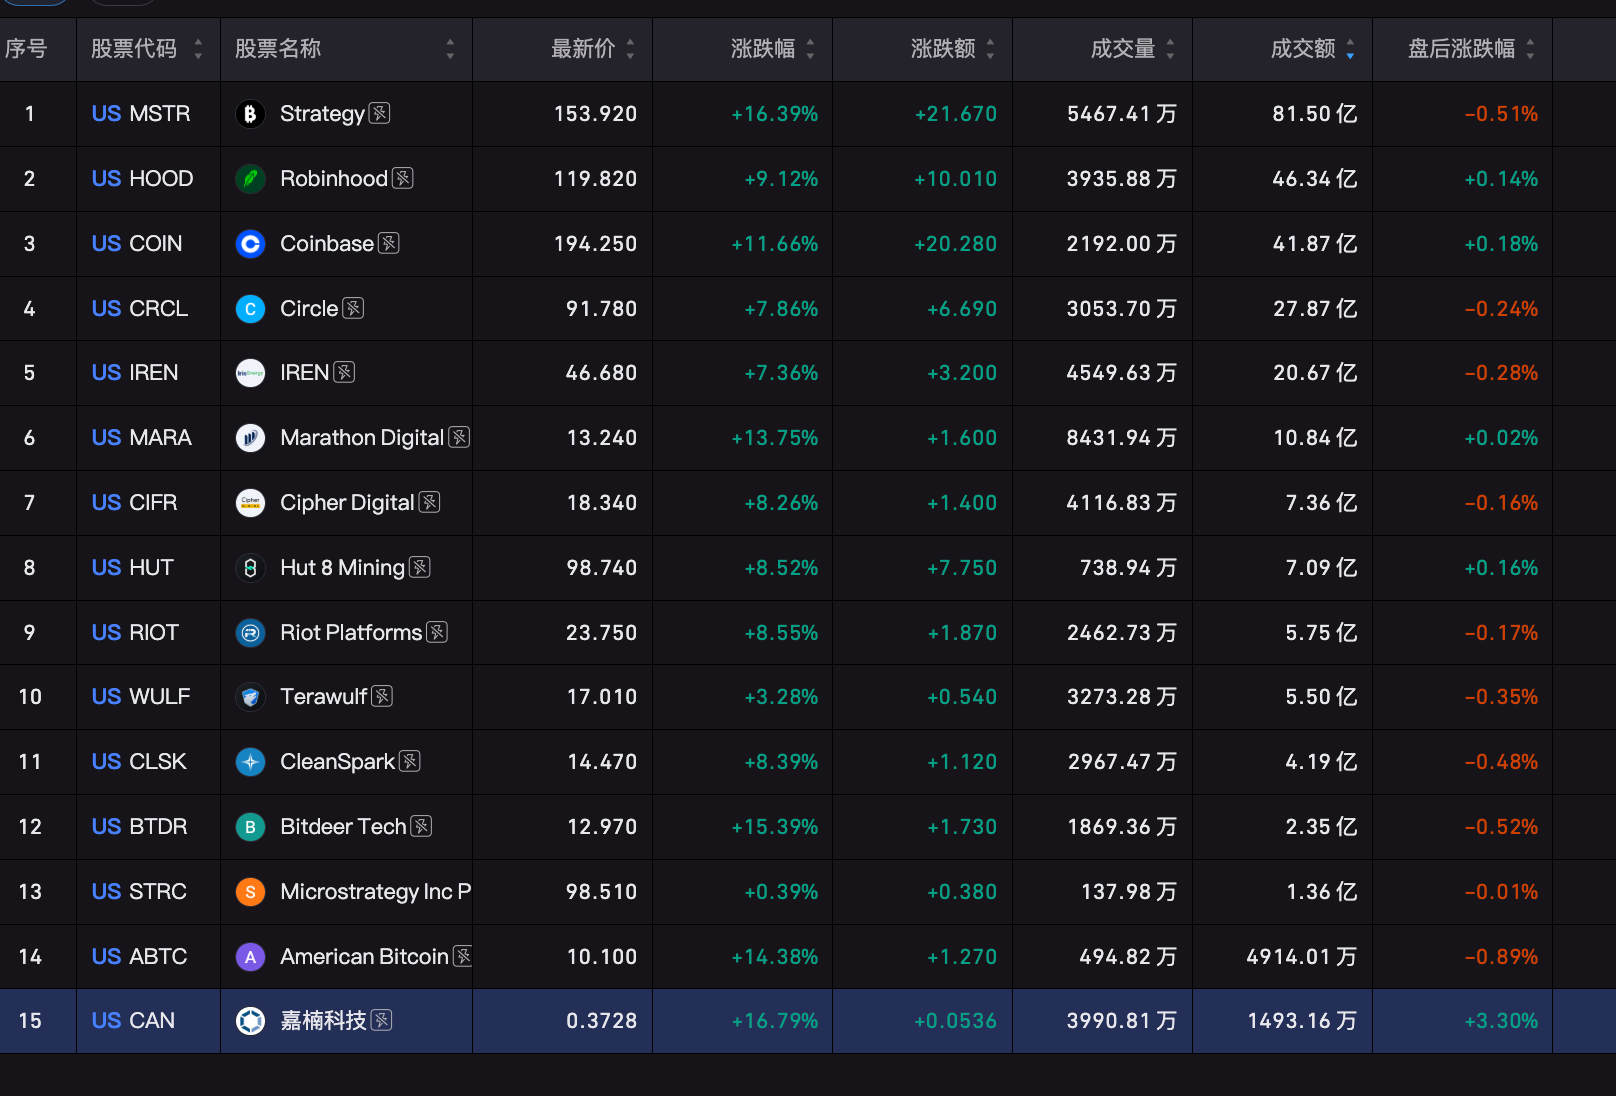
Crypto concept stocks surged across the board, according to BIT US Stocks, with Strategy soaring 16.39%, Coinbase up 11.66%, Robinhood increased by 9.12%, and Circle rising 7.86%.
Mining companies also erupted, with Marathon Digital rising 13.75%, Bitdeer soaring 15.39%, Canaan Creative increasing 16.79%, and Riot, Hut 8, CleanSpark, and others rising by over 8%.
South Korea Surpasses 7,000 Points, Druckenmiller Plans to Visit Korea
The Nikkei 225 index previously rose sharply by 1.38% driven by a significant depreciation of the yen due to the central bank raising rates to 1.25%. Starting today, due to a three-day holiday, cross-market arbitrage funds are temporarily shifting focus to Seoul and Greater China markets.
The South Korean Composite index closed up 1.65%, mainly driven by expectations of a storage super cycle and foreign capital interest: Bank of America recently upgraded the total size of the memory market to $2 trillion by 2030, and noted that DRAM prices surged 20%-30% quarter-over-quarter in Q3, with large-scale cloud providers forced to sign contracts locking in higher prices for the first quarter of next year. Foreign investment tycoons are accelerating their entry; global macro-investing legend Stanley Druckenmiller is officially conducting investigations in Korea, and even though he has reduced exposure to AI, he is still personally researching semiconductor materials and high-bandwidth memory leaders.
The A-shares also performed strongly today, with the Shanghai Composite index rising 0.97%, the Shenzhen Component index increasing 0.65%, and the ChiNext index up 0.80%, with about 4,500 stocks in the market rising. Funds mainly targeted innovative drugs, CROs, real estate, consumer sectors, and large financials. The innovative drug sector witnessed a collective explosion, while real estate accelerated in the afternoon; micro-cap stock indices rose over 3%, demonstrating a clear recovery in risk appetite.
Hong Kong stocks also showed strength, with the Hang Seng Index rising 1.18% to reclaim 25,000 points, and the Hang Seng Tech Index up 0.40%. Tencent rose 2.63%, Alibaba-W up 3.02%, Xiaomi increased by 4.47%, with innovative drugs and PCBs becoming the two most active main lines. Alibaba is set to hold the Cloud Summit, and Citigroup expects the company to reinforce its full-stack AI capabilities and long-term capital expenditure goals; Shenghong Technology rose sharply on rumors of large customer orders from North America, though the company has made it clear that specific customer cooperation details are confidential and has not committed to future performance growth.
Next Attention Points:
September 21 (Monday)
The Japanese market will be closed from the 21st to the 23rd: liquidity during the Asian session will decrease, and the expected yen intervention may amplify exchange rate fluctuations and cross-market hedges.
US-China trade discussions from September 19 to September 23: both parties have begun exchanges on trade, investment, and AI issues; subsequent attention will focus on whether specific arrangements appear regarding tariffs, technological restrictions, and investment access. Substantial progress is expected to boost Chinese concept stocks and technology supply chains; only positive statements may not support sustained upward movement.
16:00 NASDAQ 100 and S&P quarterly adjustments take effect: SpaceX's weight increases from 1.28% to 2.82%; the S&P 100 includes Palo Alto Networks, Arista Networks, Sandisk, and Dell; the S&P 500 includes Bloom Energy and Illumina. Pay attention to the passive restructuring and the profit-taking of funds that arranged in advance, as an increase in weight does not guarantee a post-effect rise.
AICC AI Computing Conference and Shanghai AI Application Ecological Conference: the former focuses on the power base in the era of intelligent agents, while the latter discusses the implementation of enterprise agents from the 21st to the 22nd. Whether servers, optical modules, liquid cooling, and enterprise software can obtain real orders is more important than just product displays.
Trump's fundraising speech for the Republican Party in New York: pay attention to discussions surrounding tariffs, AI, fiscal and energy policies, especially to guard against potential trading opportunities and risks arising from informal remarks.
September 22 (Tuesday)
The opening of the UN General Assembly's general debate, with Trump expected to speak: whether the US contacts Iran and whether negotiations can resume will directly affect crude oil, gold, and safe-haven assets. Negotiation news could lower risk premiums, but supply recovery still requires the implementation of aviation and ceasefire measures.
Trump plans to meet with representatives from Gulf countries: focusing on discussions involving Saudi Arabia, the UAE, Qatar, Bahrain, Kuwait, and Oman, with an emphasis on the security of energy facilities and the protection of transportation in the Strait of Hormuz and the Mandeb Strait.
Trump plans to meet with Zelensky and Kishida: the focus of the Russia-Ukraine talks will be whether mutual attacks on energy facilities can be halted, affecting diesel supply and oil prices; the US-Japan talks will focus on trade, security, and industrial cooperation. The specific timing is still to be confirmed.
Druckenmiller plans to visit Korea: focusing on whether exchanges with Samsung, SK Hynix, and Doosan can lead to investment arrangements. If funds truly land, it may strengthen storage, power equipment, and Korean AI supply chain valuations.
Alibaba's Cloud Summit will be held from the 22nd to the 24th: focusing on models, Agent, Agentic Cloud, and the release of the "five layers of full stack," paying particular attention to pricing, customer adoption, and revenue conversion rather than just technological parameters.
GMIF Global Memory Industry Innovation Summit from the 22nd to the 23rd: focusing on HBM, DRAM, NAND supply and demand and capacity expansion plans. If price increases and long-term orders are confirmed, the storage sector may continue to benefit; if expansion is too rapid, future supply pressure may increase.
Apple's new Mac mini and Mac Studio officially go on sale: focus on new product deliveries, inventory, and high-end model demand, assessing whether AI features can drive upgrade cycles and stimulate chip, storage, and overall supply chains.
The 14th trial flight of SpaceX's Starship is planned: data suggests the mission involves the first orbital attempt, specific windows and targets need confirmation from the company. The progress of the test flight may impact commercial space and satellite communication sentiment.
USD 69 billion 2-Year Treasury auction: focus on subscription demand and transaction yield. Weak demand may push up short-end rates, suppressing tech stock valuations.
September 23 (Wednesday)
Iranian President Raisi plans to speak at the UN: focus on negotiating conditions, ceasefire guarantees, and Strait of Hormuz opening arrangements, assessing whether the diplomatic window has a basis for execution.
Meta Connect will be held on the 23rd to 24th: focus on smart glasses, XR devices, and AI functions, particularly looking at price points, shipping plans, and service revenue, affecting consumer electronics and edge AI expectations.
Qualcomm Snapdragon Summit will be held in Beijing from the 23rd to the 25th: focus on 2nm Snapdragon new products, power consumption improvements, and customer adoption. Rumored performance, power consumption, and initial models must all be officially released to verify.
USD 70 billion 5-Year Treasury auction: testing market judgments about future interest rate paths. Strong demand could relieve the pressure from continuous supply on the bond market.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


