Author: Surf
Core Findings
The following conclusions are based on 787 million transactions from the Polymarket international market from January to June 2026, 1,733,011 wallets, and combined with market-level data from Polymarket US.
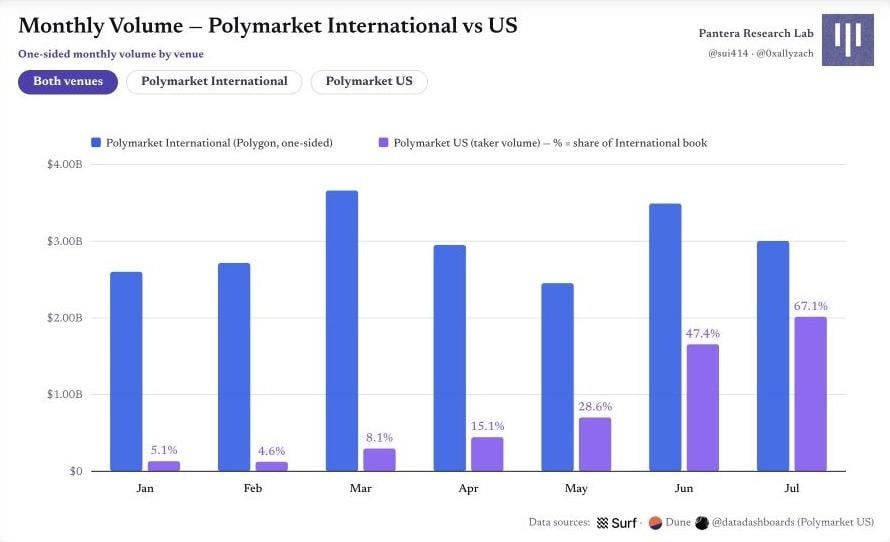
The second Polymarket is growing rapidly: the share of monthly transaction volume in the US market, regulated by the CFTC, has increased from 5% in January to 47% in June, and further to 67% in July.
The high turnover categories are the fee engine: the sports and crypto markets contributed about 98% of the gross fees of approximately $184 million for the international market in the first half of the year; the crypto market generated $96.3 million in fees with about half the transaction volume, surpassing the sports market's $83.5 million.
There is a significant mismatch between user numbers and transaction volume: retail wallets account for about 90% of users, but bots and professional users together contribute about 80% of taker transaction volume; only 5.9% of bot wallets accounted for about two-thirds of the transactions.
Attracting new users is not about betting on a single hot product: the largest single traffic market in the first half of the year brought in less than 7,000 new wallets, while there were approximately 1.13 million new wallets in total; in any given month, the top 15 traffic markets accounted for only 8%-19% of new wallets.
No single market category significantly enhances platform retention: about 51%-57% of monthly active wallets come back the following month, but users often leave the category they initially entered and switch to other categories on the platform.
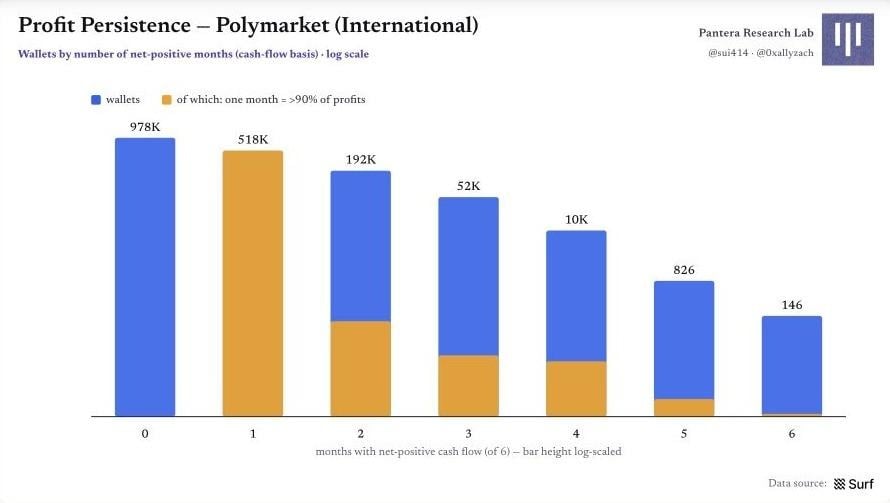
The bot group is generally profitable, but the median remains in the red: the bot sample achieved about $108 million in net gains, with only 27% of wallets profitable; among approximately 1.75 million wallets, only 146 wallets maintained positive cash flow for six consecutive months.
Part One The Panorama of Two Polymarket Markets
Polymarket US: The Second Market is Taking Shape
In the first half of 2026, Polymarket effectively became two trading venues, while discussions have mostly focused on just one. The international market, aimed at non-US users, continues to operate on an off-chain CLOB settled on Polygon, with a unilateral transaction volume of $17.9 billion over six months; meanwhile, Polymarket US, which launched at the end of 2025 and is regulated by the CFTC, saw its share of monthly transaction volume grow from 5% in January to 47% in June, and reached 67% in July (approximately $2 billion to $3 billion).
Both markets share a brand and basic order book mechanism but do not share the order book, user base, or income structure. Like Kalshi, they employ off-chain matching and a central limit order book and use the same fee curve for takers that varies with price: fee = Θ·C·p(1−p). The difference lies in the settlement channels: the international market publicly settles each transaction on Polygon, while the US market clears through a private, regulated ledger.
When comparing across platforms, it is essential to standardize the metrics. The volume discussed here refers to unilateral, taker side, and one-time counted actual transaction dollars; nominal amounts and bilateral counts are generally 2-3 times higher. Recalculating the July data using this metric gives common figures of $41 billion / $7 billion / $5 billion corresponding to about $13.3 billion / $3 billion / $2 billion.
Figure 1|Monthly Unilateral Transaction Volume of Polymarket International Market and US Market
The daily transaction volume in the US market increased from about $1 million at launch to $50 million to $100 million in July; daily transaction counts exceeded one million, and open interest once surpassed $150 million. The fee structure shifted from a fixed basis point model in January to a price-sensitive formula employed in April.
Figure 2|Polymarket US: Daily Market-Level Metrics Since Launch
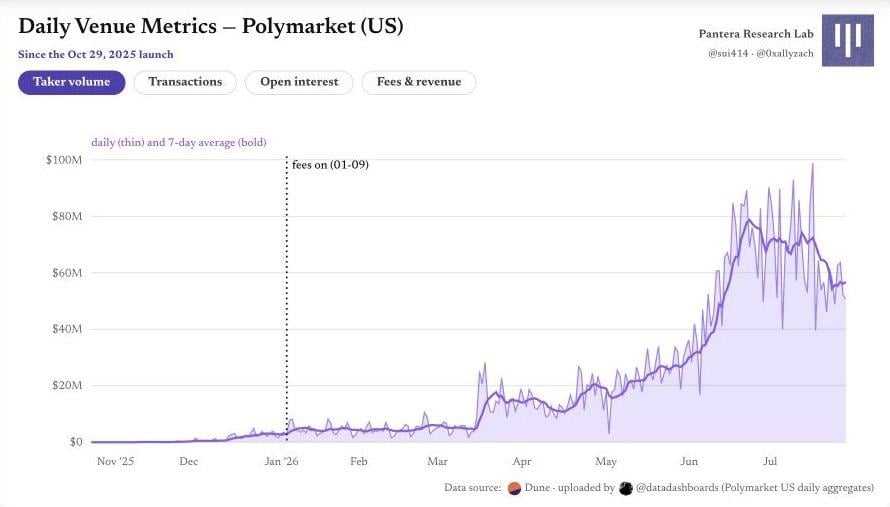
The scale of fees is also larger than what the community dataset estimated: in June alone, taker gross fees amounted to about $30 million. Based on the official rebate program estimation—25% rebated to makers upon transaction completion, following the end of a full taker promotional rebate on April 30, and thereafter on a tiered basis according to transaction volume—retained income in June was approximately $17 million, about double the fixed 25% assumption adopted by many trackers. Since there is no user-level data available for the US market, the tiered qualifications for large takers can only reference the structure where the top 0.3% takers in the international market contribute about 63% of the transaction volume.
The Fee Economics of the International Market
What exactly is being traded on the international market? Sports account for about half of the total transaction volume; crypto about 30%, with the vast majority being five-minute micro markets for ups and downs; world/geopolitical accounts for around 15%. The concentration differences between categories are even more pronounced: the largest market in sports only accounts for 0.27% of its category, while in the science and technology category, a market asking "Will the US confirm the existence of aliens before 2027?" occupies about one-fourth.
Figure 3|Polymarket International Market: Transaction Volume Broken Down by Market Category
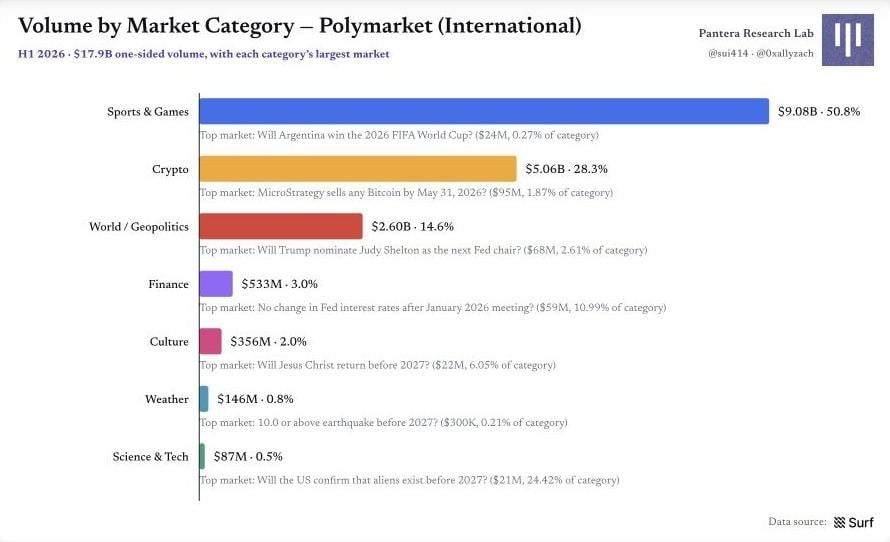
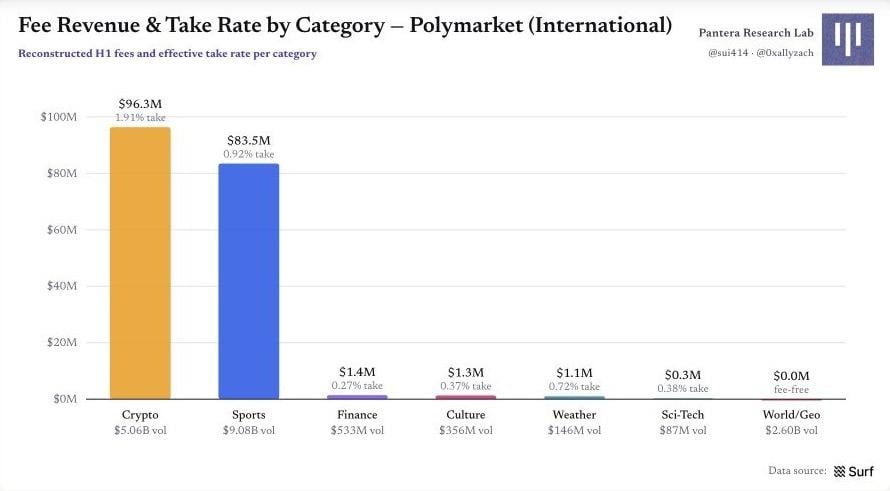
The international market generated about $184 million in gross fees in the first half of the year, but this does not account for net income after deducting maker rebates and incentives. Although the crypto market had only about half the transaction volume of the sports market, it generated $96.3 million in fees, exceeding the sports market's $83.5 million; these two categories together accounted for 98% of total fees. The world/geopolitical category adopted a deliberate zero-fee strategy.
Figure 4|Polymarket International Market: Fee Income and Effective Take Rate by Category
High Turnover Categories are Fee Engines
In July, Kalshi's open interest was about 2.3 times that of the Polymarket international market, yet its transaction volume was about 4.4 times; the corresponding daily turnover ratio was approximately 0.44× compared to 0.23×. Polymarket US has the smallest capital pool, yet runs the fastest with a turnover ratio of about 0.64×. The answer does not lie in the platform name but in what the market directory comprises.
Figure 5|Open Interest and Transaction Volume of Three Markets: Capital Scale Does Not Equal Capital Turnover Speed
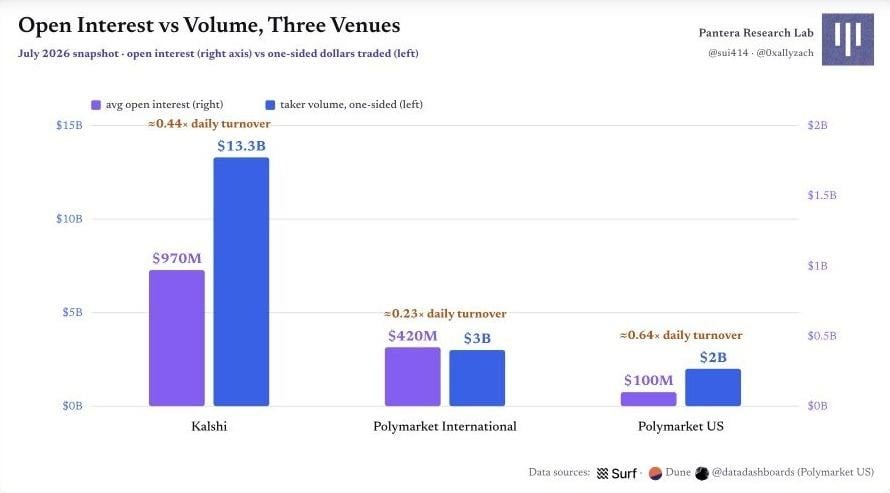
Figure 6|Comparison of Transaction Volume / Open Interest by Category Between Kalshi and Polymarket
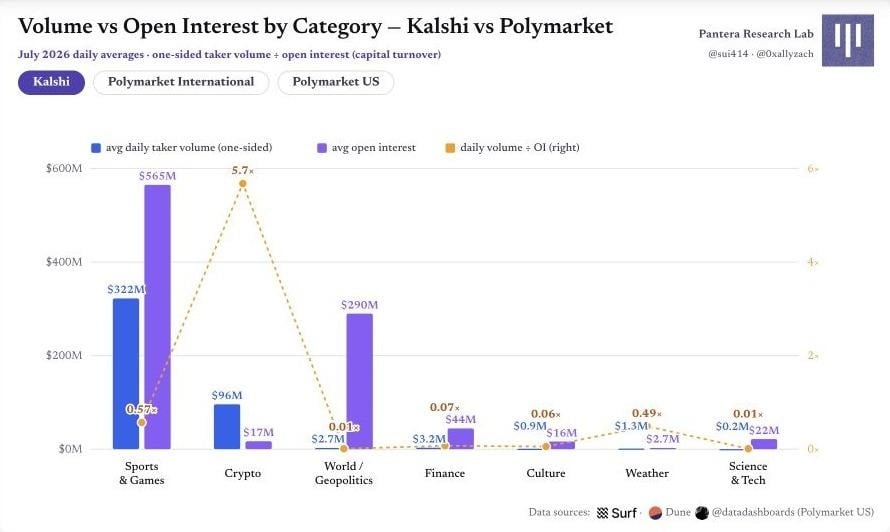
Sports and crypto are the fastest-turning categories, while world/geopolitical is the slowest, with daily turnover only about 0.01-0.03×. Both international markets each have around $200 million to $300 million in capital locked up, yet only generate $2 million to $3 million in daily transactions, hence they have set the category to zero fees. Approximately 88% of the open interest in Polymarket US is concentrated in sports, explaining why it can achieve higher turnover with less capital.
Kalshi's crypto market is a clear outlier: with about $17 million in open interest corresponding to approximately $96 million in daily transactions, its daily turnover approaches 6×, with 98% of market durations not exceeding one hour. Polymarket's crypto turnover appears to be only 0.31× due to threshold-type markets with long maturities holding most of the open interest, while five-minute ups and downs markets account for about 90% of transaction volume but hardly lock up any capital; on average, each such market only locks about $2,800 in collateral.
The same category across different platforms tends to have similar velocities: daily turnover rates for sports are approximately 0.57×, 0.67×, and 0.64× for Kalshi, Polymarket international market, and Polymarket US, respectively. This resembles category attributes rather than platform attributes.
Part Two User Growth of Polymarket International Market
The following user analysis only covers the Polygon CTF / NegRisk contracts of the international market, with a timeframe from January 1, 2026, to June 30, 2026. Polymarket US and Kalshi settle on internal ledgers, with public trading flows anonymized, thus preventing equal depth in wallet profiling.
Maker and Taker: The Two Sides of the Order Book are Not the Same Group
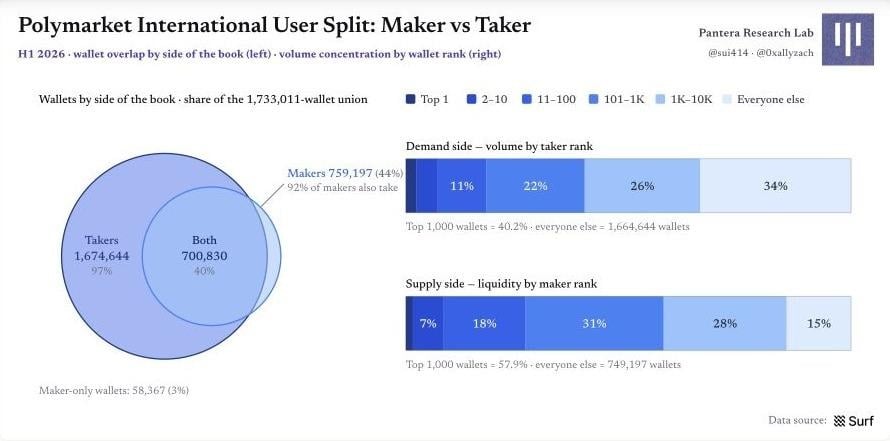
In the first half of the year, there were 1,733,011 wallets trading in the international market. Almost all wallets had actively taken liquidity at least once, but less than half had ever placed a limit order. The maker side is noticeably more professional and smaller; the top thousand makers provided most of the static liquidity. The demand side is equally concentrated: about 6% of highly active wallets completed 80% of taker transaction volume, while one-third of wallets traded five times or less over six months.
Figure 7|Polymarket International Market Wallet Structure: Overlap and Concentration of Maker and Taker
User Growth Accounting: Activity Remains Nearly Flat
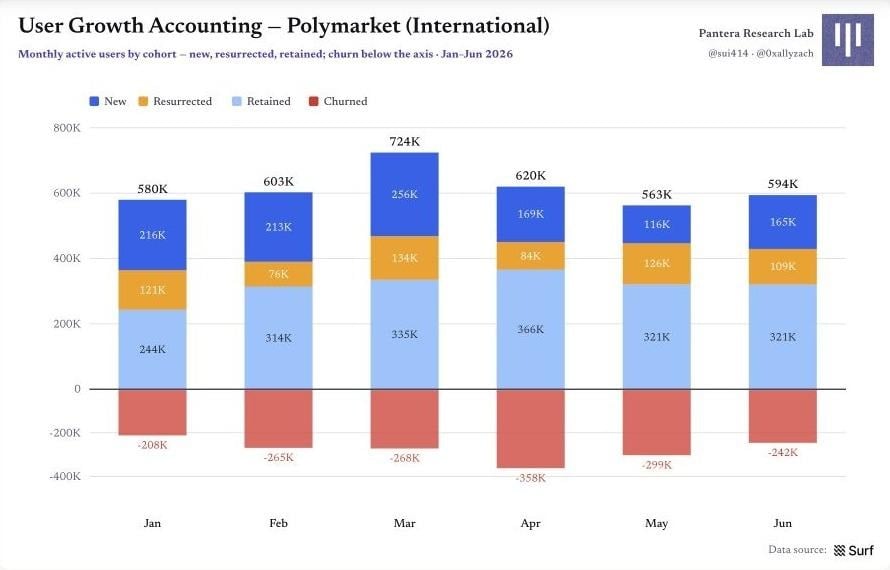
User growth is even less optimistic than transaction volume: monthly active wallets grew from 580,000 in January to 594,000 in June, remaining flat, despite about 1.1 million wallets engaging in their first trade during the same period. About 43%-49% of the previously active wallets each month stop trading, with April seeing a loss of 358,000, meaning the platform must continually replace lost users with new and returning wallets.
There are three important qualifiers here. A wallet does not equal a user; some of the so-called losses may just mean users switched to a new wallet; and churn in this article only refers to wallets stopping trades, not accounts being closed or having no funds remaining.
Figure 8|User Growth Accounting: New Users, Returning Users, Retained Users, and Churn
Where New Users Come From: Not a Single Point of Explosion
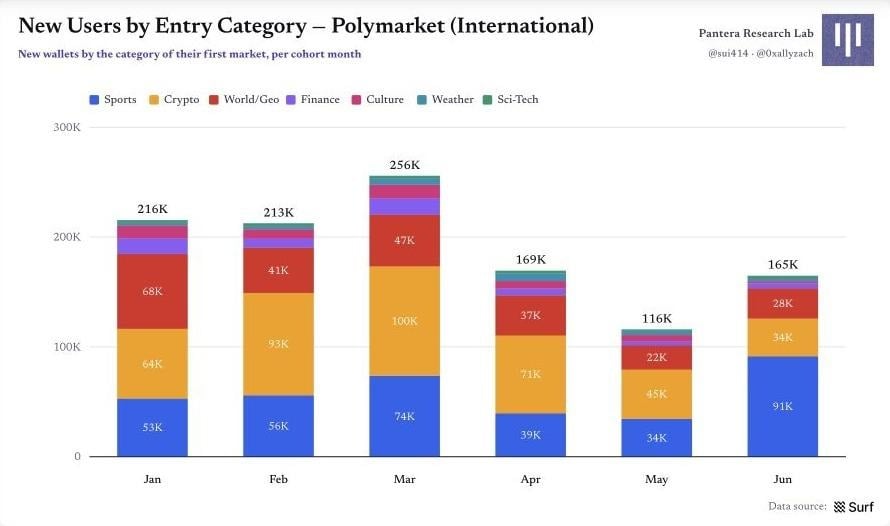
When we attribute each new wallet to the market it first interacted with, we can see the seasonality of the user acquisition machine: the crypto market peaked at about 99,000 new wallets in March, geopolitics peaked at around 68,000 in January, and sports peaked at around 91,000 during the World Cup kickoff in June. Events bring peaks, but no single market carries all the new growth.
Figure 9|New Wallets by First Entered Category
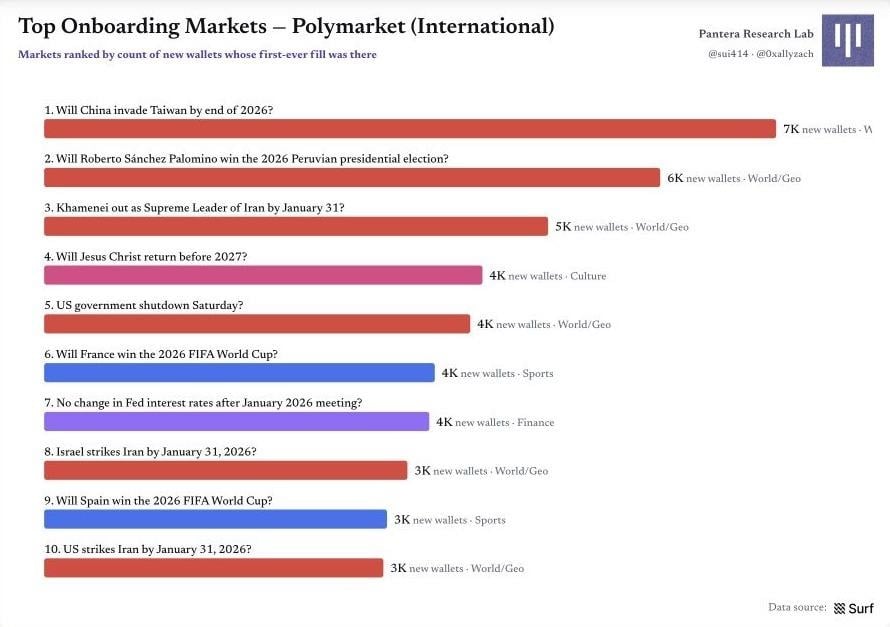
The strongest single traffic market in the first half of the year was "Will China invade Taiwan before the end of 2026?", but it also only brought in about 7,000 new wallets. Among the top ten, there are both geopolitical events as well as the World Cup, interest rates, and cultural events, indicating that effective user acquisition stems from a mix of markets rather than a single hot product.
Figure 10|Top Ten Markets with Most New Wallets in the First Half of the Year
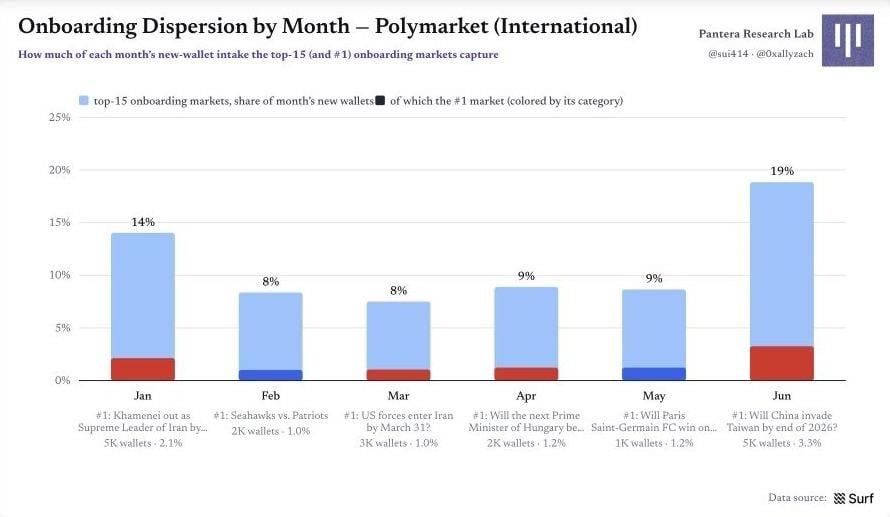
On a monthly basis, the top 15 traffic markets account for only 8%-19% of the new wallets that month, with the top market never exceeding about 3%. The most concentrated were in January and June, corresponding to news from Iran, the Taiwan market, and the World Cup.
Figure 11|Monthly New User Dispersal: Contribution of Top 15 Markets and the Top Market
Retention: Users Stay on the Platform, but Not Necessarily in the Original Category
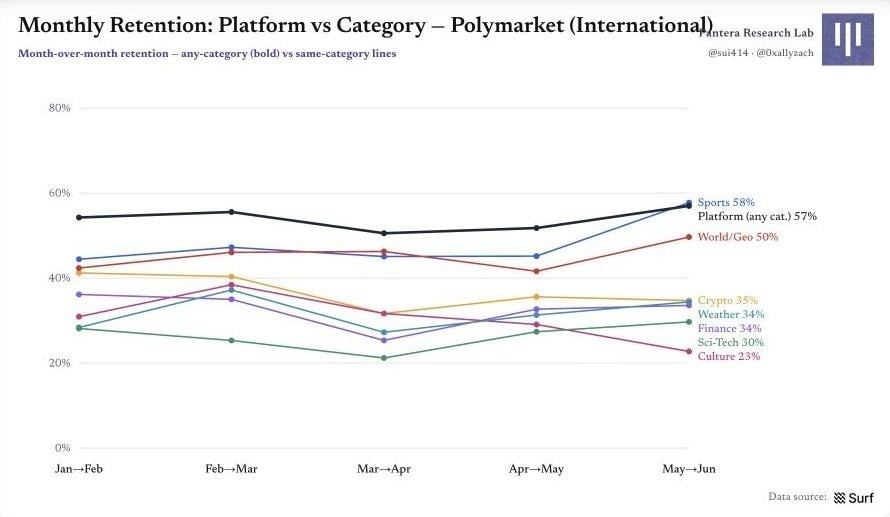
About half of the monthly active wallets come back the following month, with the platform's monthly retention about 51%-57%; however, loyalty to a specific category is significantly weaker. Users may leave the category they initially entered but reappear in another category, suggesting that cross-category recommendations and cross-selling may be at play.
Figure 12|Comparison of Platform Retention and Category Retention
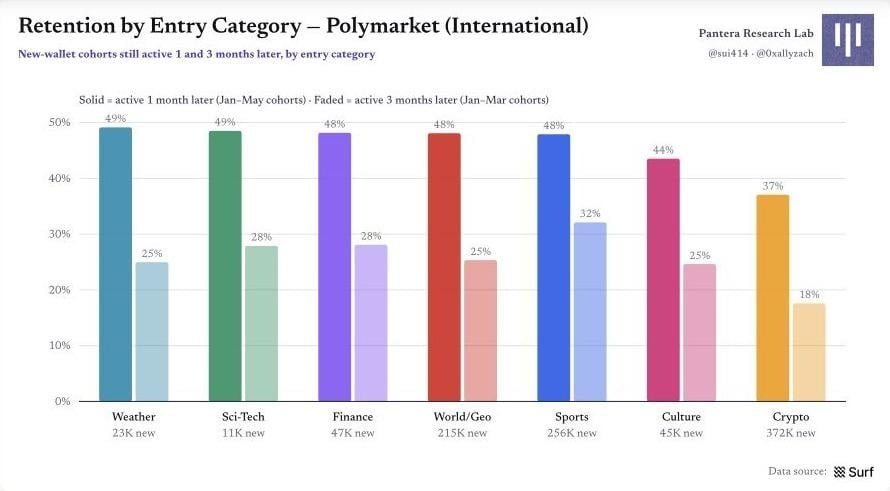
One-month retention rates from different entry categories are highly concentrated at around 44%-49%, and three-month retention is about 25%-32%. The only clear low point is in the crypto entry category, where one-month retention is around 37%, about 30% lower than other categories; one possible explanation and speculation is that automated operations in crypto trading rotate through new wallets more frequently, lowering the apparent retention rate.
Figure 13|Comparison of New Wallet Retention by Entry Category
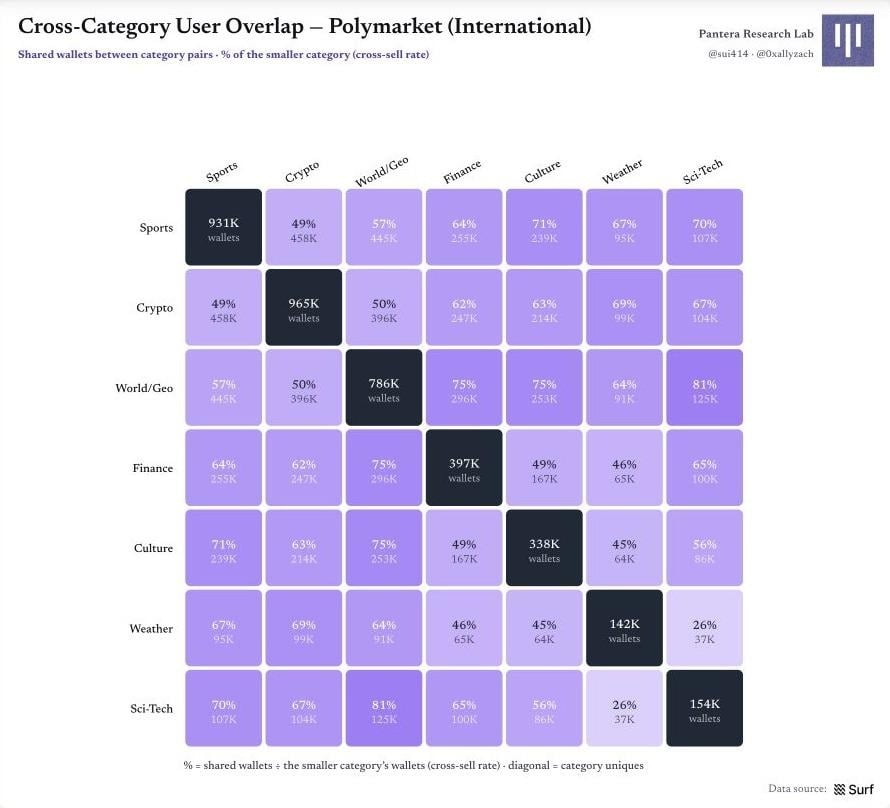
User Market Participation Category Matrix: Geopolitical is the Connecting Layer
The matrix diagonal indicates the number of independent wallets for each category, while the percentage off the diagonal represents the proportion of smaller categories that also trade another category. Sports and crypto, while being the two largest user groups, only overlap by 49%, indicating two audiences with substantial differences. The overlap of world/geopolitical with other categories is generally higher (except for weather), acting as a core product that connects the various interests on the platform.
Figure 14|Cross-category User Overlap and Cross-selling Rates
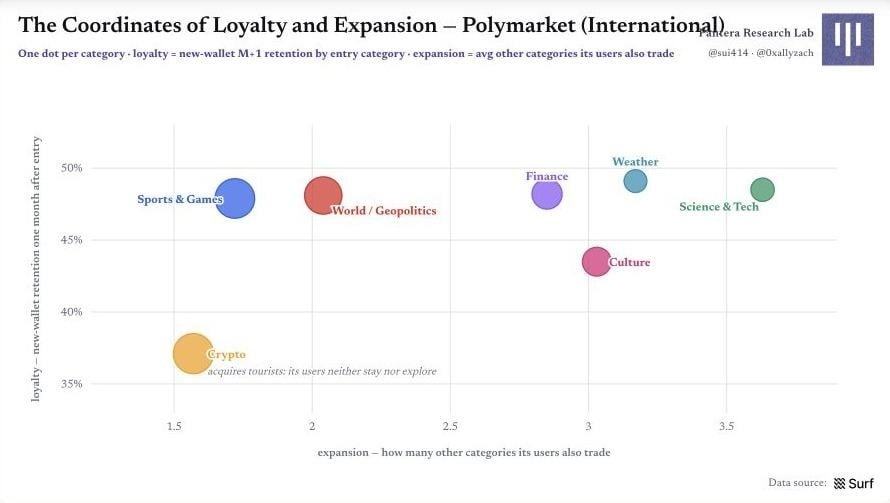
User Category Stickiness × Diffusion Chart: Different Entry Points Bring Different Qualities of Users
Graphing retention against cross-category expansion, the six categories cluster around a loyalty range of 43%-49%, but have differing expansion capabilities: sports behaves like stable users staying in their main area, while science and technology attracts users who explore an average of 3.6 other categories. Crypto is located in the lower left corner: one-month retention is about 37%, and expansion is also the lowest. Five-minute betting brings transaction volume, but not long-term retention or cross-category exploration.
Figure 15|Coordinates of Each Category in "Loyalty × Expansion"
Part Three Market Microstructure: User Profiles, Entry Timing, and Profitability
User Profile Distribution: Market Category Breadth, Frequency Linked to Transaction Size
We depict users from three perspectives: how many categories are covered, the size of single transactions, and transaction frequency. The broader the category coverage, the higher the average transaction volume; wallets that cover all seven categories account for only about 1%, but had an average taker transaction volume of about $59,000 over the first half of the year, seven times that of wallets focused on a single category at $8,300.
The frequency dimension shows a typical 80/20: about 6% of "high-frequency users" contribute 79% of the transaction volume, while wallets that only execute one trade account for about 8% of the user base.
Figure 16|Specialization and Participation: Category Breadth, Wallet Proportion, and Transaction Volume
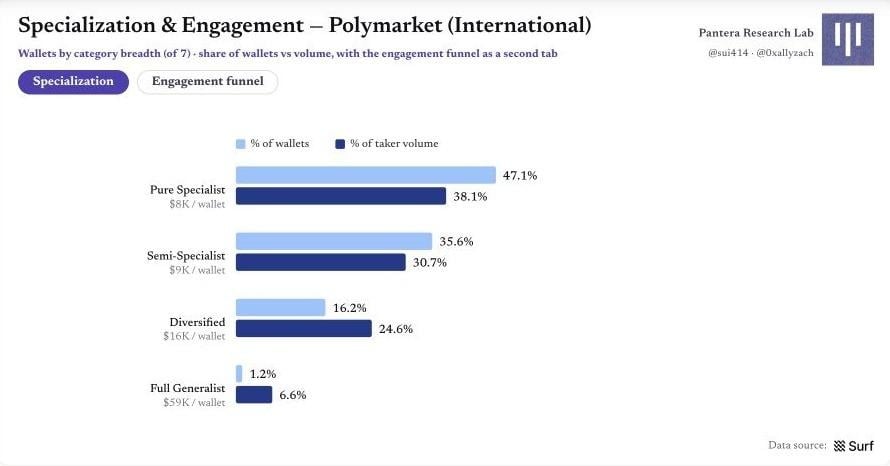
Charts retain original English labels; Chinese descriptions can be found in the text.
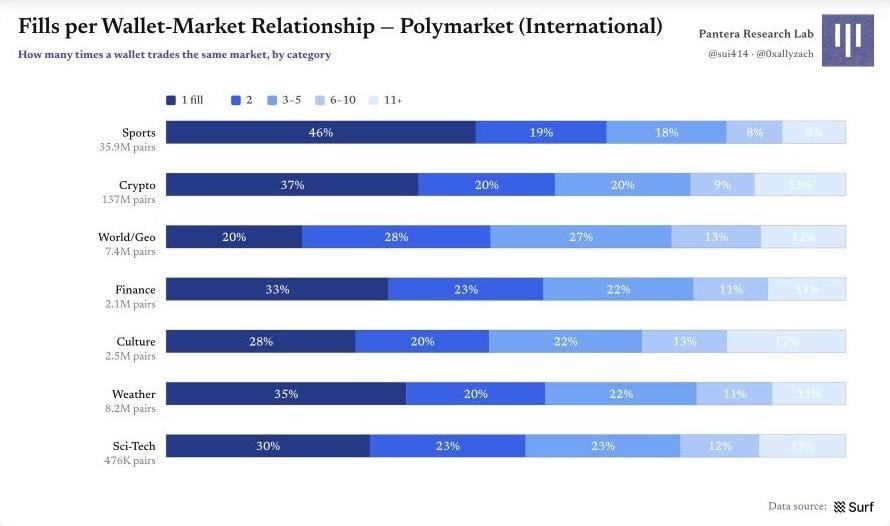
In most categories, the relationship between wallets and individual markets primarily consists of one or two transactions; the highest proportion for sports transactions is 46%. Conversely, for world/geopolitical, only 20% of connections are based on a single transaction, indicating that users return to the same market repeatedly as news progresses.
Figure 17|Transaction Counts per Wallet-Market Relationship
Three Types of Participants: Bots, Professional Users, and Retail Users
We employ behavioral signals such as transaction frequency, consistency of order amounts, breadth of coverage, and average ticket size for heuristic classification. The classification is not a definitive judgment of true identity, as threshold variations can affect distribution; it is more suitable for answering "who trades in what manner" rather than "who exactly is who."
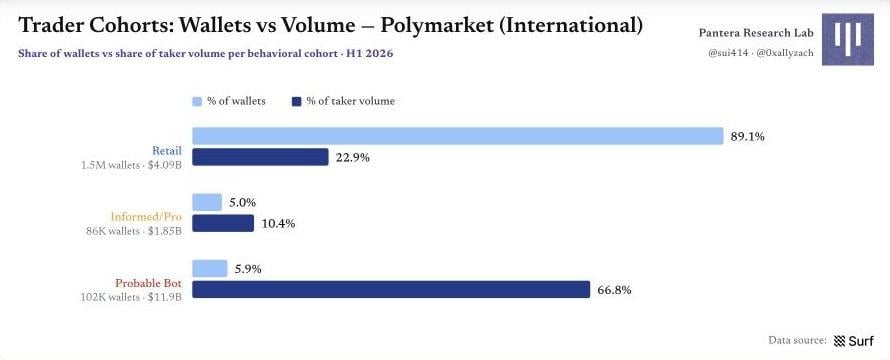
Bot wallets represent about 5.9% of users but account for about two-thirds of transaction volume: approximately 102,000 wallets contributed $11.9 billion in transactions and 89% of transaction events; around 1.54 million retail wallets contributed $4.1 billion. Professional/informed users make up about 5%, contributing 6.6% of taker transaction volume, consistent with their tendency to provide liquidity and less frequently take orders.
Figure 18|Trader Groups: Mismatch Between Wallet Numbers and Transaction Volumes
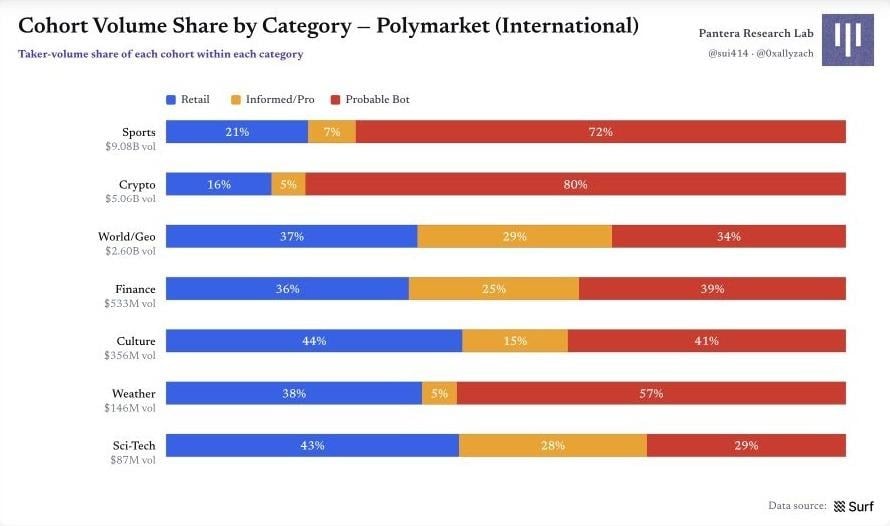
By category, bots dominate the crypto and sports markets, capturing about 80% and 72% of the transaction volume, respectively; conversely, in the areas where humans still significantly affect prices—geopolitical, finance, culture—the shares of the three groups are closer.
Figure 19|Group Transaction Volume Shares by Category
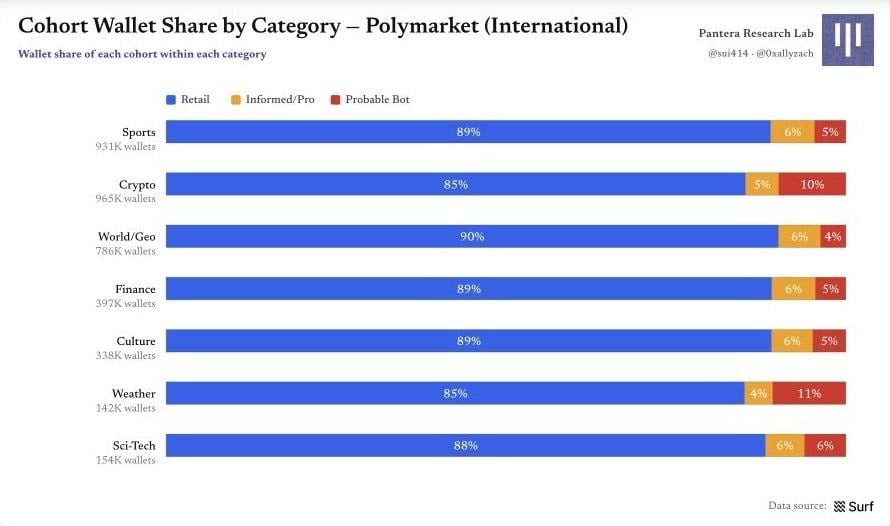
However, the volume advantage arises from a thin layer of bots. By wallet count, each category remains overwhelmingly occupied by retail users; bots account for significantly higher proportions in the crypto and weather markets, with about 5% of the population replaced by automated actions.
Figure 20|Wallet Group Shares by Category
Are Prediction Market Users Sensitive to Fees?
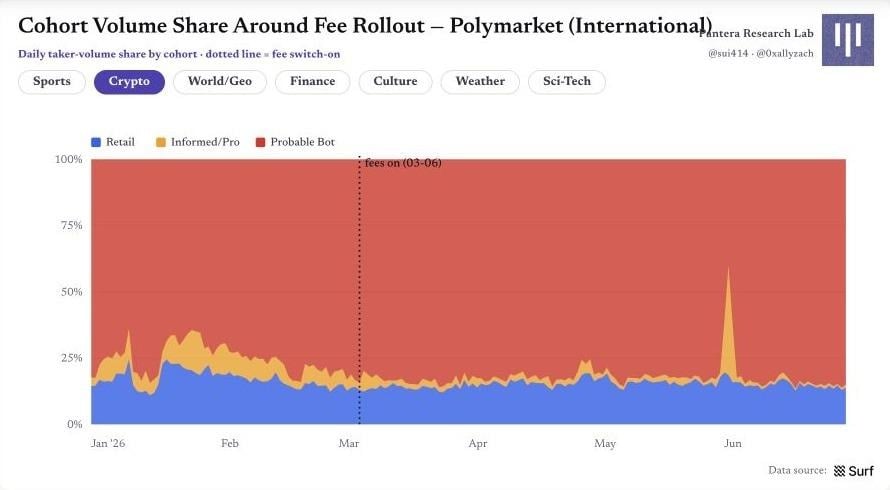
Different categories activate fees at different times, creating a natural experiment; the zero-fee world/geopolitical can serve as a control group. The results show that after fees are implemented, the composition of transaction volume changes significantly, particularly in the crypto, culture, and weather markets: the share of volume from professional/informed users quickly declines, while the shares from retail and bots remain relatively stable, demonstrating stronger insensitivity to fees.
Figure 21|Volume Share of Each Group Before and After Fee Implementation
Charts retain original English labels; Chinese descriptions can be found in the text.
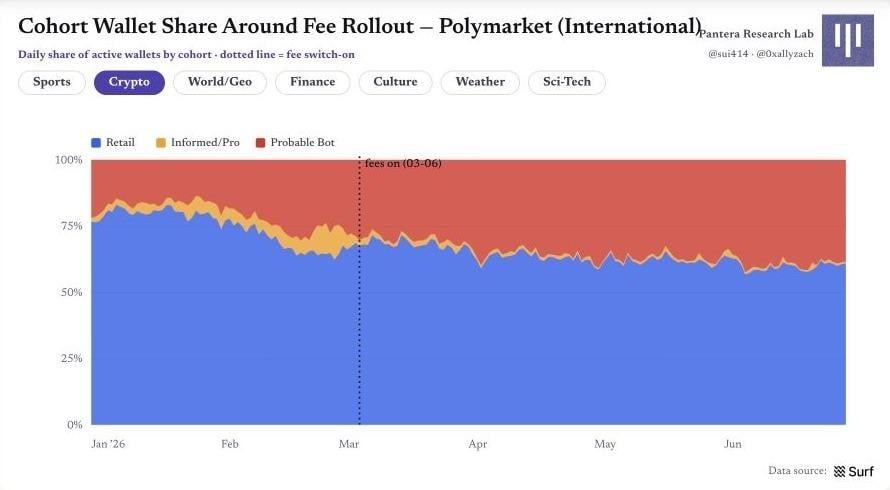
The changes in wallet shares are much smaller than those in volume shares, but the patterns are consistent: the professional/informed wallets in the aforementioned three categories show the most significant losses. Fees change "who is increasing their bets," but do not necessarily immediately change "who is still in the game."
Figure 22|Wallet Shares of Each Group Before and After Fee Implementation
Entry Timing: Most People Arrive Too Late
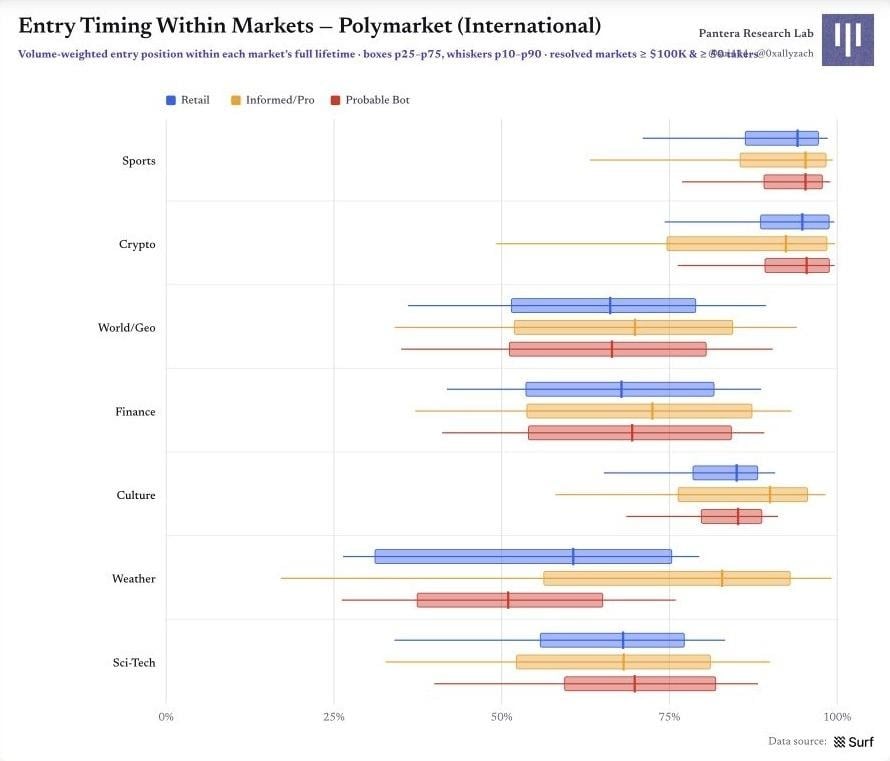
In the lifecycle of a market, late entry is the norm, but the degree of lateness varies across different information games. Sports and crypto exhibit the most delayed competitiveness: the median entry point for each group lands between 92%-95% of the market lifecycle, creating a clear adverse selection pressure for retail users. Culture stands at roughly 85%-90%; weather, conversely, experiences the earliest entries, with retail’s median around 61% and bots about 51%, consistent with model-resulting markets that can be priced earlier. The weather market also presents the latest entry point for professional users, with a median around 83%.
The entry timing analysis only includes markets that have complete lifecycle visibility: markets that settled in the first half of the year and tracked wallets from the first transaction, including positions already opened before 2026.
Figure 23|Weighted Entry Timing of Each Group in the Market Lifecycle
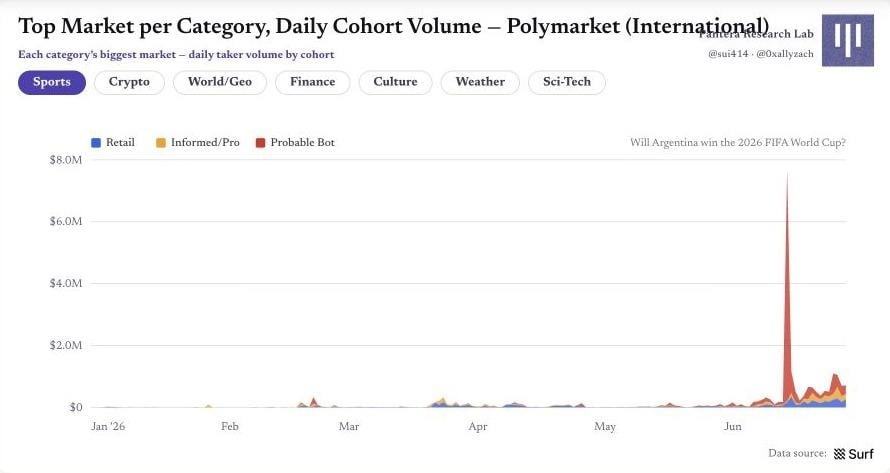
Markets with the largest volume in each category show a more intuitive intraday rhythm: retail user transactions often span the entire market cycle; professional/informed users and bots tend to suddenly increase their volume with incoming information or concentrate their bets near settlement.
Figure 24|Daily Group Transaction Volumes of Top Markets by Category
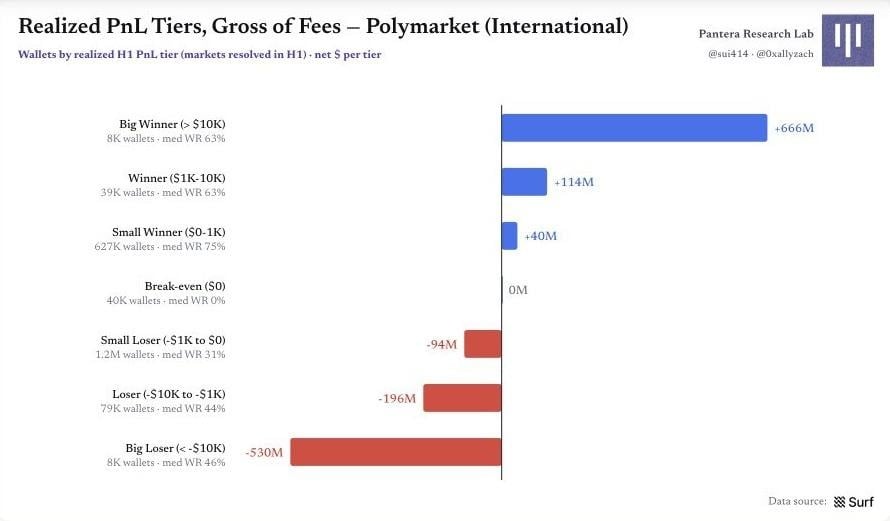
Who is Actually Making Money?
Summing up the cash flows of all positions in markets settled in the first half of the year, the pre-fee ledger approaches zero: among about 1.97 million wallets with settled positions, 34% ended up positive. The big winners totaled about +$666 million, while the big losers totaled about -$530 million, with all groups summing to about zero. This verifies that what is calculated here is the pre-fee gross PnL; after deducting approximately $184 million in fees from the first half of the year, the aggregated result will turn negative.
Figure 25|Realized PnL Layer Before Fees
Charts retain original English labels; Chinese descriptions can be found in the text.
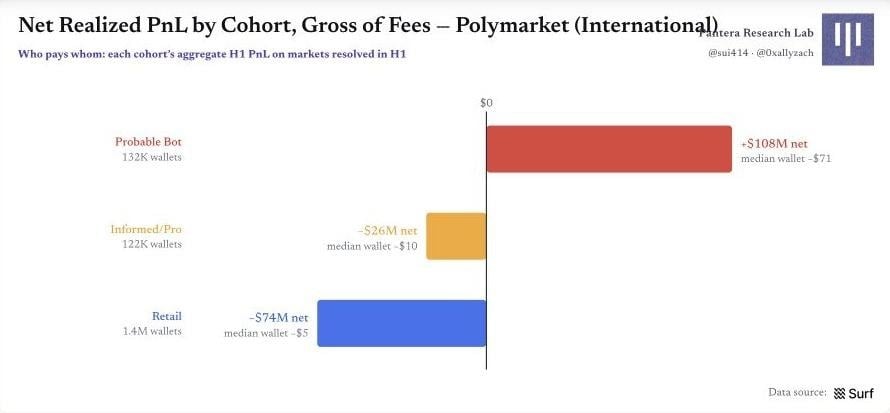
Breaking down by group, the capital flows are very clear: retail and professional users collectively provide the counterparty for the positive earnings of the bot group. Bots are the only group that is overall net profitable, totaling about +$108 million, but only 27% of bot wallets are profitable, with the median bot wallet still in the red. Profits are carried by a few large-scale operations, and sustained profitability is extremely rare.
Professional users have the highest profit ratios, with about 42% of wallets being positive; retail about 35%, and bots about 27%. However, professional users still collectively lost around $26 million. Since various incentives and rebates are not accounted for here, one cannot definitively assert that professional users' final net earnings are negative. The retail group collectively accounted for about -$74 million.
Figure 26|Profit Ratios and Win Rates of Each Group
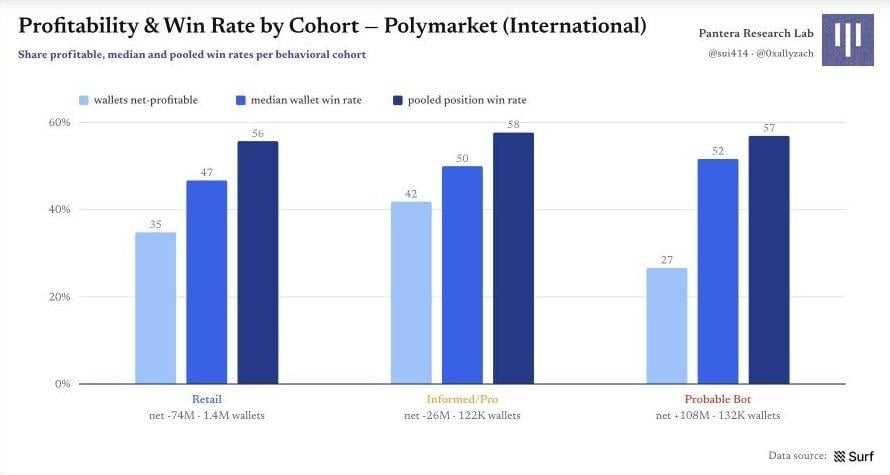
Figure 27|Net Realized PnL of Each Group: Who is Paying and Who is Receiving
Among about 1.75 million wallets, only 146 wallets maintained positive cash flow for six consecutive months; even within wallets that were previously profitable, over 90% of profits were concentrated in a single month. Earnings in prediction markets resemble episodic spikes rather than stable wage flows.
Figure 28|Profit Longevity: Distribution of Months with Continuous Positive Cash Flow
Methodology and Metrics
The data for this article was calculated by Surf AI. PnL only includes markets settled in the first half of 2026 and calculates realized results before fees based on wallets' cash flows in these markets; maker rebates, promotional incentives, and other planned subsidies are not included in gross PnL. Group labels are behavioral heuristic classifications used for comparing trading styles and should not be interpreted as definitive identifications of actual wallet owners' identities.
For access to the same dataset in products or research, please contact ryanli; the user acquisition analysis framework references @0xtaetaehoho's "Listings are the Product." Thanks to the Surf team for providing MCP tools and data support.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。
