Original Author: Zhang Yaqi
Original Source: Wall Street Watch
The AI boom is reshaping global capital flows, with the dollar hovering at a high level, but its fragile support structure makes the outlook for the super dollar full of uncertainties.
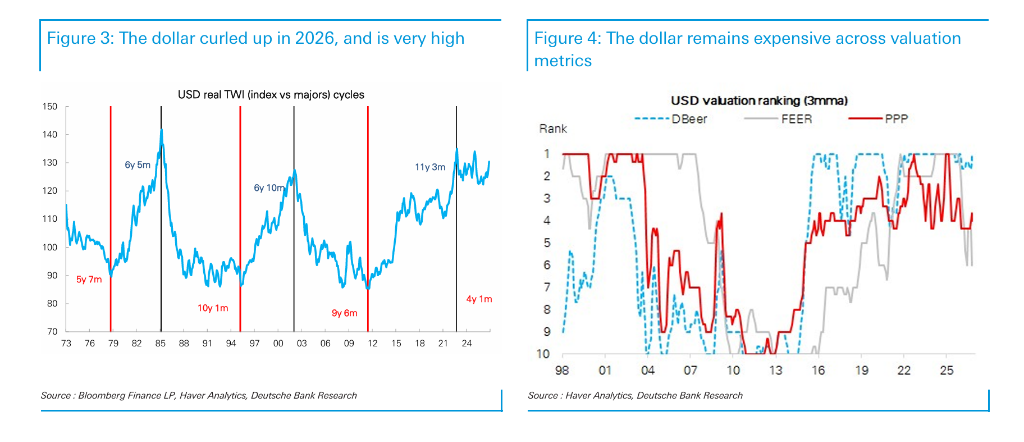
According to news from the Pursuit Trading Desk, Deutsche Bank has significantly raised its USD forecast for 2027 in its latest foreign exchange outlook report, acknowledging that its previous judgment on the weakness of the dollar was wrong. The AI hype has pushed up real interest rates in the US, attracted massive equity inflows, reignited inflation pressures, and prompted the Federal Reserve to shift to a hawkish stance, collectively forming the current "AI Dollar" pattern. The dollar is over 20% above its average from the past four years, according to three fundamental valuation indicators, making it one of the most expensive currencies in the G10.
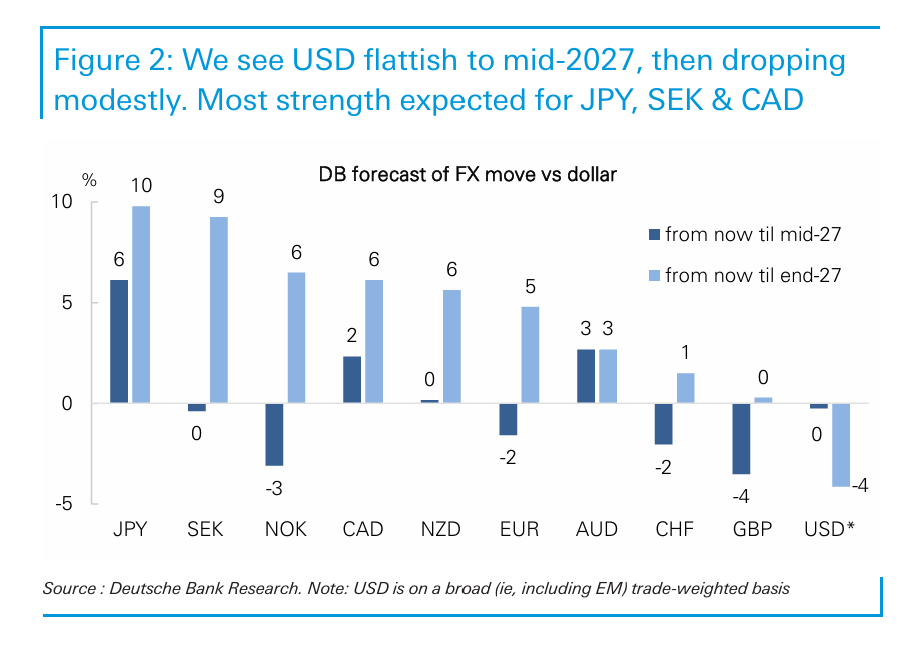
Deutsche Bank predicts that the dollar will maintain its strength in the first half of 2027, with a modest pullback in the second half, but will overall remain at a high level. The report also warns that the dollar's dependence on the AI capital expenditure cycle is deepening. If the market's expectations for AI returns experience a significant downward adjustment, the two pillars supporting the dollar—US real interest rates and equity capital inflows—will simultaneously collapse, leading to substantial downside risks for the dollar.
AI Boom Supports "Dollar Exception" Theory
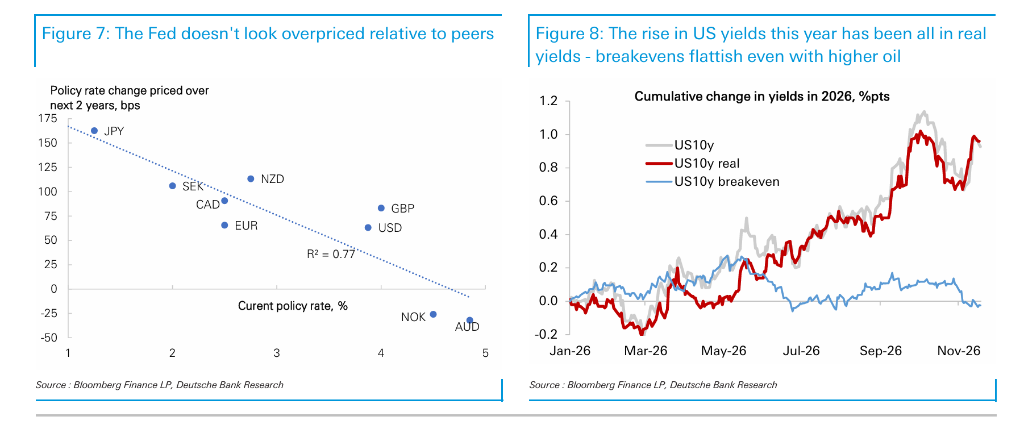
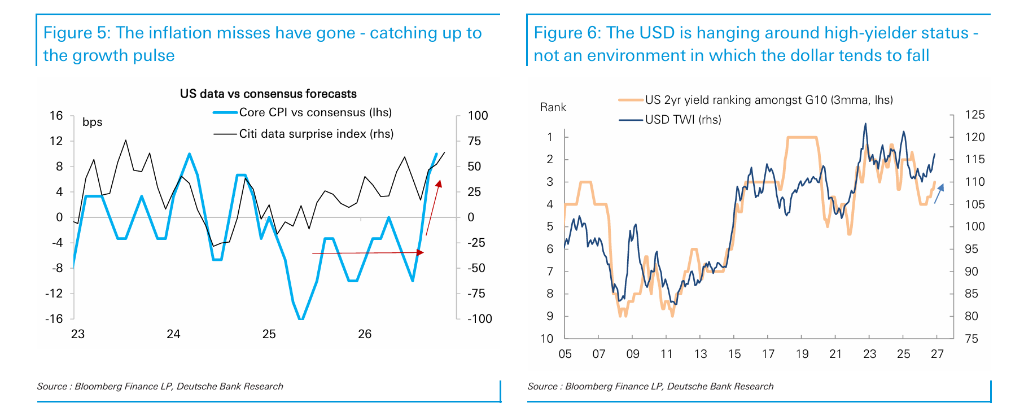
The core driving force behind the dollar's strength originates from within the United States and is likely to continue or even strengthen in the short term. In recent months, US inflation has accelerated again, with the core PCE inflation index expected to exceed 3%, driving the interest rate market to reprice, putting the dollar back among the top three high-yield currencies in the G10—having previously given up this position at the end of 2025. Data from Deutsche Bank shows that historically, the dollar rarely enters a down cycle when offering high yields.
The rise in real yields has also boosted expectations for US neutral interest rates, which have increased by about 50 basis points this year, while the eurozone has remained almost unchanged during the same period. Meanwhile, US GDP growth expectations have returned to the forefront of the G10, and the growth rate of capital expenditures is about twice that of other economies, with the AI-driven capacity expansion cycle laying the groundwork for productivity improvement, providing a positive incentive for the currency market.
Equity Inflows Dominate, Fixed Income Funds Show Signs of Diversion
In terms of capital flows, the US remains the core magnet for global equity investment. Foreign capital inflows into the US stock market have surpassed $1 trillion per year, becoming the main source of financing for the US external deficit, and these funds typically have a low hedging ratio, providing a more direct support effect for the dollar.
However, the flow of fixed income funds is quietly changing. Data from Deutsche Bank indicates that the inflow of US bond funds has slowed, while inflows into bonds in other G10 markets, such as Canada and Japan, have significantly rebounded, shaking the "There Is No Alternative" (TINA) market narrative. Foreign exchange reserve management agencies have also consistently increased their allocation to other smaller currencies over the past year and a half. This trend is worth monitoring—if the diversification value of dollar assets continues to decline, the upward pressure on hedging ratios will increase accordingly.
High Valuations and Dual Deficits Pose Mid-term Hazards
The mid-term outlook for the dollar faces multiple structural pressures. The most concerning factor is the excessive reliance on the AI capital expenditure cycle—capital expenditures related to AI have increased nearly fivefold over the past three years, but this momentum's impact on growth is expected to gradually fade after 2028. The volatility of tech stocks has not yet transmitted to the dollar, but Deutsche Bank believes that once expectations for AI capital expenditures are significantly adjusted downward, the dollar will face substantial impacts.
Meanwhile, the US fiscal deficit remains stable at around 6% of GDP, and the current account deficit is also expanding again, approaching 4% of GDP, close to the worst levels in the G10. From the perspective of trade-weighted real exchange rates, potential trade deficits have shown a long-term downtrend, masked in total data only because the US energy balance has turned positive. Tariff risks are also a concern—recent historical experience shows that tariff threats tend to reduce the value of the dollar rather than increase it.
Asian Currencies: North Asian Capital Reallocation Affects the Dollar's Fate
The movement of North Asian currencies is becoming an increasingly key variable in the dollar's outlook. The combined weight of the yen, won, and new Taiwan dollar in the Federal Reserve's dollar index has surpassed that of the euro, and these economies are accumulating the world's largest trade surpluses, with how they manage these surpluses—reinvesting in the US, seeking alternative routes, or converting domestically—having a decisive impact on the dollar's movement.
Deutsche Bank defines this phenomenon as the "Chip Dollar" era: Chips account for about 50% of the value of every $1 invested in data centers, with chip manufacturing concentrated in Asia, creating trade surpluses that are then reinvested in the US capital markets, forming a self-reinforcing cycle, but also containing systemic vulnerabilities that could collapse if AI valuations are reassessed.
Specifically, Deutsche Bank expects the dollar to move towards the 140 range against the yen. The Bank of Japan's interest rate hikes and the government's drive for localized savings deployment (including intentionally pushing GPIF to shift more assets domestically) may trigger capital repatriation.
Euro: French Political Risk Suppresses but Improvement Expected
The euro will continue to be under pressure in the short term, with the upcoming French presidential election (the first round of voting expected in April 2027) and the subsequent parliamentary elections being the main sources of uncertainty. It is expected to keep EUR/USD at a downward risk below 1.10 in the coming months. Current market pricing by the ECB suggests an interest rate hike of more than 60 basis points, far exceeding Deutsche Bank's expected 25 basis points, further dragging down the euro.
However, Deutsche Bank believes that the French election itself is more likely to become a market-clearing event rather than a risk amplifier. The political risk premium in France has been fully reflected in the market, and there is a clear premium on French government bond spreads relative to fundamentals; furthermore, with the exception of the extreme left, all major political forces in France are aimed at fiscal rectification, making it difficult for the degree of fragmentation under stable government expectations to surpass the status quo. Trends in corporate profits are improving, and both equity and bond fund inflows are expanding, providing a foundation for the euro's mid-term stabilization. Deutsche Bank's assessment for the EUR/USD annual range is approximately 1.07 to 1.15.
Emerging Markets: Carry Trade Space Narrows, Differentiation Increases
After a strong year, the low-hanging fruit in emerging market currencies has dwindled. Deutsche Bank takes a more cautious stance on the foreign exchange markets in CEEMEA and Latin America, mainly due to narrowing real interest differentials with the US, overweight positions, and rising supply and fiscal risks.
Specifically, the Polish zloty, Czech koruna, and Israeli new shekel face significant real interest differential compression pressures; the Turkish lira, Egyptian pound, and South African rand are more sensitive to supply shocks. In Latin America, the Brazilian real still has support due to high real interest rates and strong trade conditions, but fiscal risks are balancing the outlook; the Mexican peso continues to be under pressure due to weak economic growth and a dovish stance from the central bank; currencies in the Andean region are relatively optimistic due to favorable trade conditions, cheap valuations, and potential reform dividends. Border markets remain a bright spot, but Deutsche Bank has tempered its bullish expectations for the Kazakh tenge and Uzbek som.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


