【MSX Research Institute · US Stock RWA Daily Observation】 is a flagship daily report produced by the leading RWA trading platform MSX. Leveraging our strong macro research capabilities, we capture the core pulse of the global traditional US stock market, liquidity changes, and the RWA tokenization market, helping you to strategically position in quality assets.
Today's Observation
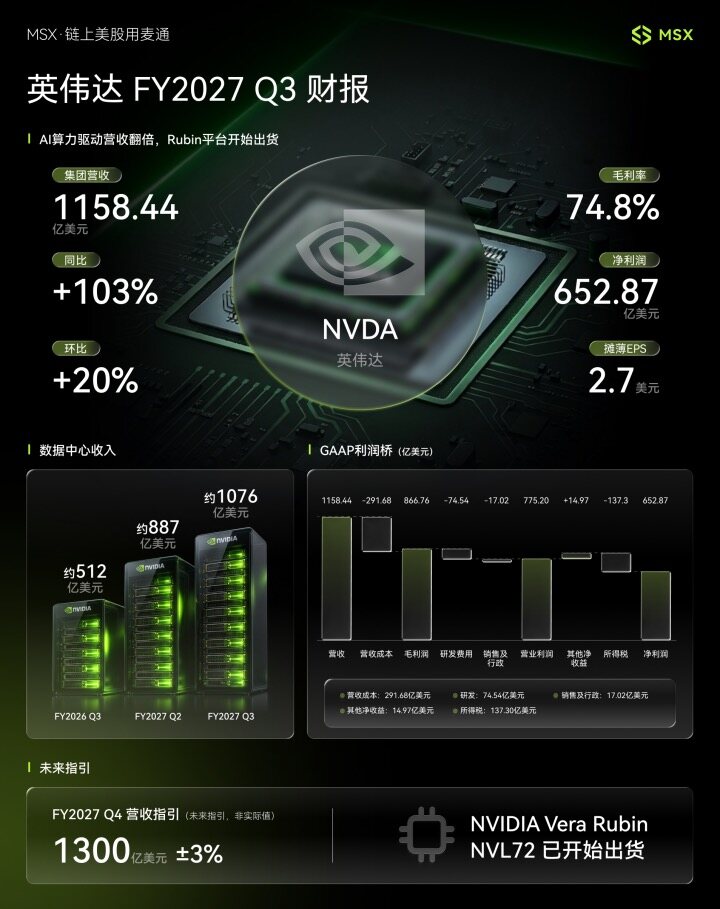
Nvidia's latest financial report provides new performance support for the sustainability of investments in AI infrastructure. On November 17, Eastern Time, Nvidia announced its FY2027 Q3 results: revenue reached approximately $115.8 billion, a year-over-year increase of 103% and a quarter-over-quarter increase of 20%; adjusted earnings per share (EPS) was $2.68. Both metrics exceeded market expectations.
The most noteworthy change this quarter is that the new generation Vera Rubin platform has begun to contribute significant revenue. Management indicated that Rubin generated nearly $20 billion in revenue during its first mass production shipment quarter, making it the fastest product platform in the company's history to ramp up production. Meanwhile, demand for Blackwell remains strong, driving a 110% year-over-year growth in data center business revenue.
The growth momentum has also extended into the next quarter. The company expects FY2027 Q4 revenue to reach $130 billion, with a fluctuation of 3%, and this guidance does not include revenue from data center computing in China. It should be noted that Q4 has an additional week compared to a typical quarter, and this factor should be considered when comparing quarter-over-quarter growth rates.
Data in One Minute
• FY2027 Q3 revenue was approximately $115.8 billion, a year-over-year increase of 103% and a quarter-over-quarter increase of 20%;
• Data center revenue totaled $107.6 billion, a year-over-year increase of 110% and a quarter-over-quarter increase of 21%;
• GAAP net profit was approximately $65.3 billion, a year-over-year increase of 105%;
• GAAP diluted EPS was $2.70, adjusted EPS was $2.68;
• GAAP gross margin was 74.8%, adjusted gross margin was 74.9%;
• Quarterly operating cash flow was $48.253 billion, free cash flow was $43.777 billion;
• This quarter, approximately $28.1 billion was returned to shareholders through buybacks and cash dividends.
• In the data center business, revenue from hyperscale customers was approximately $60.1 billion; AI cloud, industrial, and enterprise customer revenue was approximately $47.5 billion.
• The first mass production shipment quarter of Vera Rubin contributed nearly $20 billion in revenue;
• The FY2027 Q4 revenue guidance median is $130 billion, with a fluctuation of 3%, and this quarter includes an additional week;
• Q4 GAAP and adjusted gross margin guidance are both 71%—72%;
• Management raised the FY2028 revenue year-over-year growth outlook from approximately 70% to about 75%, expecting the gross margin for that fiscal year to be 72%—73%. The above are forward-looking judgments.
MSX View
Understanding Nvidia's financial report can be approached from three aspects: whether the new platform can smoothly ramp up production, whether growth can be converted into cash, and whether customers can continue to bear increasingly larger infrastructure investments.
First, Rubin's revenue contribution indicates that Nvidia is translating its product roadmap into actual delivery. For cloud vendors, procuring new-generation computing power involves cabinets, electricity, cooling, networking, and software adaptations. The ability of the new platform to generate revenue quickly helps shorten the time from equipment procurement to cloud service provision, and it can improve Nvidia's supply chain expansion efficiency. However, the revenue ramp in the first quarter mainly reflects procurement and delivery progress; the utilization rate of the equipment after deployment and the return on investment for customers still need further verification.
From the customer structure perspective, hyperscale customers and AI cloud, industrial, and enterprise customers contributed significant revenue. The expansion of demand sources can increase Nvidia's participation opportunities in various AI application scenarios. However, the financial strength and revenue models of different customers vary, and when analyzing the quality of growth, it is also essential to observe order payment conditions, collection speed, and the customers' own commercialization progress.
Secondly, gross margin will become an important observation metric in the next phase. This quarter's adjusted gross margin reached 74.9%, but the Q4 guidance is 71%—72%. This decline continues the outlook previously provided by the company: management has discussed the rising supply costs in the prior quarter and expects to gradually implement new pricing to bring the FY2028 gross margin back to 72%—73%. Therefore, what needs to be verified going forward is whether cost changes and price adjustments can align as planned.
Lower gross margins and higher profit scales can occur simultaneously. If revenue growth is fast enough, the increasing sales could still drive the gross profit and operating profit expansion. However, as the revenue base increases, every one percentage point change in gross margin will significantly impact profit. When the market evaluates Nvidia's profitability, it needs to consider revenue scale, product mix, and unit costs together.
Cash flow provides another layer of support. Nvidia's free cash flow this quarter was approximately $43.8 billion, higher than the same period last year of about $22.1 billion, while continuing to implement buybacks and dividends. This enables the company to allocate funds among R&D, supply chain, and shareholder returns and reserves space to respond to product iterations and demand fluctuations.
However, Nvidia's participation in industrial expansion is becoming increasingly complex. The company's disclosed supply procurement commitments rose from about $279 billion in the previous quarter to $390 billion, primarily driven by long-term storage procurement. The more comprehensive the supply assurance, the stronger the ability to fulfill orders; correspondingly, the long-term funds and procurement responsibilities also need continuous management.
Customer financing is also worth paying attention to. Management stated that future support for new cloud service providers will be more cautious and will selectively assess investments, commitments, and guarantees. From a business logic perspective, financing support can help customers build data centers faster, but a long-term healthy industrial cycle still requires end users' payment demands to gradually cover the cloud vendors' operational and financing costs. Therefore, after the growth in chip shipments, cloud service revenue, computing power utilization rates, and customer cash flow will become more critical cross-validation metrics.
This financial report is also at a unique transitional point of management handover. Colette Kress is currently serving as interim CEO, and the company is looking for a permanent successor. As of October 25 of this quarter, evaluating execution after the handover will require more observation of product deliveries, team stability, and capital allocation in the next few quarters. The extent to which existing technology platforms and customer ecosystems can sustain momentum will gradually be reflected through these operational results.
For the AI industry chain, Nvidia's growth supports demand for advanced manufacturing, storage, networking, and data center equipment, but the profits obtained by each link still depend on their own supply-demand relationships. Expanding procurement volumes can increase revenue opportunities, while rising costs, competition, and capacity inputs also affect ultimate returns. The strong industrial demand and the profitability improvement of each company still need to be verified item by item.
Next, the most worth tracking is whether Rubin can continue to expand deliveries, whether gross margins can stabilize along the management path, and whether revenue growth can continue to drive cash flow. Nvidia has already demonstrated the ability for new platforms to ramp up and generate high cash flow; as the business scales further, delivery efficiency, capital discipline, and customer returns will together determine how long this growth can continue.
About MSX:
MSX is a leading RWA trading platform dedicated to providing secure, efficient, and transparent access to global financial markets. As one of the earliest on-chain US stock trading platforms in the world, MSX always stays at the forefront of the industry, leading market transformation through continuous innovation.
The platform deeply integrates blockchain technology with compliance frameworks, providing a comprehensive trading of nearly 400 types of tokenized stocks and Pre-IPO assets, including both spot and derivatives trading, perfectly bridging the gap between traditional finance and the digital asset industry.
With the core mission of “allowing premium assets to circulate freely,” MSX has currently built a diversified digital financial service system covering US stock spot and perpetual contracts, coin-to-coin trading, Pre-IPO, and MSX Research Institute, aiming to provide global investors with all-time high-performance gateways to quality asset participation.
Official website: https://msx.com/
Chinese TG: https://t.me/MSXOfficial
Global TG: https://t.me/MSXGlobal
Risk Warning: The macroeconomic and US stock market fluctuations are severe. The content of this article is for the academic and research observation reference of the MSX Research Institute only and does not constitute any investment advice.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


