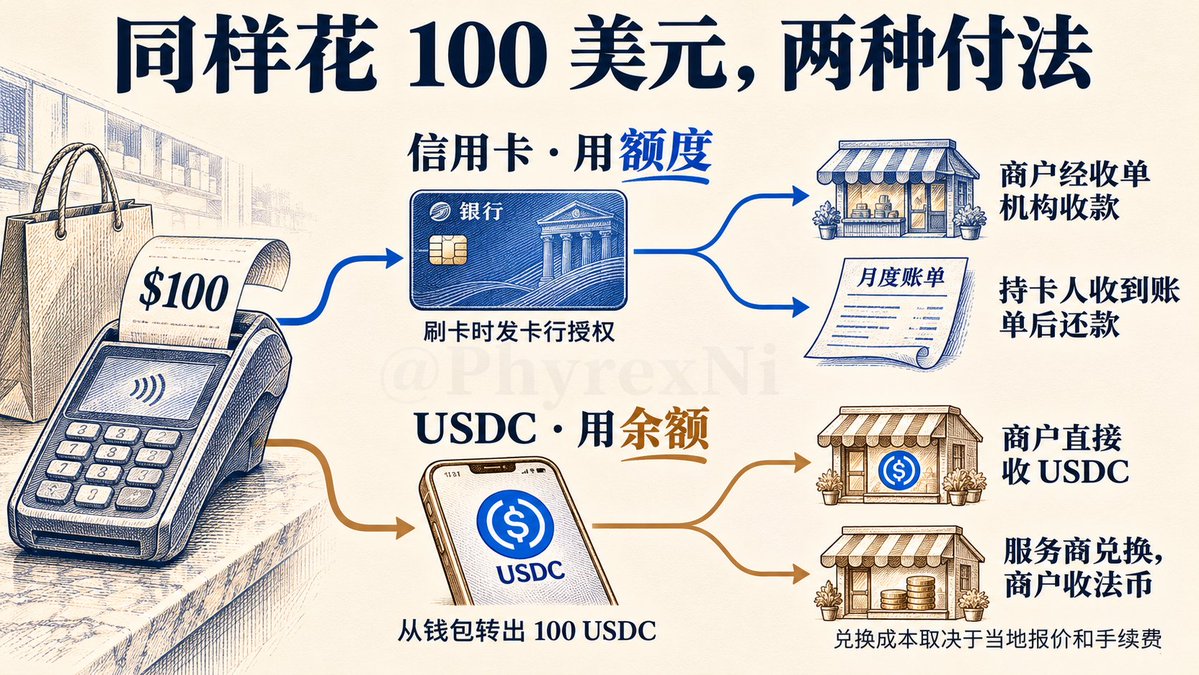
I am not optimistic about $CRCL, mainly because USDC wants to take away daily consumption from credit cards, and this path is very narrow. Many friends are optimistic about USDC payments because USDC itself is the largest compliant stablecoin by volume, but for someone used to using a credit card, the difference between spending $100 today and paying it back later when the bill arrives is very significant.
The reserves behind USDC include cash in USD, short-term US government bonds, and repurchased treasury bonds, which support it to exchange back to USD at a 1:1 ratio. In actual payments, if merchants ultimately need to receive USD or the local fiat currency, they must rely on payment service providers to complete the conversion and withdrawal; bank accounts, local liquidity, and compliance checks must still have someone in charge.
These steps can be imperceptible to holders, but being imperceptible does not mean that costs and barriers do not exist.
I agree with 90% of what Andy said, but there are slight differences on two points. Actually, from the perspective of reserve composition, the assets of USDC are simpler; cash, short-term US bonds, and repurchases are also clearer in disclosure, which are attractive to enterprises that value capital safety, USD redemption, and compliance. In comparison, USDT's reserves also involve assets like gold, Bitcoin, and guaranteed loans, which add more factors that can affect reserve value and liquidity.
Therefore, for gray or black markets, or even all payments, the risk of USDC's blowout is lower than that of USDT, and the acceptance expectations during a run on the bank are higher than that of USDT.
The main reason the gray market does not use USDC is that it is too strict, which means that it is not as convenient for redemption as USDT. If I were with Circle, the first step would be to develop redemption in Southeast Asia, Latin America, and Africa, as these regions have specialized redemption agents. This way, they can capture the market from USDT.
Circle has actually been moving towards these regions; in September, it announced the acquisition of Tazapay in Singapore, and in October, it stated that it would enter about 40 emerging markets. However, they are following the B2B route with licensed banks and payment companies, and do not engage with street-level redemption vendors. This business volume is actually larger than B2B, so USDT remains the mainstream here.
Secondly, the reason USDC finds it hard to take away credit card consumption is that credit cards have integrated payment and credit. Especially in the United States, users enjoy the convenience of using a card, along with the ability to spend in advance, benefit from interest-free periods, earn rewards, and the familiar dispute resolution mechanisms. USDC redeeming at face value does not meet these demands.
For consumers already accustomed to credit cards, exchanging the money in their accounts for USDC before spending requires significant benefits.
If the process of exchange and use is more cumbersome, and there are no clear advantages, users lack the motivation to switch. Therefore, if Circle wants to directly capture this segment of the market from the consumer side, it needs to integrate credit and consumer services through partnerships, and then attract users with lower costs or subsidies. These all require investment, making it difficult to easily achieve scale in the short term.
For AI Agent payments, however, USDC has already become the de facto standard; over 99% of the transaction volume on x402 is USDC. The problem is that the volume is too small; according to Allium's statistics, there were a total of 68.3 million Agent payments in the third quarter, totaling only $3.7 million, averaging around 5 cents per transaction, which can nearly be ignored in a quarterly total transaction volume of $13.9 trillion on-chain.
Thus, essentially, USDC is just an on-chain USD, merely a currency, and for now, it does not represent a payment channel that can replace traditional credit systems. The more USDC aligns with traditional systems, the quicker I believe it will decline.
A @Gate, trading more markets
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


