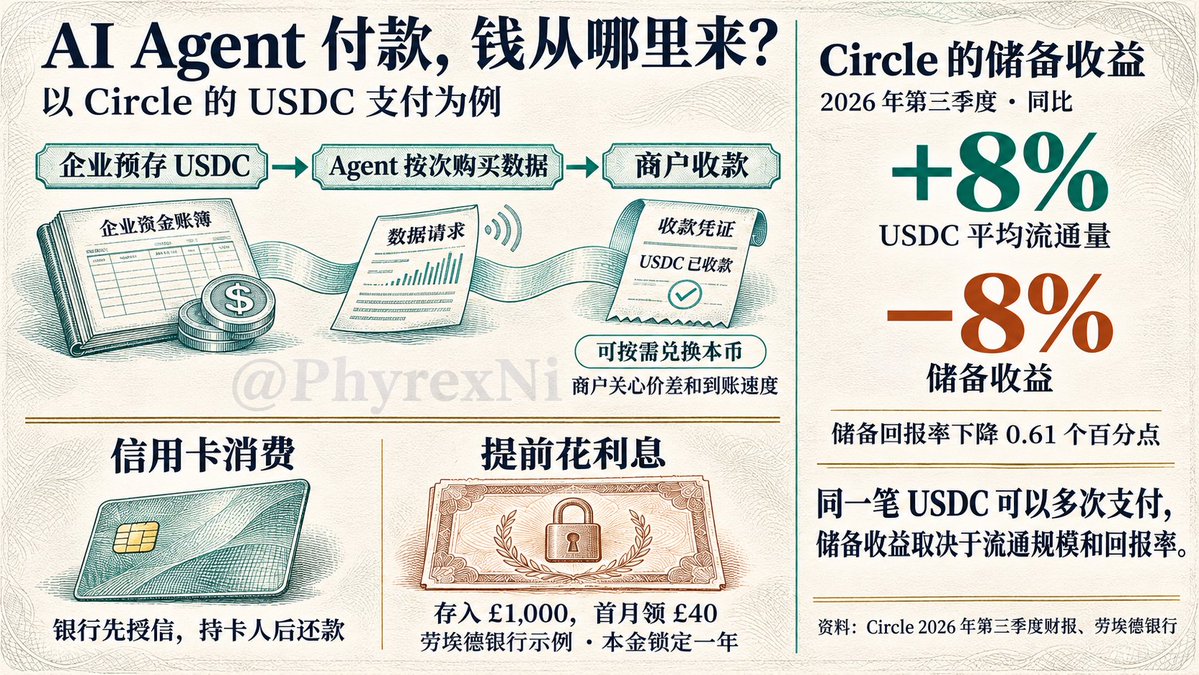
Seeing many friends discussing, before some friends also told me that $CRCL does not need to be made into a credit card, just focus on the payment of AI Agents. From my understanding, this idea still does not break out of the inherent cognition. Even if the focus of AI Agent payment is also to have cash, most people in Europe and the United States are now more accustomed to advance payment methods, which is also the key point I mentioned earlier.
No matter what payment it is, you must first have money. The credit system is about borrowing money first and then paying it back; the most important thing here is "credit." Why can banks lend you money? It is because you have a sufficient foundation of trust in the current world.
However, cryptocurrency itself is decentralized and heavily focused on privacy. So, if you want to keep your identity in the cryptocurrency field unlinked to the real world and credit, for example, if you see that I have 1 million dollars worth of Tokens in my wallet, how much would you dare to lend me?
Moreover, the credit system in Europe and the United States is already very developed, making it very difficult for Circle to establish a new set. It can only join the previous credit system, so either they attract users with lower interest rates or invest more capital to create their own credit system.
The widespread application of stablecoins is definitely not in countries or cities where currencies are mature and currency regulation is relatively relaxed like in Europe and the United States. It must be in countries or cities with strict currency regulation and local currencies that are relatively less stable than the dollar, but these places are basically occupied by USDT, and the reason is the huge acceptance system. Therefore, if USDC wants to share in the pie of USDT, the most important thing is to establish a good acceptance dealer model.
A country where the local currency can be freely exchanged for stablecoins is not the best usage scenario for stablecoins. Just think about it.
For Circle, I am not blindly pessimistic. I have been saying since before the listing that if Circle does not establish its own new profit system, then growth may be very limited. At first, investors were still dreaming that stablecoins could replace credit card payments, but after using them, they realized that stablecoin payments still cannot challenge the credit system.
Even with the logic of "PayFi," banks can actually do it too, it’s just whether they are willing. It is equivalent to using a part of your deposits to buy short-term US treasury bonds, letting you consume in advance without spending principal, which is not difficult.
PS: Circle's Q3 2026 financial report shows that USDC's average circulation has increased by 8% year-on-year, but the reserve return rate has decreased by 0.61%, and the reserve income has instead decreased by 8% year-on-year, to 658 million dollars.
PS2: Lloyds Bank in the UK deposits 1,000 pounds, receives 40 pounds in interest in the first month, which can be spent directly, and retrieves 1,000 pounds after a year. The cost is the principal is locked for a year.
A @Gate, trading more markets
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


