Original | Odaily Planet Daily (@OdailyChina)
Author|Azuma (@azuma_eth)
Half a month ago, Elon Musk and Silicon Valley venture capital giant Chamath Palihapitiya harmonized on X, issuing a "death sentence" to over 200 emerging computing cloud firms (Neocloud) — prophesying that a vast number of graphics cards would become “stranded compute” on abandoned construction sites, and disclosing that “the debt market is completely closed,” asserting that a large wave of “death and mergers” is impending in the new cloud sector.
- Odaily Note: For details, refer to “Doomsaying New Cloud Firms, Musk's Grand Strategy.”
As Musk launched a fierce attack, the AI new cloud leader CoreWeave (NASDAQ: CRWV), positioned in the eye of the storm, also experienced a brutal "double kill" of stocks and bonds — its stock price plummeted over 40% in the past month, while the yield on its 9.75% bonds maturing in 2031 surged to 16.7%, a junk bond crisis level, and the five-year credit default swap (CDS) spread once exceeded 1200 basis points.
Wall Street is holding its breath, is the high-leverage flywheel of new cloud firms "buying cards with borrowed money" really going to stop spinning?
On November 10, after the market closed in Eastern Time (in the early hours of November 11 Beijing time), CoreWeave released its third quarter financial report for 2026, regarded as a "life or death test" for the entire new cloud sector. Following the release, the market gave a dramatically positive reaction — CoreWeave's after-hours stock price surged 7.9%, temporarily reported at $52.58.
Facing the attack from short sellers, what kind of report did CoreWeave deliver? How is it attempting to alleviate current debt pressures?
Directly Countering the "Compute Dust Accumulation Theory"
Prior to the financial report release, one of the core narratives from short sellers was — with infrastructure delays and careful spending from large manufacturers, the exorbitantly purchased GPUs would gather dust in warehouses or become low-margin menial jobs, but CoreWeave's third quarter report directly used a set of violent growth data to respond to the doubts of “demand slowdown.”
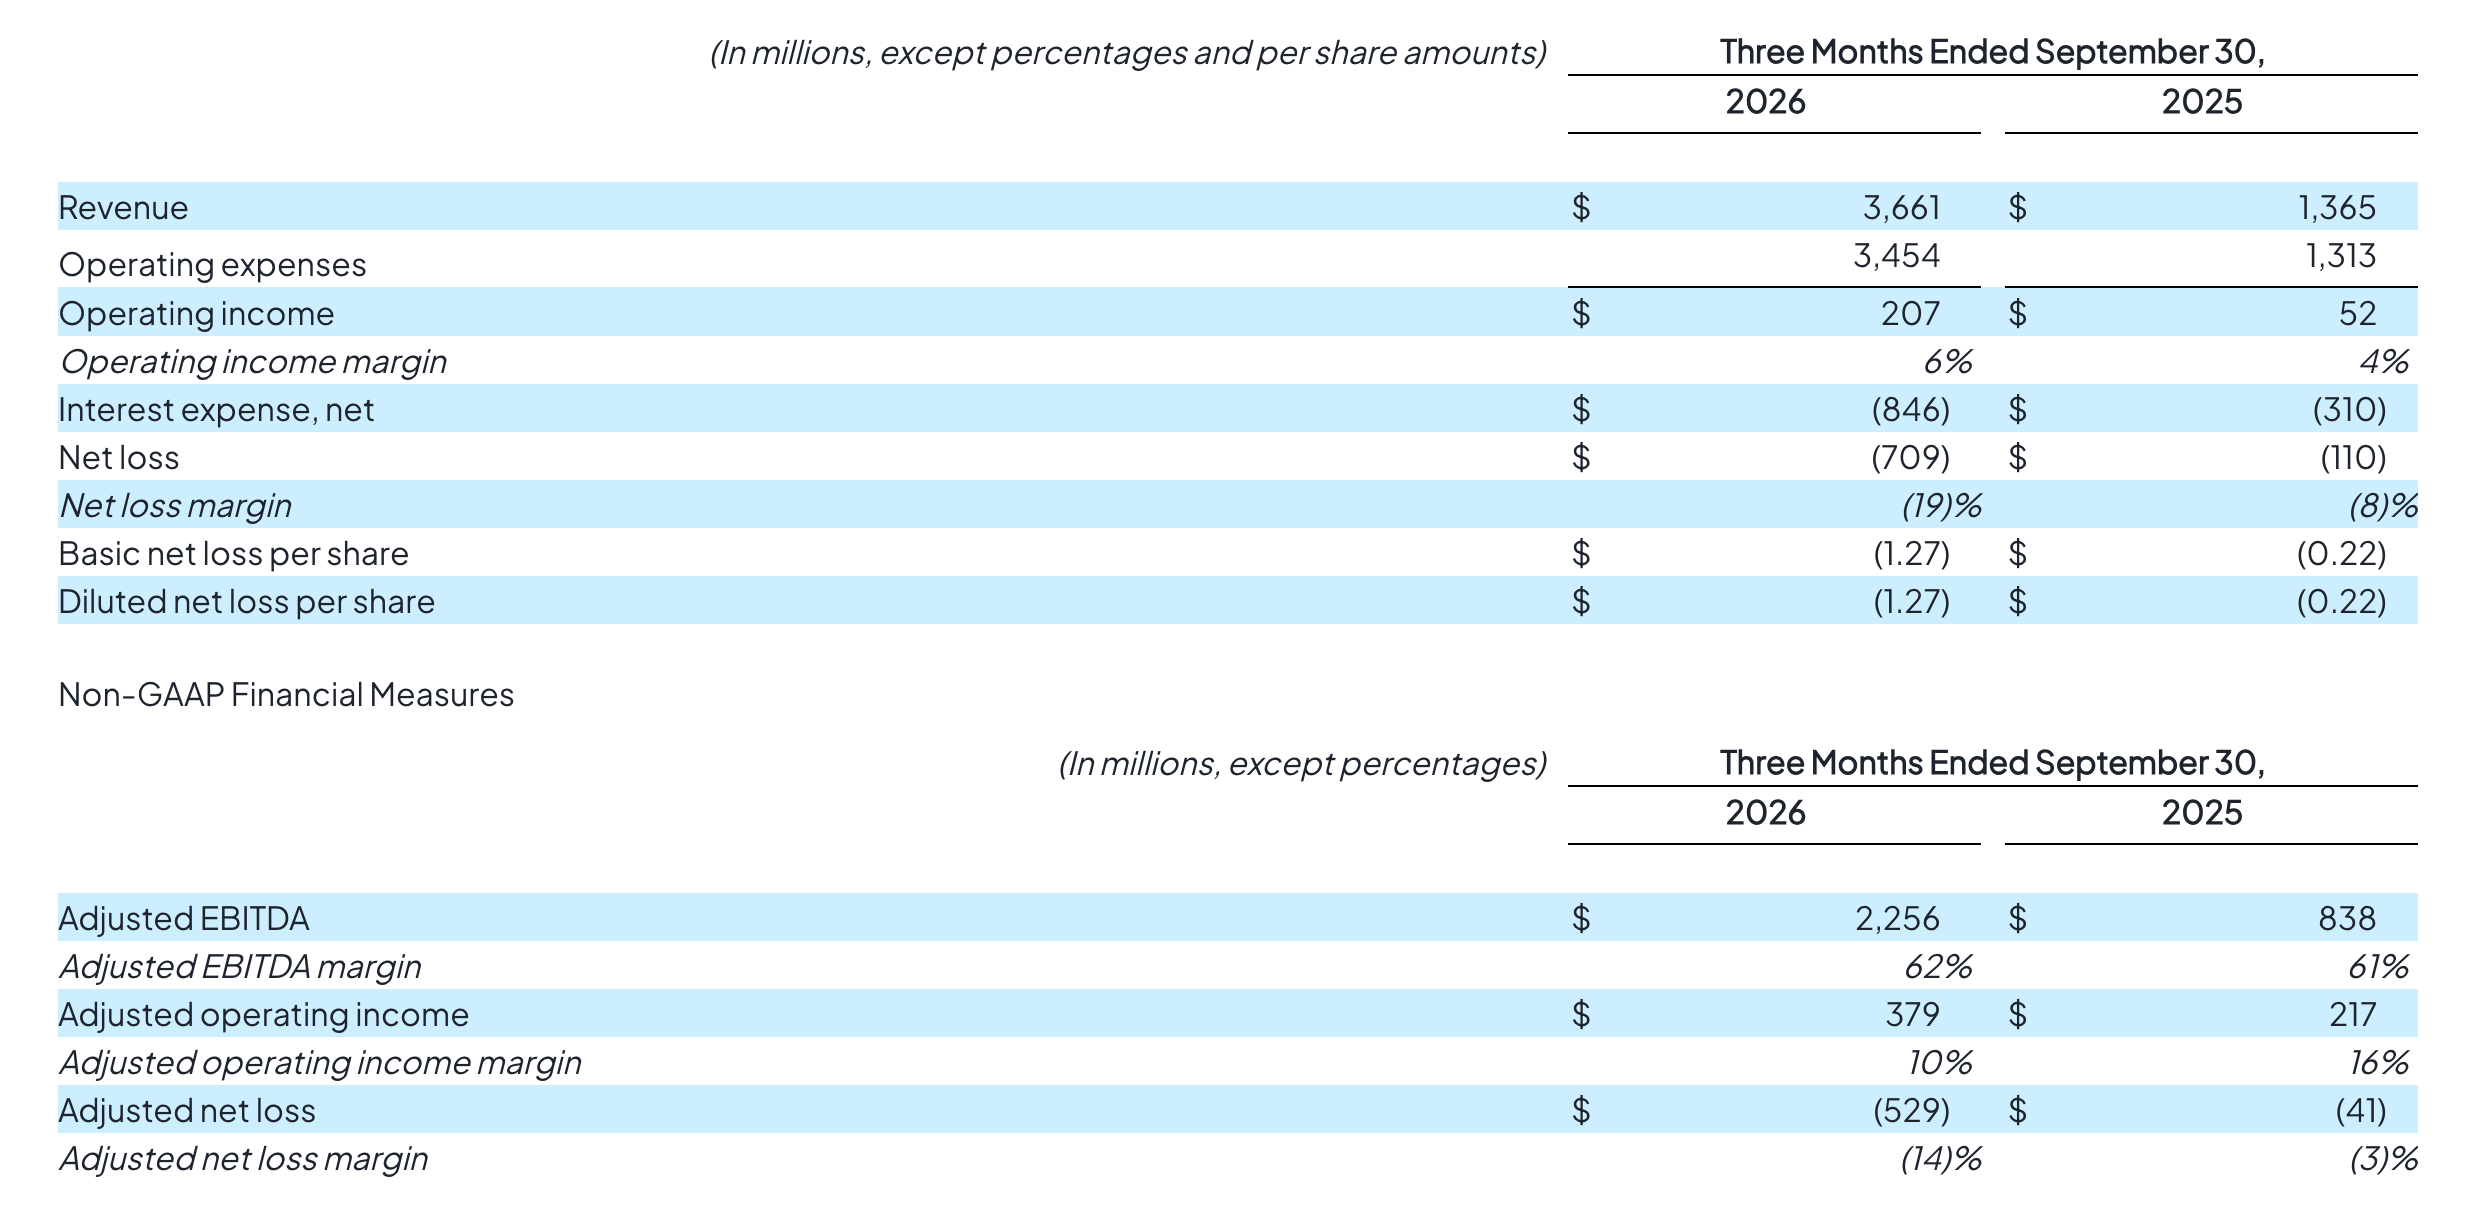
In the third quarter, CoreWeave beat market expectations in both revenue and profit margin — total revenue reached $3.661 billion, year-on-year surging 168%, and quarter-on-quarter increasing 42%, with quarterly net revenue surpassing $1 billion for the first time, exceeding Wall Street's consensus expectation of $3.55 billion to $3.56 billion, and also exceeding the upper limit of the company’s own guidance ($3.6 billion); adjusted EBITDA reached $2.256 billion, with a profit margin of 62%, higher than the market expectation of 57.6%; adjusted operating profit reached $379 million, far surpassing the previous guidance of $200 million to $260 million; and the adjusted operating profit margin jumped from 1% in Q1 and 5% in Q2 to 10%, achieving the double-digit profit margin target one quarter ahead of schedule.
In terms of backlog, as of September 30, CoreWeave's revenue backlog from unfulfilled contracts reached a record-breaking $132.5 billion, an increase of over $28 billion from the $104.2 billion at the end of Q2, and a year-on-year increase of 138%. About 36% of this backlog is expected to convert into actual revenue within the next 24 months.
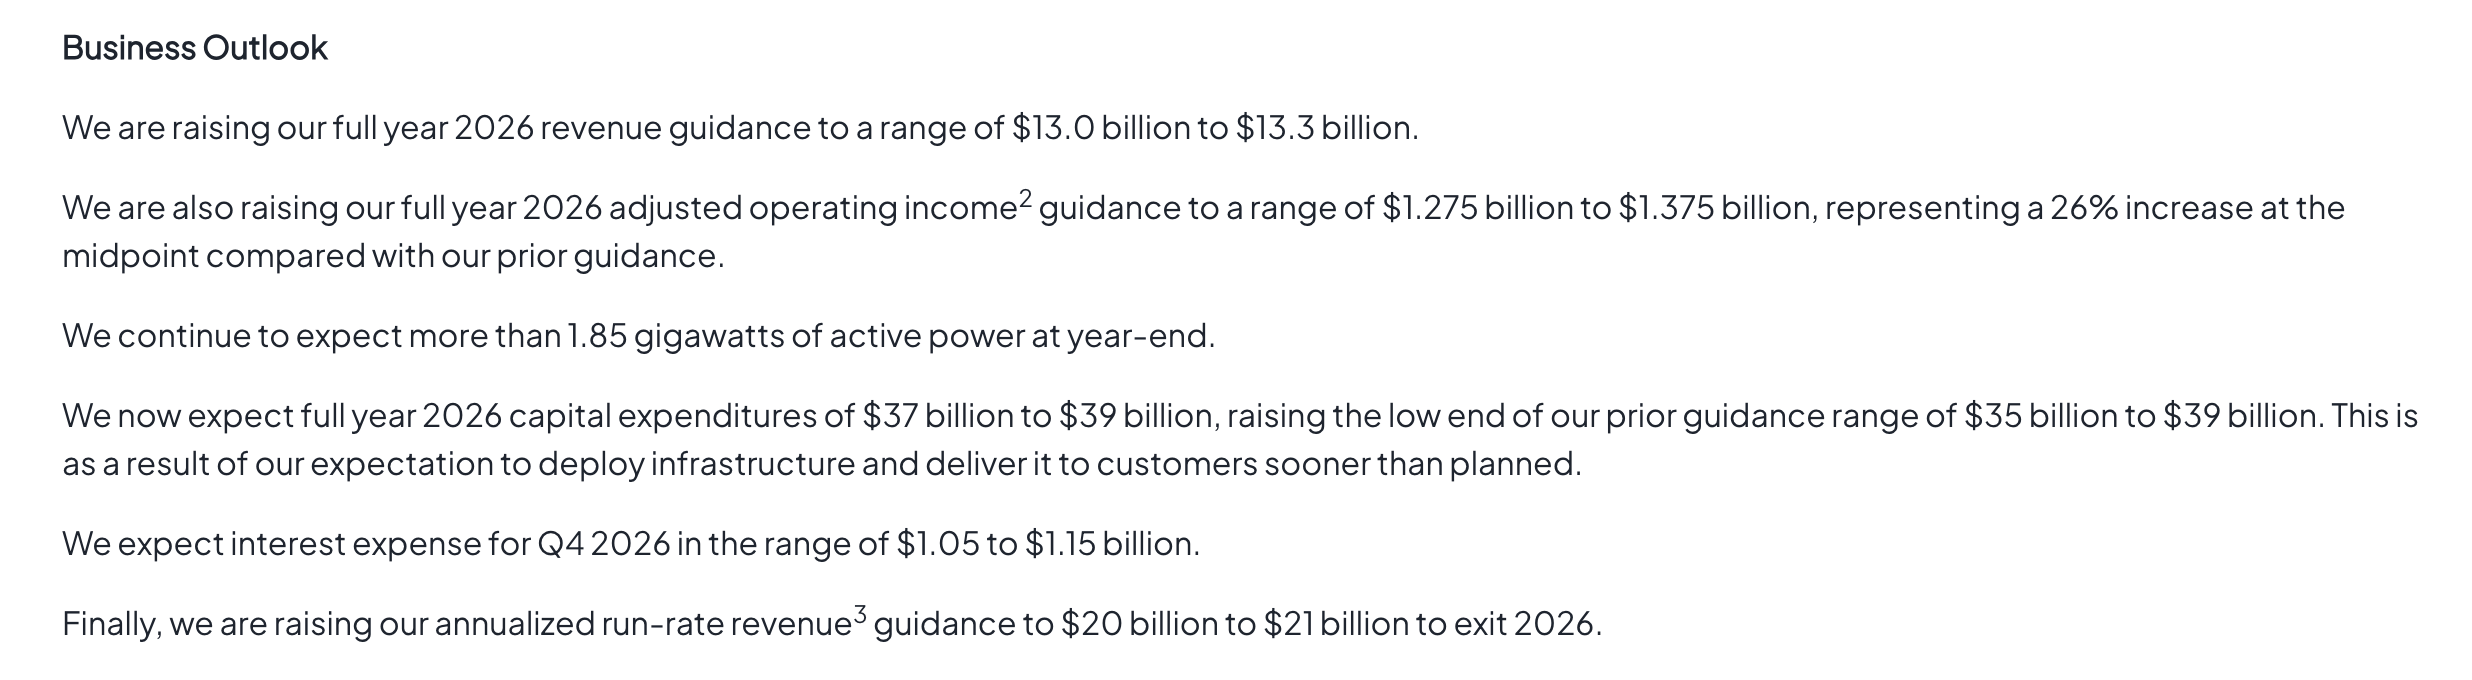
In the financial report, CoreWeave raised its full-year revenue guidance for 2026 from $12.4 billion to $13.2 billion to $13 billion to $13.3 billion; the full-year adjusted operating profit guidance was raised to $1.275 billion to $1.375 billion (an increase of 26% for the midpoint); the year-end annualized revenue run rate (ARR) target was raised to $20 billion to $21 billion.
Apart from the explosive financial numbers, management also displayed a strong seller's market attitude during the earnings call. CoreWeave CEO Michael Intrator stated on the call: "Our available capacity for 2028 is sold out. Although we have not yet pushed all of our 2028 capacity to the market, the portion that has been pushed is already sold out."
The supply-demand structure also gives CoreWeave the confidence to raise prices against the trend — in July of this year, CoreWeave raised the prices of all its product SKUs by about 25%, and then increased them by an additional 10% at the end of Q3, with prices still on the rise in Q4. CoreWeave CFO Nitin Agrawal revealed that the pricing of long-term contracts for 4-5 years has risen to $20 million to $25 million per megawatt, while short-term contract prices are as high as over $40 million per megawatt annually.
As for the "devaluation of old graphics cards" issue that short sellers once attacked, there has been a reversal. Intrator disclosed that due to the shortage of computing power, the rental prices for the previous generation Hopper architecture chips increased by 30% to 50% quarter-on-quarter in Q3, even exceeding the initial launch price when the contracts were signed.
Debt Pressure Remains Huge
Though the business is booming, flipping through the unvarnished balance sheet and cash flow statement reveals that the shorts' attacks are not unfounded — in the face of the heavy asset black hole of "buying cards with borrowed money," CoreWeave still faces suffocating debt pressure.
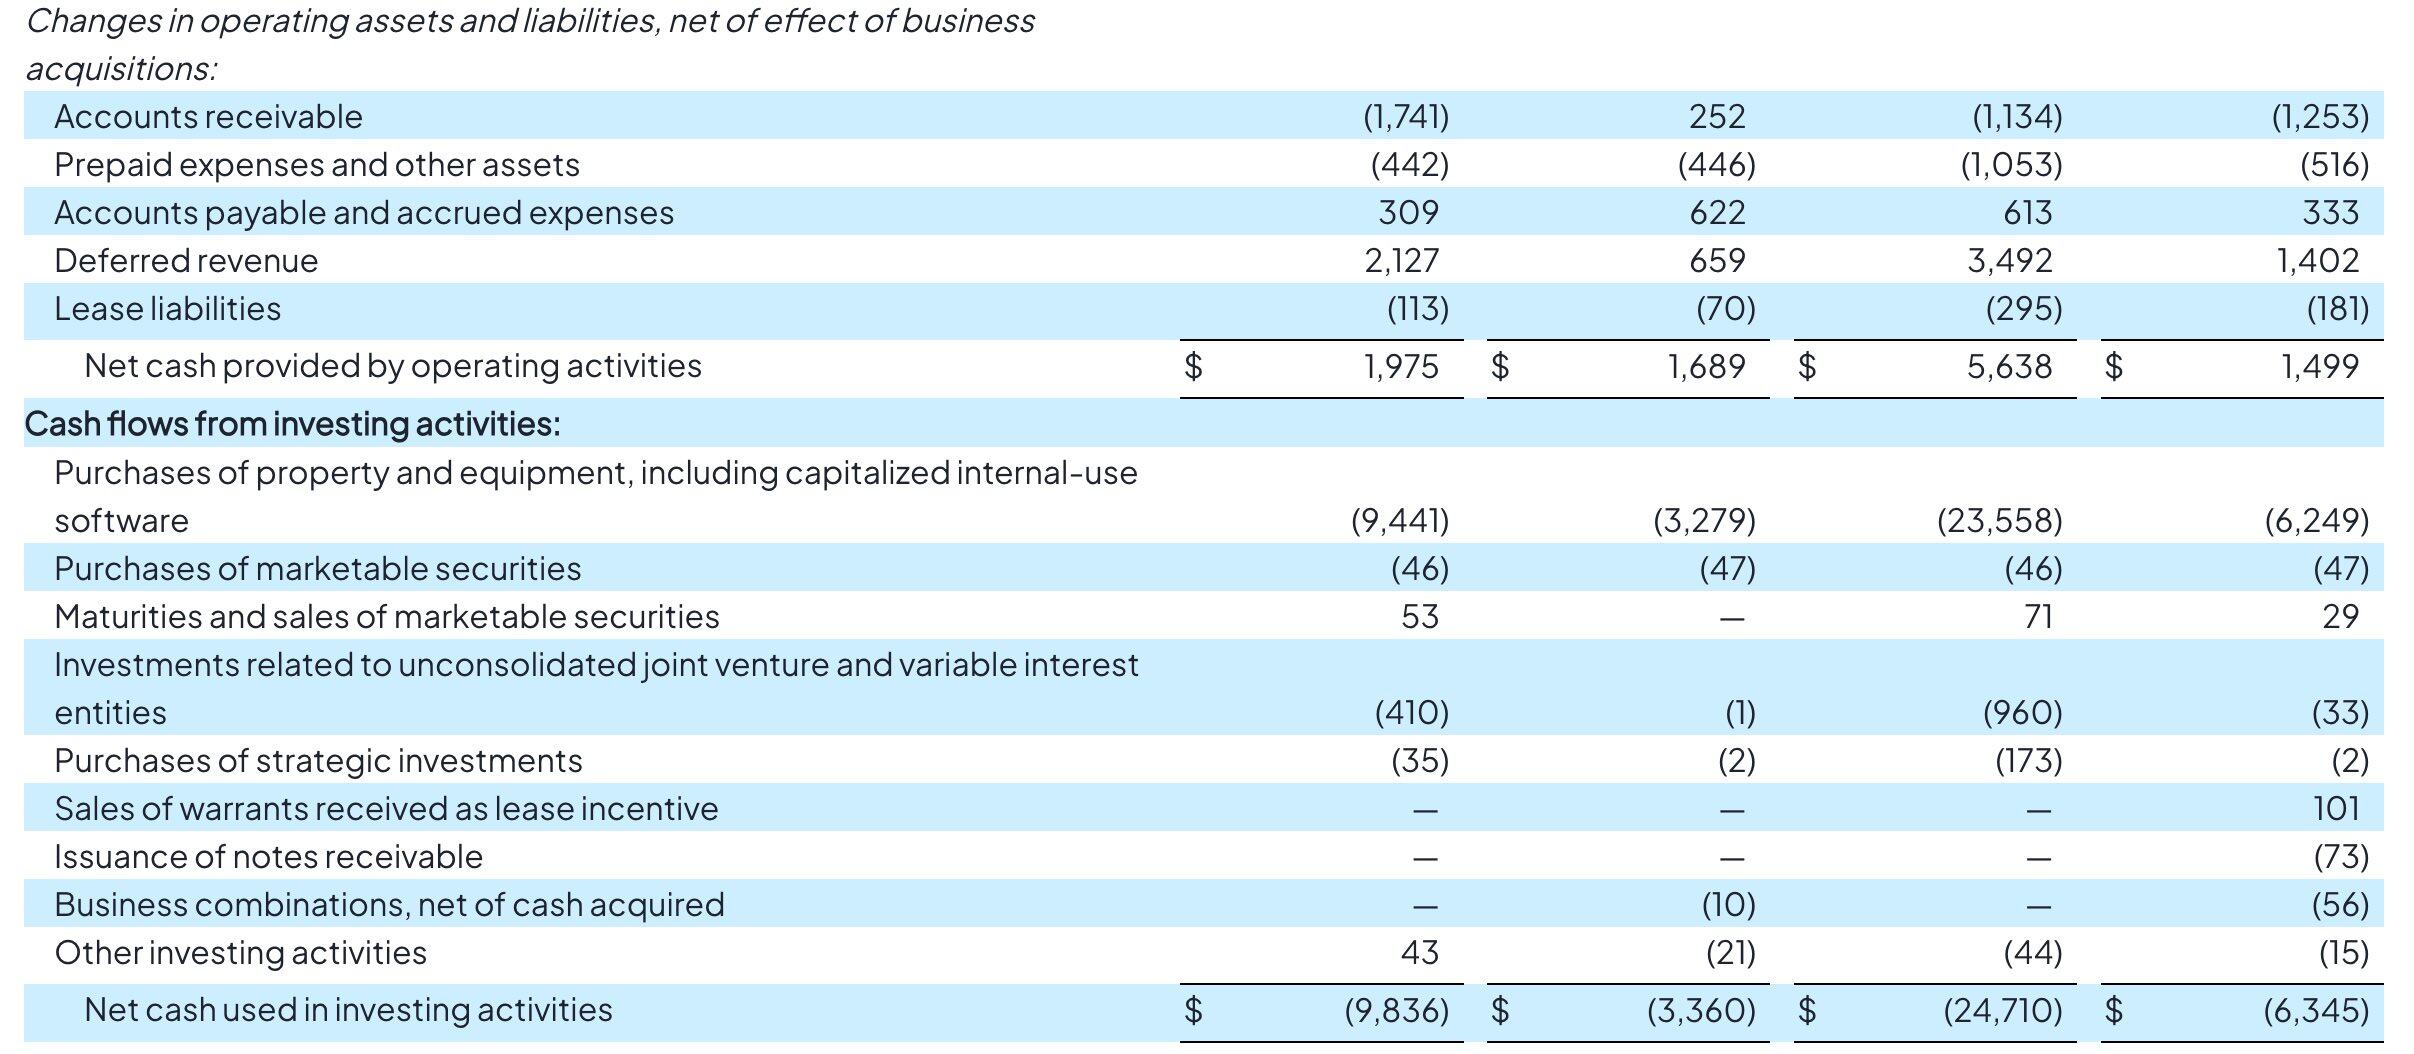
First is the shocking growth rate of debt and cash consumption. In the third quarter, CoreWeave's capital expenditures, according to company disclosure, reached $14.5 billion. Meanwhile, the cash flow statement shows that the actual cash expenditure for property and equipment purchases during the quarter was $9.441 billion. After deducting this cash outflow, the net outflow of free cash flow in Q3 reached $7.466 billion, with a cumulative net outflow of $17.92 billion in the first three quarters.
To fill the funding gap, as of September 30, CoreWeave's total debt soared to $46.873 billion. If further accounting for $18.697 billion in operating lease liabilities and $649 million in financing lease liabilities, the total debt and lease liabilities amount to approximately $66.22 billion.
The worsening trend of “profit and interest inversion” is also alarming. In the third quarter, CoreWeave’s adjusted operating profit was $379 million (GAAP operating profit was only $207 million), but the net interest expense for the quarter was as high as $846 million, which directly dragged the company into a GAAP net loss of $709 million. More critically, management expects that Q4 interest expenses will further rise to $1.05 billion to $1.15 billion (with annualized interest expenses as high as $4.4 billion), and even if the company increases its adjusted operating profit margin to 10%, there is still a significant gap between profitability and financing costs.
D.A. Davidson analyst Gil Luria commented, “Interest expenses are far higher than operating profits, indicating that the business revenue generated by data centers is still insufficient to repay the ever-increasing debt.”
In the face of enormous debt pressure, CoreWeave is trying three strategies to break the deadlock and buy itself some breathing room.
- Refusing to issue high-interest unsecured debt, relying on customer prepayments for “blood transfusion”: CFO Agrawal clearly stated that according to the current market yield rate, CoreWeave has no plans to issue new unsecured debt at the parent company level before the end of 2027. The alternative is to ask downstream customers for funds — within the next three months, the company expects to receive about $9 billion in customer prepayments and deposits (with currently 70% of transactions attached to prepayments), and management claims that most of the funding needs in 2027 will be covered by customer prepayments and financing from hardware partners.
- Shifting to asset-level collateral loans (DDTL): Avoiding the parent company's credit, directly using investment-grade large customer contracts as collateral. Currently, the company’s overall weighted average debt cost is 7.9%, and a new issue of investment-grade DDTL will be launched in the coming weeks, with an expected interest rate of 7% to 7.5%, which can cover over 90% of the capital expenditures for related projects.
- Hoping the "old cards" will generate cash flow after paying off loans: Since the loan cycle for buying cards is linked to the first customer contract, the expiration of the first contract signifies that the loan is repaid. Intrator revealed that in 2027 and 2028, over 130,000 and approximately 170,000 GPU contracts, respectively, will expire. Based on the current price increase trend of old cards, these 300,000 “debt-free” devices can generate nearly $4 billion and close to $10 billion of incremental annual revenue in 2027 and 2028, respectively, without additional capital expenditures.
However, market doubts have not been dispelled. Wells Fargo analyst Michael Turrin calculated that even in an optimistic scenario, CoreWeave’s capital expenditures in 2027 would reach as high as $66 billion, leaving a financing gap of at least $25 billion for new debt at that time; meanwhile, if a portion of the $9 billion prepayments comes from downstream AI startups that also rely on financing to burn cash, their risk resistance still needs to be questioned.
Alert Temporarily Paused, But Big Tests Lie Ahead
In addition to the hundred billion debt situation on the books, physical delivery friction and policy headwinds also squeeze the room for error.
The financial report shows that while CoreWeave's active electricity doubled to 1.7GW, the activation rate was only 37% (the total contracted electricity exceeded 4.6GW). Considering the tightening attitude towards high-energy-consuming data centers after the U.S. midterms, CoreWeave will need to accelerate the distribution of over 1.3GW of contracted capacity to overseas markets such as India, Indonesia, and Spain.
Ultimately, this unexpected third quarter report and the nearly 8% rebound after hours only prove that downstream AI computing demand remains scorching, and that leading players still have the leverage to pass on funding pressure to customers. It temporarily extinguished the imminent liquidity panic, but has not changed the perilous nature of the high-leverage sprint.
Under the immense pressure of $65.6 billion in broad debt and over $1 billion in quarterly interest, Musk's "total destruction prophecy" still hangs overhead. CoreWeave has won a breather tonight, but the real test of cash flow that will decide its life or death has just begun.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


