The US October CPI will be announced tonight at 21:30, with the market expecting overall and core month-on-month increases of 0.3% and 0.2%, respectively. Due to the lack of price data collection during last October's shutdown, there will be no official year-on-year readings this time. Around 6 AM Beijing time tomorrow, CoreWeave will hold its third-quarter earnings call, where the market will really focus on another number: the quarterly interest expense of $860 million to $940 million, and whether it can be absorbed by the adjusted operating profit of $200 million to $260 million.
Tonight at 21:30, we first look at CPI. Tomorrow morning at around 6 AM Beijing time, CoreWeave's earnings call will be another key point. What really matters is whether the valuation logic of AI assets will continue to tighten after putting the two sets of answers together.
1. CPI lacks year-on-year comparisons, tonight the market really focuses on core month-on-month
The biggest peculiarity of this CPI is that it misses a market's most familiar indicator: year-on-year.
In October 2025, the US federal government experienced a 43-day shutdown, during which the Bureau of Labor Statistics did not complete the monthly CPI price collection and has not subsequently filled the gap. Thus, this October CPI lacks a genuine benchmark from October 2025, and the Bureau of Labor Statistics will not publish the 12-month year-on-year changes for both overall and core CPI. The latest official data from September still shows an overall year-on-year increase of 3.7% and a core increase of 2.6%, and tonight's report will directly enter market pricing from month-on-month data.
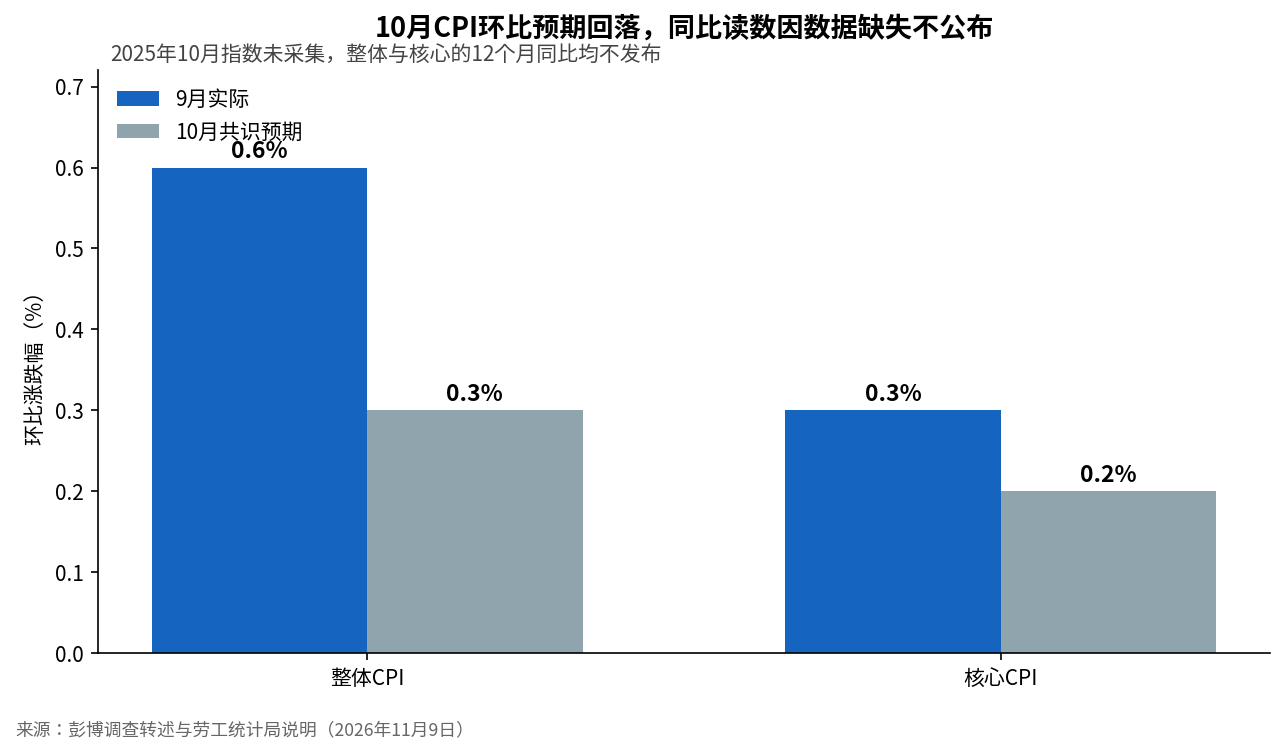
The market currently expects the overall CPI for October to rise by 0.3% month-on-month and core CPI to rise by 0.2%, which is a notable cooling compared to September's 0.6% and 0.3%. The decrease in gasoline prices will help slow the overall CPI, while for the Federal Reserve, what remains truly important is the core inflation excluding food and energy, especially whether the prices of housing, transportation services, and other sticky services can continue to slow.
This is also where the data might show contrast tonight; a number below expectations does not necessarily mean the removal of interest rate pressure. A core month-on-month increase of 0.2% nearly matches expectations but may not be enough to loosen the pricing for a December rate hike. What can really drive rate trading to reprice is if core CPI significantly falls below 0.2%, or conversely, goes back above 0.3%. Previously in October, non-farm payrolls increased by 165,000, exceeding market expectations, and a December rate hike has already become the mainstream pricing, with the latest market pricing around 84% (CME data quoted, on November 9, before the non-farm report it was 72.8%).
The real impact of tonight's CPI is not only on the December rate hike but also on whether the interest rate path for 2027 can continue to rise. Bank of America and Morgan Stanley currently expect a rate hike in December and March, with the terminal rate at 4.25% to 4.5%. If the core month-on-month is only 0.2% or even lower, long-term US Treasury yields, the dollar, and high-valuation tech stocks may have room to breathe. If core inflation rises back to 0.3% or even higher, the market will revisit the discussion of maintaining high rates for a longer period, and the AI sector is precisely one of the assets that reacts fastest to changes in capital costs.
In other words, the CPI answers whether money is expensive. CoreWeave's financial report needs to answer whether, even if money is expensive, can AI infrastructure still earn back the costs.
2. CoreWeave's biggest test, from revenue to interest
CoreWeave's revenue growth has become less of a suspense. The company’s second-quarter revenue was $2.575 billion, a year-on-year growth of about 112.5%. By the end of June, the revenue backlog was about $104 billion, with an additional commitment from customers of over $25 billion at the beginning of the third quarter. Active power capacity has reached 1.5 gigawatts, with contracted power on hand of about 3.7 gigawatts. The story on the demand side remains strong.
However, the market is now really concerned about how much funding these orders require to be fulfilled and who will bear the financing costs incurred before fulfillment.
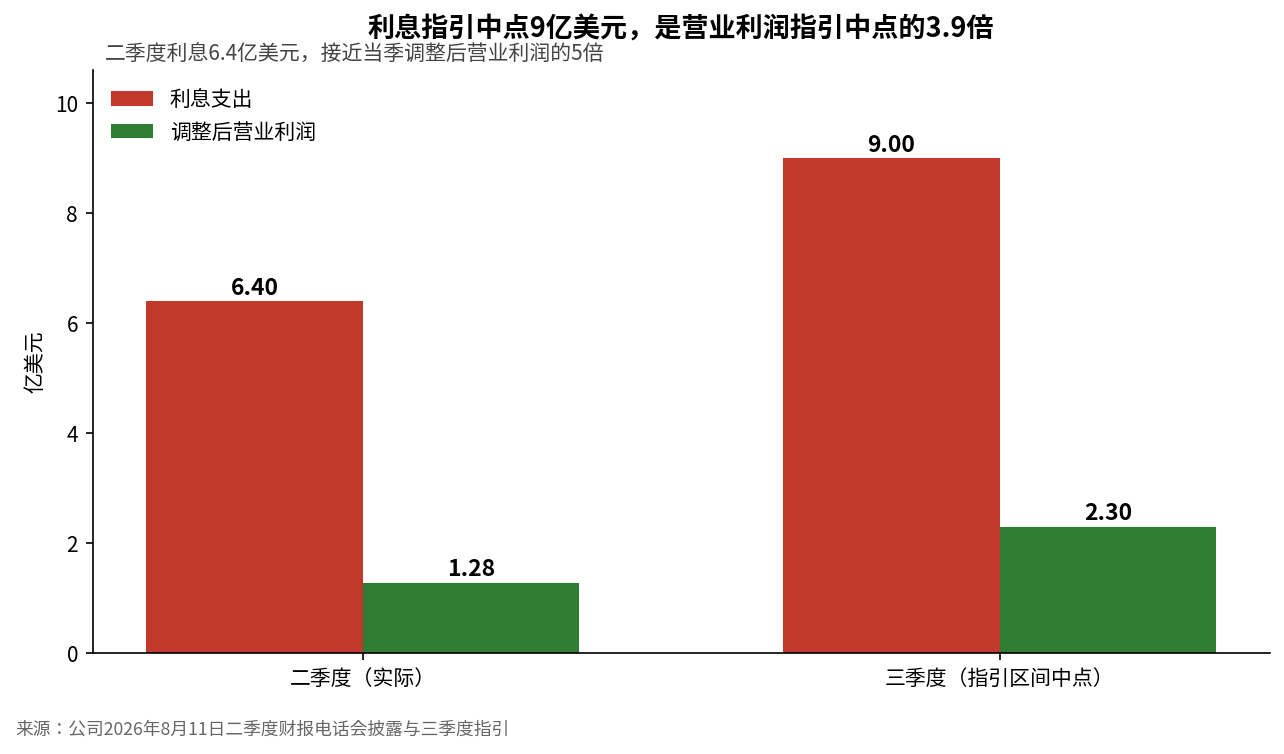
The company previously guided third-quarter revenue of $3.45 billion to $3.6 billion, interest expenses of $860 million to $940 million, and adjusted operating profit of $200 million to $260 million. Calculating based on the midpoint of the range, $900 million in interest corresponds to $230 million in adjusted operating profit, about 3.9 times. This figure itself is enough to explain the problem: CoreWeave is in a phase of rapid revenue growth while financing costs concurrently eat into operating profits.
The actual data from the second quarter is more illustrative. The company’s quarterly revenue was $2.575 billion, with a GAAP operating loss of $49 million and interest expenses of $640 million. Adjusted operating profit was $128 million, with interest nearing five times that amount. Adjusted EBITDA reached $1.51 billion, which superficially seems sufficient to cover interest, but this does not solve the real issue; CoreWeave still needs to keep investing massive capital to turn orders into actual revenue-generating computing power.
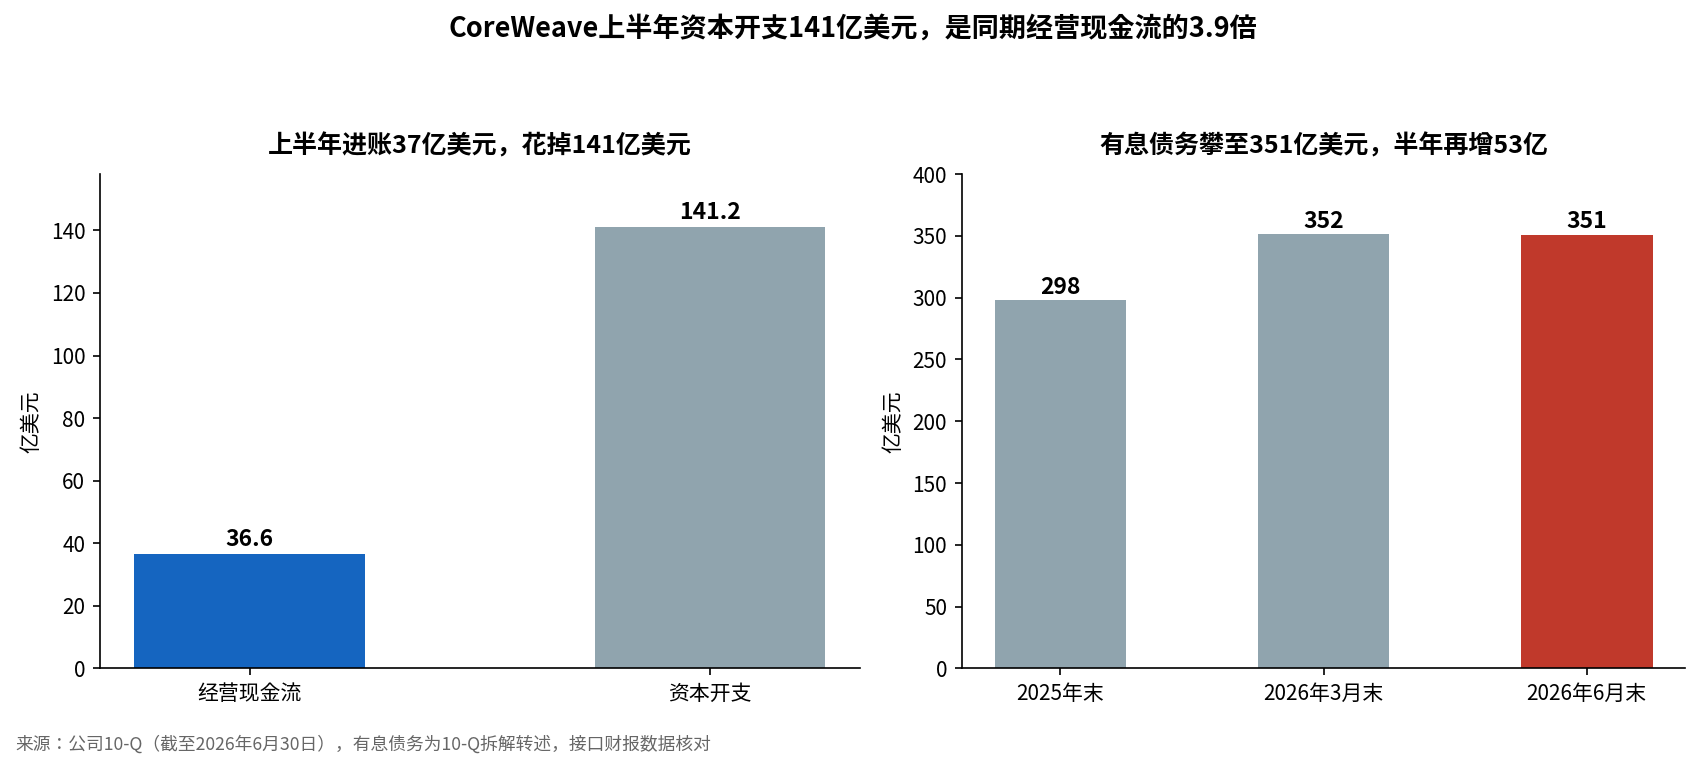
This is also why focusing solely on EBITDA can easily underestimate the risks. The capital expenditure in the second quarter was about $9.4 billion, slightly exceeding the guidance upper limit (as disclosed in the company’s call). The capital expenditure for the first half of the year was about $14.1 billion (cash flow statement), while operating cash flow was only about $3.66 billion during the same period. The company is capable of generating cash; however, the speed of generating cash falls far short of the pace of funding required for expansion.
Therefore, the most crucial points to read in tomorrow's earnings report have shifted from revenue to three other things: what the actual interest expense for this quarter is, how much new capacity has come online and started contributing to revenue, and the extent of financing preparations needed for continued expansion in 2027.
A backlog of $104 billion in orders is real, and 1.5 gigawatts of active installed capacity is also real, but orders are not cash, and installed capacity is not profit. Only if the new data centers are delivered on time, customers pay per contract, and operating cash flow begins to catch up with capital expenditures can CoreWeave's high leverage truly be considered leverage.
3. Bonds vote before stocks, and the market is worried about the financing chain
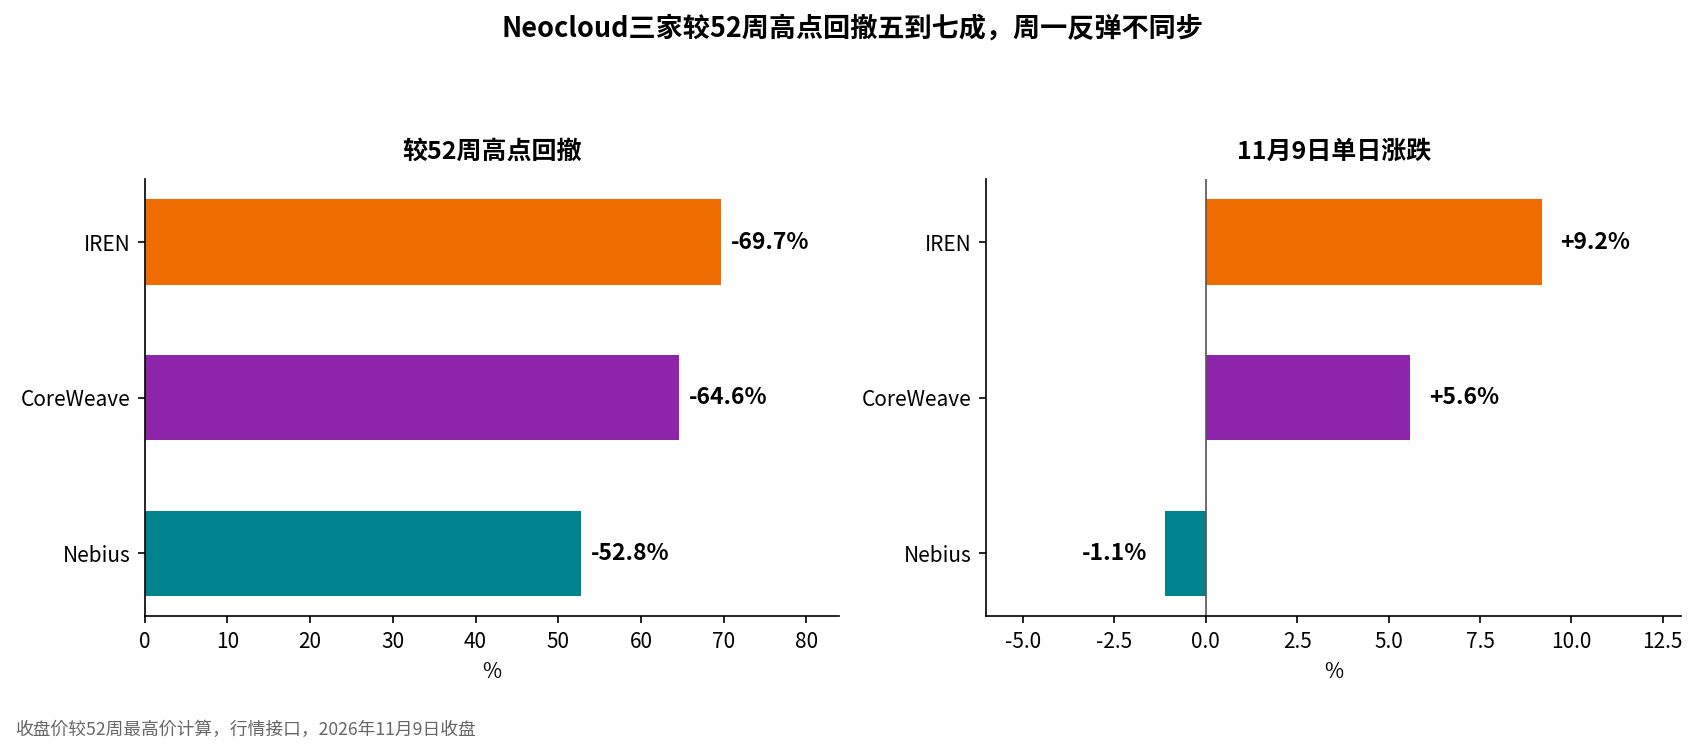
If we only look at the US stock market on Monday, it is easy to think that last week’s AI decline has come to an end. SOXX was up 7.49%, AMD was up 13.26%, Broadcom was up 8.78%, and CoreWeave was up 5.56%, showing a clear rebound after a steep decline (market interface, November 9 close).
However, the signals from the credit market are not so optimistic: CoreWeave's 8.5% coupon, dollar bonds maturing in 2032 previously fell to about 71 cents, with a weekly drop of about 8.5 points. The yield on unsecured debt has risen from about 10% to around 15%, and the five-year CDS spread has breached 1100 basis points. This pricing does not indicate that there is no demand for AI. It indicates that the market is starting to require AI infrastructure companies to pay a higher price for high leverage, high capital expenditure, and refinancing risks.
An even more critical signal is that this pressure is spreading to other points in the industry chain. Goldman Sachs recently observed in the credit market that chip sector CDS spreads have surpassed large cloud providers for the first time in three months. The market was previously accustomed to interpreting AI financing risks as the need for cloud providers to borrow money to build data centers, but is now further questioning how fast Neocloud's orders can grow if cloud providers themselves control capital expenditures, and whether the credit risks among chip manufacturers, data center operators, and GPU clouds will rise simultaneously if financing costs continue to increase.
Microsoft's actions have also made this issue more real. According to CNBC on November 6, Microsoft is reevaluating its Neocloud partner list and is inclined to prioritize its own data center resources. Microsoft has yet to decide which specific suppliers to drop but has already abandoned a site with UK Nscale and did not renew its contract related to Texas.
This does not mean Microsoft is abandoning Neocloud, nor does it imply that AI demand has suddenly vanished. The real change is that customers are beginning to scrutinize the economics between purchasing computing power from third parties and building computing power themselves more seriously than before. For companies like CoreWeave, how large orders customers are willing to sign is one thing, but whether orders can be delivered on time, whether customers will continue to place additional orders, and whether financing institutions are willing to provide funds for the next set of data centers are another matter.
Thus, the valuation logic of AI infrastructure is changing, shifting from how strong the demand is to whether demand, financing, and cash recovery can coexist.
4. After tonight, what to look for in AI trading?
Putting CPI and CoreWeave together, tonight is actually a clear stress test, and the results roughly fall into four combinations.
If CPI is below expectations and CoreWeave's earnings report is solid, it is the most comfortable combination for AI assets. A core CPI below expectations and a decline in long-term yields. If CoreWeave also provides lower interest expenses, smoothly ramped-up capacity, and clear financing arrangements, the market will again believe that high capital expenditure is merely a temporary phenomenon of the expansion phase. In such a combination, we cannot rule out the possibility that CoreWeave, AMD, Broadcom, data centers, and other high-beta AI assets will continue their rebound.
If CPI exceeds expectations while CoreWeave's earnings still remain solid, the market will begin to differentiate. Rates continue to be biased high, and companies that truly have cash flow, customer quality, and financing capability may continue to secure funds, while the valuation recovery of high-leverage Neocloud will be constrained. The AI market will not end because of this, but the overall strategy to buy into AI sectors will become increasingly difficult, and the market will focus more on who can truly convert orders into cash.
What we genuinely need to be vigilant about is if CPI exceeds expectations, but CoreWeave simultaneously reveals financing pressure. If core inflation reaches 0.3% or even higher again, long-term rates continue to rise, and CoreWeave's interest expenses exceed the upper limit of guidance, capacity delivery experiences delays, or management cannot provide sufficiently clear answers regarding the 2027 financing arrangements, last week's AI decline might exceed the clearing of positions, and the valuation system may begin to further shrink.
Conversely, if CPI is below expectations but CoreWeave's financial report is weak, it also cannot be straightforwardly interpreted as a full benefit for the AI sector. A decrease in rates can relieve valuation pressure but does not solve the company's cash flow and debt problems. In this scenario, funds are more likely to shift from high-leverage AI infrastructure to AI beneficiaries with healthier balance sheets and stronger free cash flow.
This is also the most noteworthy point tonight: CPI determines the cost of capital, CoreWeave determines whether AI expansion can still hold under high capital costs. The former affects the valuation denominator of the entire market, while the latter directly tests whether AI infrastructure companies can cover this expansion model with profits and cash flow.
Monday’s rebound indicates the market is willing to buy back AI assets that have been smashed down, but whether the rebound can turn into a trend recovery cannot be determined by stock prices alone. We should first look at core CPI tonight at 21:30 and then check CoreWeave's interest, capacity, and financing tomorrow morning. For high-beta AI assets, the combination of these two numbers is more significant than a single earnings report or macro data.
5. In conclusion: AI demand has not disappeared; what is expensive is the money to pay for AI
What CoreWeave currently needs to be most vigilant about is not the sudden disappearance of the $104 billion order backlog nor the disproof of AI demand. The real issue is that the revenue realization of AI infrastructure takes time, while debt interest and capital expenditures need to be paid now.
The $640 million in interest for the second quarter corresponds to $128 million in adjusted operating profit, and the guidance provided by the company for the third quarter pushes this ratio to nearly four times. Capital expenditures of about $14.1 billion for the first half year correspond to approximately $3.66 billion in operating cash flow. As long as capital expenditure continues to grow rapidly, the company needs to continually enter the debt and equity financing markets, and if financing costs continue to rise, valuations based on high growth will increasingly depend on whether cash flow can be smoothly realized in the coming years.
Therefore, tonight's analysis is not just whether CPI is 0.2% or 0.3%, nor only CoreWeave's post-market rise or fall. What truly needs to be matched up is whether the four variables of interest rates, interest, capacity, and financing can all coexist.
If CPI cools and CoreWeave's financing capability remains stable, AI trading may return from last week’s panic-driven deleveraging to a fundamentals-driven market. If CPI continues to exceed expectations while CoreWeave's financing pressure further exposes itself, the market will need to reprice high-leverage AI infrastructure.
This time, the question the market needs to answer has shifted to a more realistic one: how much money is required to continue the prosperity of AI?
Disclaimer:
This content is for general informational purposes and market commentary only, based on publicly available information as of the time referenced in the text, and related market data, expectations, and probabilities may change depending on market conditions. The views and investment strategies quoted from third-party entities, analysts, or other individuals represent those third parties' views at a specific time and do not represent BIT's views or recommendations. This document does not constitute investment advice, investment research, offer, solicitation, or recommendation for any security, investment product, or trading strategy, nor should it be relied upon for making any investment decisions. The financial markets carry risks, and the prices of securities and market performances may fluctuate; past performance and previous market trends do not guarantee or represent future outcomes. Investors should independently assess the relevant risks based on their own circumstances and seek professional advice when needed.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。


