First, let’s look at two numbers.
On November 3, 44 local referendums on "suspending data center construction" were held, with 43 passing. The approval rate was 97.7%.
On November 5, the Nasdaq fell by 5.5%, the Philadelphia Semiconductor Index plunged by 12%, and the Nasdaq 100 saw a one-day evaporation of over $2.3 trillion. Nvidia fell by 9.3%, AMD by 17.3%, and Nebius by 15%.
There were two days in between. Many believed it was a coincidence, but it wasn’t—these two events are two sides of the same coin.
An Election Misunderstood
The Democratic Party secured both the Senate and the House, and also won governorships in Texas and Georgia. Media headlines proclaimed that "American voters said no to AI".
However, if you look at NBC's election day polls, you will find a more precise statement: 76% of respondents opposed building data centers in their own communities.
Note the key phrase: in their own communities.
What they oppose is not the large models, not AGI, not technological advancement. Their worry is about rising electricity prices, noise pollution, and local infrastructure being overwhelmed.
But if you think this is just "sympathy for the electricity bill," then you’re downplaying this issue. The electricity bill is just the first invoice, and it’s the one that arrives last.
The Electricity Bill is Just the First Invoice
A recently released storage report by Counterpoint for the third quarter of 2026 contains a peculiar set of numbers.
The global DRAM market revenue skyrocketed by 369% year-on-year, achieving the highest quarterly growth rate in the history of the storage industry; the average selling price reached $1.9 per Gb, equivalent to about 13 yuan per GB.
But in the same quarter, DRAM bit shipments grew by only about 4%.
Shipments hardly moved, yet revenues increased nearly fourfold—it's all about price increases. The exact words of Counterpoint analysts are: AI has transformed storage from a commodity into a scarce high-value resource; buyers are now scrambling for "whether they can get goods" rather than "whether they can get them cheaper."
The reason lies in HBM.
HBM is high-bandwidth memory located next to AI accelerators. It has a physical characteristic: producing 1 bit of HBM consumes about three times the wafer capacity of standard DDR5. The chip area is larger, the stacking process is more complex, and yield loss persists throughout.
Thus, Samsung, SK Hynix, and Micron did a simple arithmetic calculation: allocate wafers to HBM. TrendForce data shows that the share of HBM shipments from the three major manufacturers increased from 18% of total DRAM shipments at the end of 2025 to 22% by the end of 2026, with a projected reach of 30% by the end of 2027; meanwhile, the share of HBM bits supplied only rose from 8% to 9%, then to 13% during the same period.
Translation: Nearly one-third of wafers are allocated to produce a supply that makes up about one-eighth of the bits. The remaining production capacity is reserved for your phone, your computer, and your home NAS.
AI is not "using" storage; it is "occupying" storage. This is not a price war; the capacity is being entirely bought out.
The Cost Ultimately Falls in the Shopping Cart
The downstream numbers are much more intuitive than the electricity bill.
Memory: 32GB DDR5 kits, about 900 yuan last year, now nearly 4000 yuan, an increase of over 300%; 16GB DDR5 rose from 350-400 yuan to around 1500 yuan. Hard drives: The mainstream 1TB solid-state drive went from 410 yuan to 950 yuan.
The proportion of storage chips in the material costs of laptops rose from about 15% in 2025 to over 35%.
Consequently, the price of complete machines jumped: Lenovo Xiaoxin Pro 16, with a mainstream transaction price of about 4800 yuan at the end of 2025, new models for 2026 are now priced at 7500-7900 yuan; the average price of the Legion series has increased by about 5000 yuan, with originally 10,000 yuan models now reported at 15,000 to 16,000 yuan, and certain models increasing by 3800 yuan over four months. Asus has adjusted prices across the board by 15%-25%, while Apple raised global MacBook prices by about 20% in June, and the base model of iPad directly increased by 800 yuan.
Graphics cards are worse: The official recommended price for the RTX 5080 is 8299 yuan, and in late October, e-commerce prices surged to 20,000 yuan, with the average price of the entire RTX 50 series at 1.7 times the suggested retail price. The 32GB version of the 5090 rose from 35,000 yuan before September to 54,000 yuan by mid-October.
The most straightforward result: laptops priced under 5000 yuan are basically extinct in mainstream channels.
Manufacturers are very honest about this—low-cost models are now "losing money on every sale," and they can only collectively cut off entry-level product lines. A dealer said that the price increases will have to continue for at least another year, and non-essential purchases are advised against.
Consumers are already voting with their feet: during the first half of 2026, online sales of laptops in China fell by over 40% year-on-year. The second-hand trading and repair business in Huaqiangbei, Shenzhen, has actually improved—people are no longer switching to new machines, but opting to repair the old ones.
There’s a figure that can explain it all: in Nvidia's second quarter of fiscal year 2027, $96 billion in revenue included $89 billion contributed by data centers, representing 92.5%; personal GPU business was only left with 5.45%.
It’s not that graphics card manufacturers don't want to sell to gamers; selling to AI is more profitable. The same wafer, the same batch of capacity, goes to the highest bidder.
This follows the same logic as electricity bills: your demand hasn't disappeared; it has simply been pushed to the back of the line by a buyer willing to pay more.
Therefore, the neighbor’s question should actually be asked in a more complete way: it's not "why did my electricity bill go up," but rather "why did my electricity bill go up, and why did my son's back-to-school computer become 4000 yuan more expensive?"
Texas's newly elected governor, Gina Inohosa, stated quite directly: suspend approval of new data center projects until the state legislature passes laws to protect local residents' interests.
What is Texas? Over the past few years, it has become the core battlefield for AI infrastructure expansion in the U.S., thanks to lenient regulations, cheap electricity, and land. There are currently 335 data centers in operation and at least 248 projects in planning or progress.
Now, this battlefield is about to close down.
Shawna Thomas, co-founder of the political action committee Guardrails Alliance advocating for AI regulation, said something that I think is the key to the whole matter:
Opposing the expansion of data centers is one of the most bipartisan political issues she has seen.
Bipartisan consensus. This term weighs heavily. In today’s America, the only issue that can unify voters from both parties is left to one—don't make me pay more.
This is the Most Crucial Part
In recent years, the AI industry has had a set of established narratives to deal with regulation: talking innovation, national security, and "falling behind means getting hit".
This set of rhetoric is effective with lawmakers and at hearings. But this time its opponent is not lawmakers; it’s the neighbors.
The neighbor is not debating text with you, does not care about your benchmarks, and is not concerned with any AGI timetable. He just asks one question:
"Why did my electricity bill go up?"
You cannot answer this question with "We are advancing human civilization."
What's more damning is that this is no longer a legal problem; it’s a physical one. Data centers need electricity, water, land, and the neighbor's approval; your next computer needs memory, flash storage, and video memory. You can lobby a congressman, but you can't lobby an electricity bill, nor can you lobby a laptop that costs three thousand yuan more.
UBS previously estimated that the newly added data center capacity in the U.S. by 2028 would potentially be affected by construction pauses by about 30%. Yorkville's analysts are even more direct: the planning and construction of up to 1000 data centers may slow down.
Meanwhile, Dina Powell McCormick, president of Meta Platforms, revealed that some companies are already considering building data centers outside the United States.
Capital can run away, but bills cannot.
The Market Turned Faster than Politicians
Many attribute the crash on November 5 to the election. But looking at the timeline, the market had already begun to back away.
The Nasdaq has dropped nearly 12% since its historic high on October 6, having already entered a technical correction range before the crash.
The real signal lies in the details: the five-year credit default swap (CDS) spread for CoreWeave has expanded to 1267.9 basis points, a record high.
What is a CDS spread? Simply put, it is the market's price for the "default risk" attributed to this company. 1267 basis points mean investors believe that the risk of lending it money has risen to the point where an extremely high premium is required.
And CoreWeave is precisely the most typical example of this round of AI expansion: building data centers by taking on massive debts, betting that computing demand will always rise.
When financing costs rise and return cycles remain unclear, this model is the first to collapse.
So, November 5 was not "a sell-off triggered by elections;" it was a valuation reassessment that had already been underway, triggered by the election.
The Most Heartbreaking Evidence: Three Consecutive Valuation Reductions
What reveals the issue more than stock prices is IPO pricing.
Anthropic's valuation curve reveals the whole picture:
In September, the target was $2 trillion.
By early November, it was estimated at $1.5 trillion.
After November 5, three major investors indicated it might be closer to $1 trillion.
One investor even suggested a delay in going public.
Note that as of September 30, Anthropic had $146.6 billion in cash. It certainly does not lack money.
A company that does not lack cash is being advised by investors to "consider going public later"—this is not a money issue; it’s about "how much AI is really worth," and it needs a re-vote.
OpenAI was even more direct: it secretly submitted its IPO, reducing the fundraising target from about $30 billion to $20 billion, and the valuation from $1.4 trillion to $1.25 trillion.
They trimmed the fundraising by a third and reduced the valuation by nearly 11%. This is the market repricing with real money.
There’s Also a Knife Hanging
After the election, action on Capitol Hill sped up.
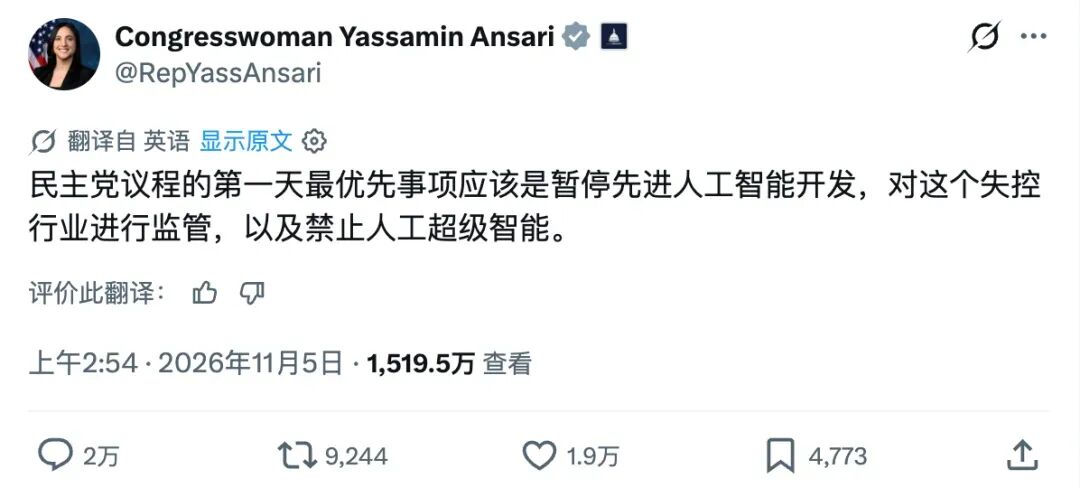
Representative Yassamin Ansari has posted, demanding that on the first day of the new Congress, the advanced AI should be suspended and superintelligence banned. The basis for this stance is the "Artificial Superintelligence Prohibition Act" introduced in the Senate by Sanders on September 23.
The core of the bill has two main points:
First, prohibit superintelligence.
Second, suspend training of advanced models capable of 10²⁵ operations.
The number 10²⁵ is worth pondering—it roughly represents the training level of the most advanced models currently. In other words, this threshold is not drawn in a far-off future but is drawn at the doorstep of existing cutting-edge models.
What’s more severe is the accountability clause: reckless violations by decision-makers could lead to penalties of up to 20 years.
Of course, it must be stated objectively: the probability of this bill passing is questionable. There is no unified line in the Democratic Party on "how to balance innovation and safety," and there is still complex room for negotiation between federal policies, state regulations, and local approvals. Adam Kovacevich, founder of the pro-technology Chamber of Progress, also reminded that it is still unclear whether the Democrats will adopt Biden-like strict regulations or revert to Obama-like friendly approaches.
But the direction is already clear: the AI industry's past approach of "expanding first, complying later" is closing.
Conclusion
What’s most worth noting for China's AI industry is not "the U.S. is in chaos," but a question that everyone involved in AI will have to answer sooner or later:
When the cost of AI falls on ordinary people, how do you plan to settle this bill with them?
The answer in the U.S. is: it has collapsed. Because over the past two years, the industry has only been telling stories to the capital market and has never talked to the neighbors, nor to the person ready to buy a new computer.
However, it’s not all bad news. Some analysts point out that a moderate slowdown in infrastructure investment may actually curb excessive capital influx and reduce the risk of a bubble. The industry is also saving itself: DeepSeek V4.1 is reducing HBM occupancy with a new architecture; cloud providers are beginning to lower single machine storage configurations; memory pooling solutions are being promoted; and new wafer fabs are set to gradually release capacity starting in the second half of 2027. Katie Barr of Glen Echo also warned not to simply interpret the election results as "Americans oppose technology"—voters are genuinely concerned about living costs, jobs, safety, and whether they can participate in significant community decision-making.
Ultimately, the key is: they do not want to stop; they want to participate.
Therefore, the only real solution is to convert AI’s value into something ordinary people can see. It’s not the parameters released at a conference, nor the valuations in a PPT; it’s lower electricity costs, a more stable power grid, affordable computers, real employment, and knocking on the neighbor's door before starting construction.
Computing power can be bought, land can be purchased, electricity can be purchased.
Only "consent" cannot be bought.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到[email protected],本平台相关工作人员将会进行核查。