Recently, the Chinese internet and crypto community have been buzzing with a macro announcement. The core reason is a statement made by Li Zhong, the Vice Minister of the Ministry of Human Resources and Social Security, during a press conference held by the State Council on October 10, introducing the high-quality development of employment and social security during the "14th Five-Year Plan" period. He emphasized the need to adhere to "guaranteeing all who should be insured" and to mobilize uninsured individuals through innovative methods like "finding people through data", focusing on promoting the transition of flexible workers, migrant workers, and new employment form personnel from urban resident pension insurance to employee pension insurance, aiming for a basic pension insurance coverage rate of over 95% during the "14th Five-Year Plan" period.
This statement quickly sparked heated discussions and complex social perceptions online. On one hand, in light of the objective realities of the pay-as-you-go system, population aging, and low birth rates, public concern about the long-term sustainability of the social security system has reached unprecedented levels. On the other hand, for groups facing cyclical income fluctuations and working at the forefront of the digital economy, under the premise of compliance and legality, using diversified personal asset allocations to supplement and enhance risk resistance is the rational choice that balances present and future needs.
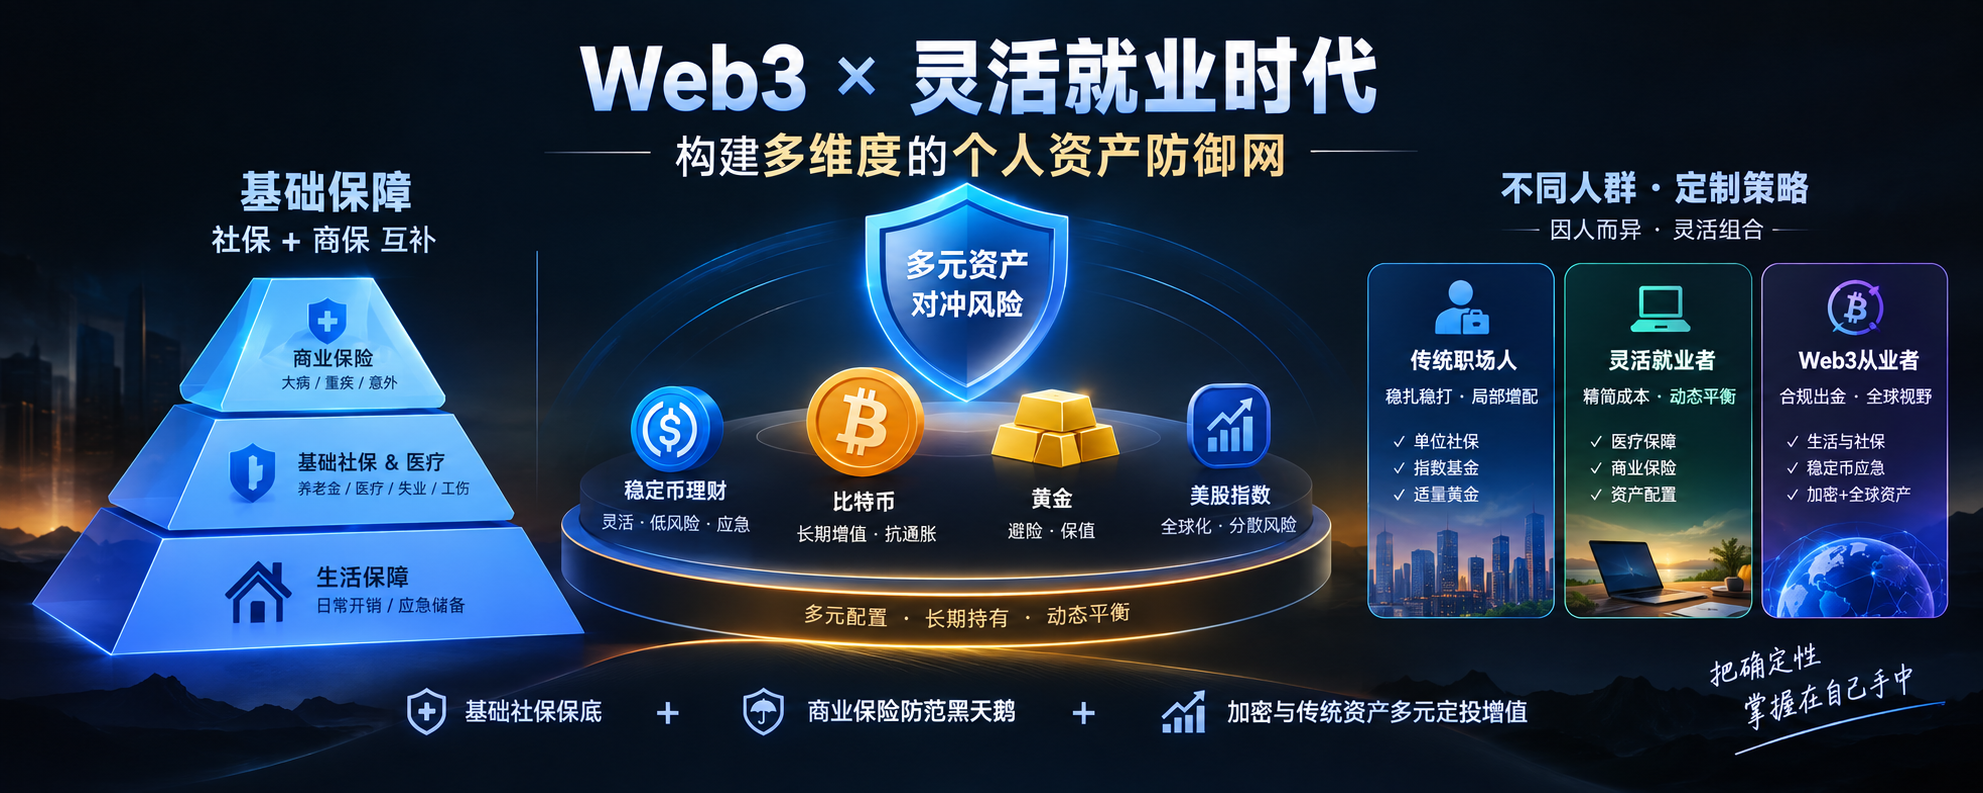
1. Strengthening the Foundation: The Perfect Complement of Basic Social Security and Commercial Insurance
Before discussing any advanced asset allocation, it is essential to face the value of the basic safety net.
- Do not easily interrupt contributions when employed: For those still relying on traditional workplaces, companies bear a considerable proportion of social security costs (especially the major expenses of medical and pension). Although personal contributions need to be deducted, the cost-effectiveness is exceptionally high. Particularly, employee medical insurance serves as the most solid foundational shield against significant health risks due to its long-term accumulation and lifetime medical benefits after retirement.
- Cost-effectiveness evaluation for flexible workers: For freelancers or flexible workers, the cash flow pressure of fully self-contributing to employee social security is immense. A more pragmatic strategy is to prioritize medical coverage (selecting the minimum employee medical or resident medical based on personal economic situation) to ensure fundamental reimbursement rights for medical treatment; while for the pension portion, a dynamic evaluation based on cash flow duration can be used to make proportionate choices.
- The necessity of supplemental commercial insurance: Basic social security resolves "minimum livelihood and basic medical care," but in the face of high-level medical needs from serious illnesses, special drug expenses or interruptions in household income, commercial insurance (such as million medical insurance, consumer critical illness insurance, and accident insurance) is an indispensable leverage tool. Using a small amount of premium to leverage high-risk transfer can avoid the devastating impact of illness-induced poverty on long-term investment plans.
2. Building Long-Term Pension Assets with Crypto Assets and Diverse Financial Management
For groups with significant income fluctuations working in Web3 or global remote work environments, traditional single savings and social security often struggle to fully hedge against inflation, the dilution of fiat purchasing power, and systemic rule changes. Thus, utilizing crypto assets and modern financial tools to create a long-term "personal pension/risk-resistance asset pool" has become a realistic choice for many.
1. Low-risk Income Strategy: Balancing Liquidity and Emergency
Hold a portion of short-term living funds or cash flows waiting to be invested in stablecoin form, and obtain a certain low-risk return through compliant channels or mainstream platforms.
Real Case Reference: According to information released by Binance VIP customer managers, the platform offers an annual interest rate of up to 5.5% APR for USDC on-demand financial products (VIP users can enjoy up to 5.5% annualized for the first 200,000 USDC). The key is its "on-demand" property, meaning funds do not need to be locked and can be accessed at any time.
For a deposit of 100,000 USDC, calculated at an annualized rate of 5.5%:
- Expected daily earnings: about 15.11 USDC
- Expected monthly earnings: about 453 USDC
- Expected annual earnings: about 5,500 USDC
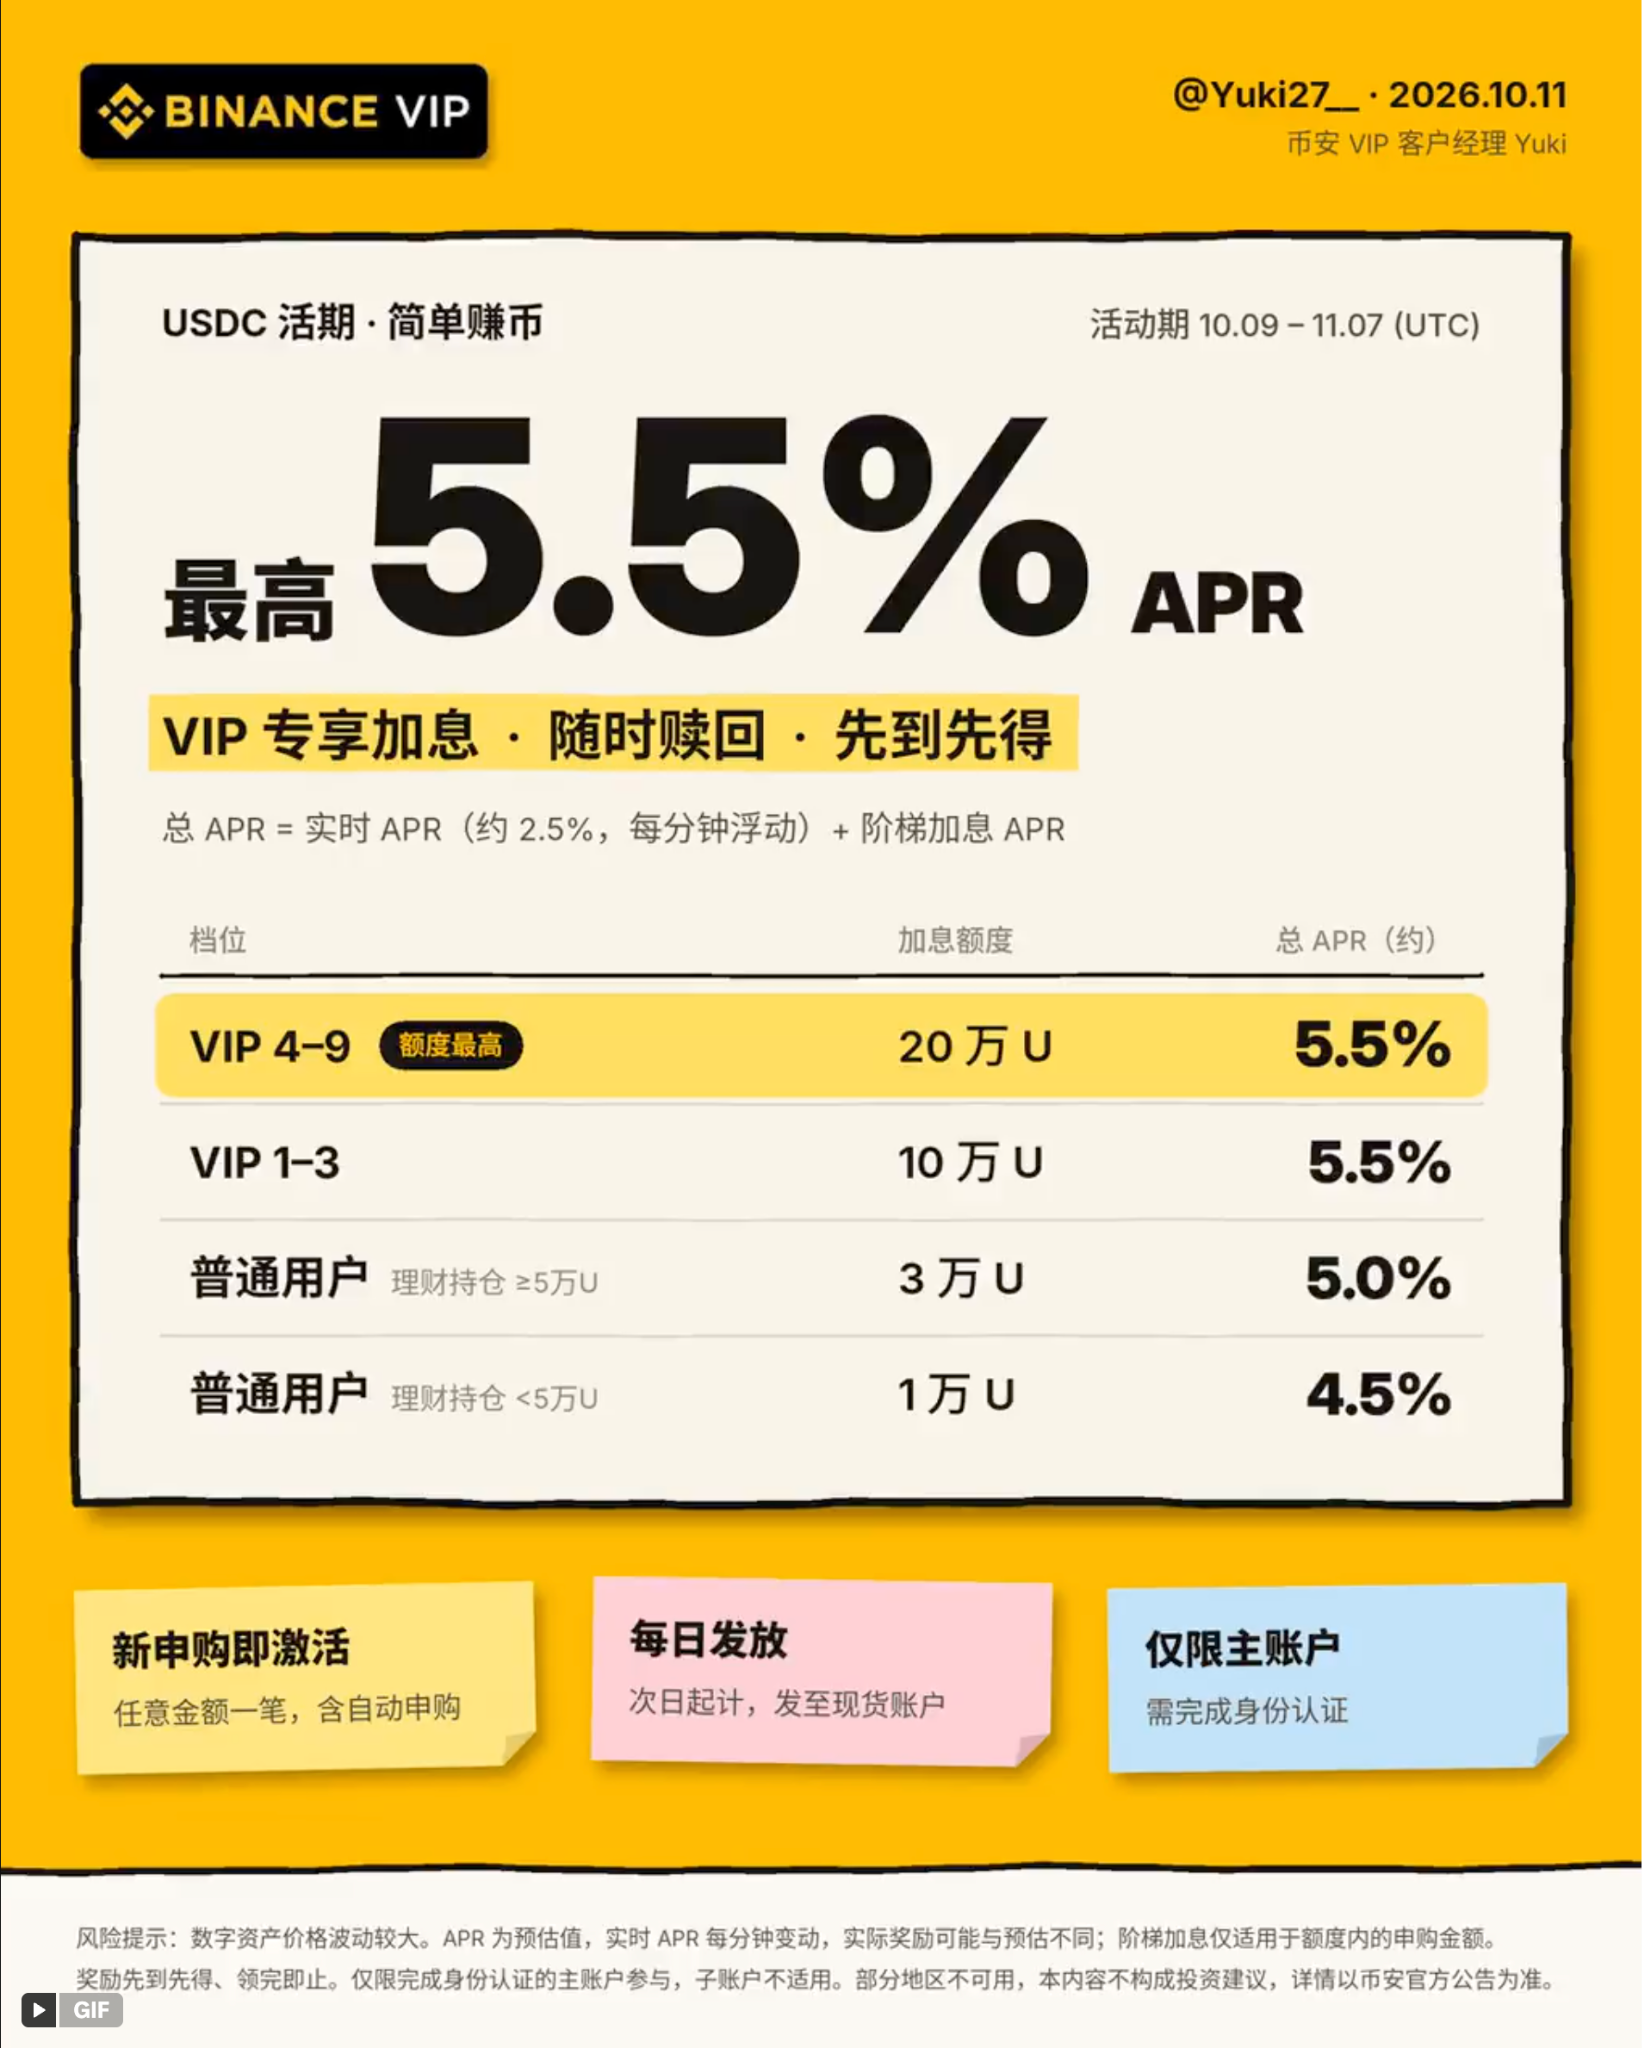
This strategy is very suitable as a "contingency fund pool" and "waiting cash flow" for individuals or families, obtaining returns higher than traditional bank savings while not sacrificing fund flexibility.
Exclusive Benefit Tip: Registering on Binance with the invitation code aicoin668 can enjoy the following exclusive benefits:
Binance registration link:
https://jump.do/zh-Hans/xlink-proxy?id=3
- Benefit One (New Customer Up to 440U):
- Deposit 100U + Trade 100U → Get a 100U Position Voucher (three tiers can be stacked, deposit 100U to obtain the first tier)
- Deposit 1,000U + Trade 50,000U → Receive an additional 300U Position Voucher
- Deposit 3,000U + Trade 200,000U → Receive an additional 40U Cash Voucher
- Benefit Two (Mystery Box Lottery): Complete registration + Deposit 50U + Trade 100U + Log in to the App to receive one mystery box for the event, randomly drawing up to 25 RE tokens.
2. Regular Investment in Blue Chip Assets: Hedging Against Inflation and System Changes
There is a representative saying circulating in the cryptocurrency community - "Use part of your monthly idle surplus to regularly invest in Bitcoin, gold, or core U.S. stock indices."
- Core Logic: Global fiat currency overissuance and long-term inflation pressure are continuously eroding the real purchasing power of cash. Cryptocurrencies represented by Bitcoin, as well as traditional gold and the global core U.S. stock index, have strong anti-inflation and cross-cycle properties.
- Real Consideration: Although historical long-term data show that these core assets have significant excess return potential, cryptocurrencies are highly volatile. Participants must have strong psychological resilience and be able to calmly face downturns of over 50%, and absolutely must not use essential living funds or borrowed money to participate in this.
3. Position Ratio Recommendations: Strictly Adhere to the Bottom Line, Avoid All-in
Crypto assets and alternative investments can never replace insurance and basic living guarantees. A healthy financial pyramid should follow a scientific proportional allocation:
- First Layer (Foundation): Basic living expenses + minimum social security/medical coverage.
- Second Layer (Breakwater): Commercial insurance and emergency cash flow (including some compliant stablecoins).
- Third Layer (Growth Engine): Reasonable allocation of remaining investable capital. In this layer, long-term crypto positions can occupy a certain proportion based on personal risk preferences, but one must never go all-in.
3. Scenario-based Implementation: Practical Combination Strategies for Different Groups
For ordinary people with different income structures and occupational forms, differentiated asset combination plans can be adopted:
- Traditional Office Workers: Steady and Sure, Partial Increase
Strategy: Rely on existing units to contribute sufficient social security and enjoy policy dividends.
Efficiency Increase: Use spare time or yearly surplus to allocate in traditional index funds (such as CSI 300 or S&P 500) and some gold, gradually building a personal capital reservoir.
- Flexible Workers/Freelancers: Streamline Costs, Dynamic Balance
Strategy: Prioritize medical coverage (choose the minimum resident medical or social security) paired with commercial medical insurance to cover gaps.
Efficiency Increase: Allocate the significant difference saved from fully contributing to high-level employee social security into scientific asset configurations - part regularly investing in U.S. stocks/gold and part allocated to low-risk financial management, achieving a triad of "social security baseline + commercial insurance for unexpected events + personal investment appreciation."
- Web3/Pure Crypto Income Earners: Compliance Outflows, Global Perspectives to Prevent Singular Risks
Strategy: Some crypto professionals receive their income directly in stablecoins or overseas salaries. In this situation, it is even more important to focus on the compliance and safety of assets.
Efficiency Increase: Split income into three parts: one part compliant with exchange to fiat for basic living and contributions to basic social security/commercial insurance; another part held in stablecoins as liquidity emergency funds; and the core long-term portion regularly invested in crypto blue chips (like Bitcoin) and high-quality global assets, achieving cross-regional and cross-sovereign asset diversification.
For individuals, flexible workers, and crypto pioneers amid the tide of the times, true security never comes from absolute reliance on a single system, but from sovereignty in a diversified defense system.
Through the combination of "basic social security baseline + commercial insurance against black swans + diversified investment appreciation in crypto and traditional assets," we can not only respond to the developmental rules of the era but also calmly face any future fluctuations, firmly grasping the certainty of life in our hands.
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。