For those holding HYPE, there were not many choices in the past.
If optimistic about the market, continue to hold; if needing stablecoins, sell a portion; if wanting to improve capital utilization, transfer assets to other lending protocols, switching back and forth between different accounts and risk systems.
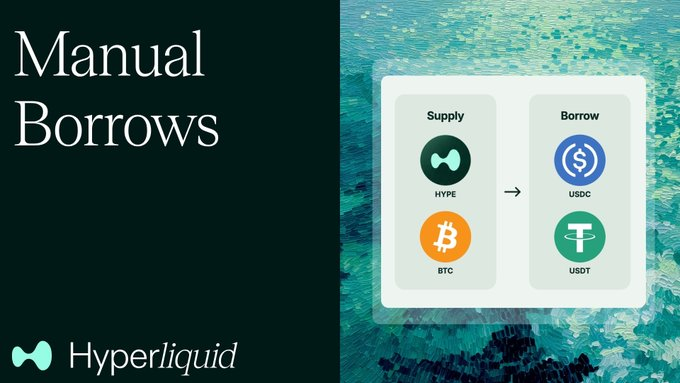
Now, Hyperliquid offers a fourth option: instead of selling HYPE, use it as collateral to directly borrow USDC or USDT.
On September 18, Hyperliquid officially launched manual lending. Users can supply HYPE or BTC as collateral, or supply USDC and USDT to earn lending interest. The official announcement disclosed that the Portfolio Margin, sharing the underlying funds of HyperCore with this function, already had $269 million in assets lent out at that time.
This is not simply a "new financial entry point."
Previously, investing by holding coins solved the question of "how to earn returns on idle funds"; Hyperliquid this time solves "how to obtain liquidity without selling assets."
This is the essence of what is termed "an upgraded version of financial management."
First Level Upgrade: HYPE transitions from holding to callable credit
According to Hyperliquid's official rules, users can pledge HYPE or BTC to borrow USDC or USDT. The loan-to-value ratio (LTV) for HYPE is 65%, while for BTC, it is 50%.
Assuming the price of HYPE is $40, if a user supplies 100 HYPE as collateral, the value of the collateral is $4,000. Based on the 65% LTV, the theoretical borrowing limit would be 2,600 USDC:
100 HYPE × 40 dollars × 65% = 2,600 USDC
This means that users bullish on HYPE do not need to sell their tokens first to obtain liquidity in stablecoins. The borrowed funds can be used for other allocations in the account while maintaining the existing exposure to HYPE.
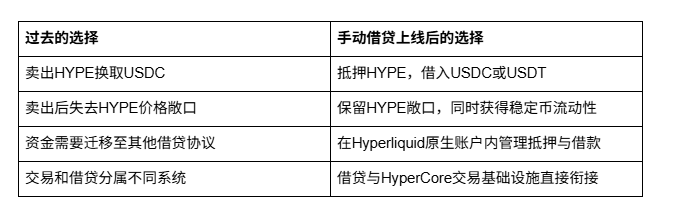
This is the most straightforward value of collateral lending: to transform "holding assets" and "using funds" from a binary choice into simultaneous existence.
However, it must be clarified that pledging HYPE does not automatically generate interest. The official documentation clearly states: the supplied HYPE and BTC are responsible for providing the borrowing limit and do not earn lending income themselves; the actual interest earnings come from USDC and USDT.
Thus, it is not "pledging HYPE to earn effortlessly" but rather that HYPE now has an additional financing purpose.
Second Level Upgrade: Stablecoins do not have to be idle and can act as fund suppliers
If users do not want to borrow money but hold idle USDC or USDT, they can also participate on the other side of the funding pool.
After supplying stablecoins, the funds will be used by borrowers, and suppliers will earn borrowing interest. The yield is not a fixed subsidy from the platform but depends on the utilization rate of the funds.
The official rate formula shows that when the utilization rate of stablecoin funds does not exceed 80%, the base annual borrowing rate is 5%; once it exceeds 80%, borrowing costs will rise rapidly. The protocol retains 10% of the borrowing interest as a future liquidation buffer, and the remaining portion is credited to the income of the fund suppliers based on their share of the supply.
Therefore, the displayed annual yield on the page is not a fixed rate and does not guarantee capital preservation. It depends on how much capital has actually been lent out:
- When borrowing demand rises, the utilization rate increases, and supply income usually rises as well;
- When borrowing demand falls, idle funds increase, and supply income may also decline;
- When liquidity in the funding pool is tight, suppliers may not be able to withdraw all funds immediately.
General "exchange finance" often only provides users with a single yield number; Hyperliquid's native lending directly clarifies the source of income—your interest comes from real financing demand on the other end.
Why is $269 million important? Because demand did not start searching only after the launch
Hyperliquid officials state that manual lending and Portfolio Margin use the same underlying infrastructure of HyperCore, revealing that there were already $269 million worth of assets lent at the time.
On the first day of launch, it established $269 million in loans. More precisely, this figure reflects the borrowing balance of the shared underlying system at that time and does not equate to the manual lending generating an additional $269 million in deposits or loans on the first day.
However, it still demonstrates an important point: Hyperliquid did not launch an empty funding pool and then wait for users to borrow money.
Portfolio Margin has already created real borrowing demand. Manual lending simply opens up this capability originally embedded in the trading system, allowing more users to proactively choose:
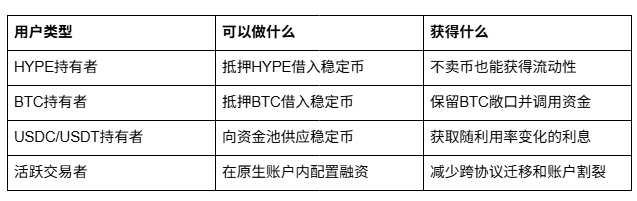
Traditional finance only has the line of "deposit—earn income."
Hyperliquid's upgraded finance forms a closed-loop of "pledge—borrow—lend—trade": Some wish to retain exposure to HYPE and BTC while others are willing to provide stablecoins, with both sides matched through real interest rates.
Third Level Upgrade: Users earn borrowing interest, while the protocol takes the reserve yield from stablecoins
A noteworthy view: after manual lending increases stablecoin deposits, users can earn borrowing interest; more USDC remaining in Hyperliquid may also expand the reserve yield base for AQAv2, thereby supporting more HYPE buybacks and burns.
This can be understood as a two-tier return, but the two tiers do not come from the same income.
The first tier belongs to users. Suppliers of USDC and USDT earn interest from borrowers, with the actual yield varying with the utilization rate of funds.
The second tier belongs to the protocol. AQAv2 requires stablecoin deployers to share about 90% of the adjusted reserve yields generated from their Hyperliquid supply with the protocol. The yield is accumulated over a 30-day period and sent to the Assistance Fund 8 days after the end of the period.
The AQAv2 for USDC has been activated with Coinbase serving as the Treasury Deployer and Circle as the Technical Deployer. Wu disclosed that the income began accumulating on August 26, with the first payment and execution planned for October 3.
The Assistance Fund will use the relevant protocol funds for automatically buying HYPE; the HYPE held by the fund will be permanently removed from circulation according to current rules.
Thus, the complete logic is:
Stablecoin suppliers earn borrowing interest; increased stablecoin deposits may enhance AQAv2 reserve yield; the earnings obtained by the protocol will, through the Assistance Fund, impact HYPE.
This is not users receiving "double interest" nor is it HYPE holders getting fixed dividends. The sources, recipients, and risks of the two income paths are different.
However, it allows Hyperliquid's financial products to add a layer to the simple "deposit for interest": users earn capital income while the protocol seeks long-term returns from stablecoin scale.
What is the real attraction for HYPE holders?
It is not the APY, nor is it about maximizing leverage.
The biggest change is: HYPE now possesses both holding value and collateral value simultaneously.
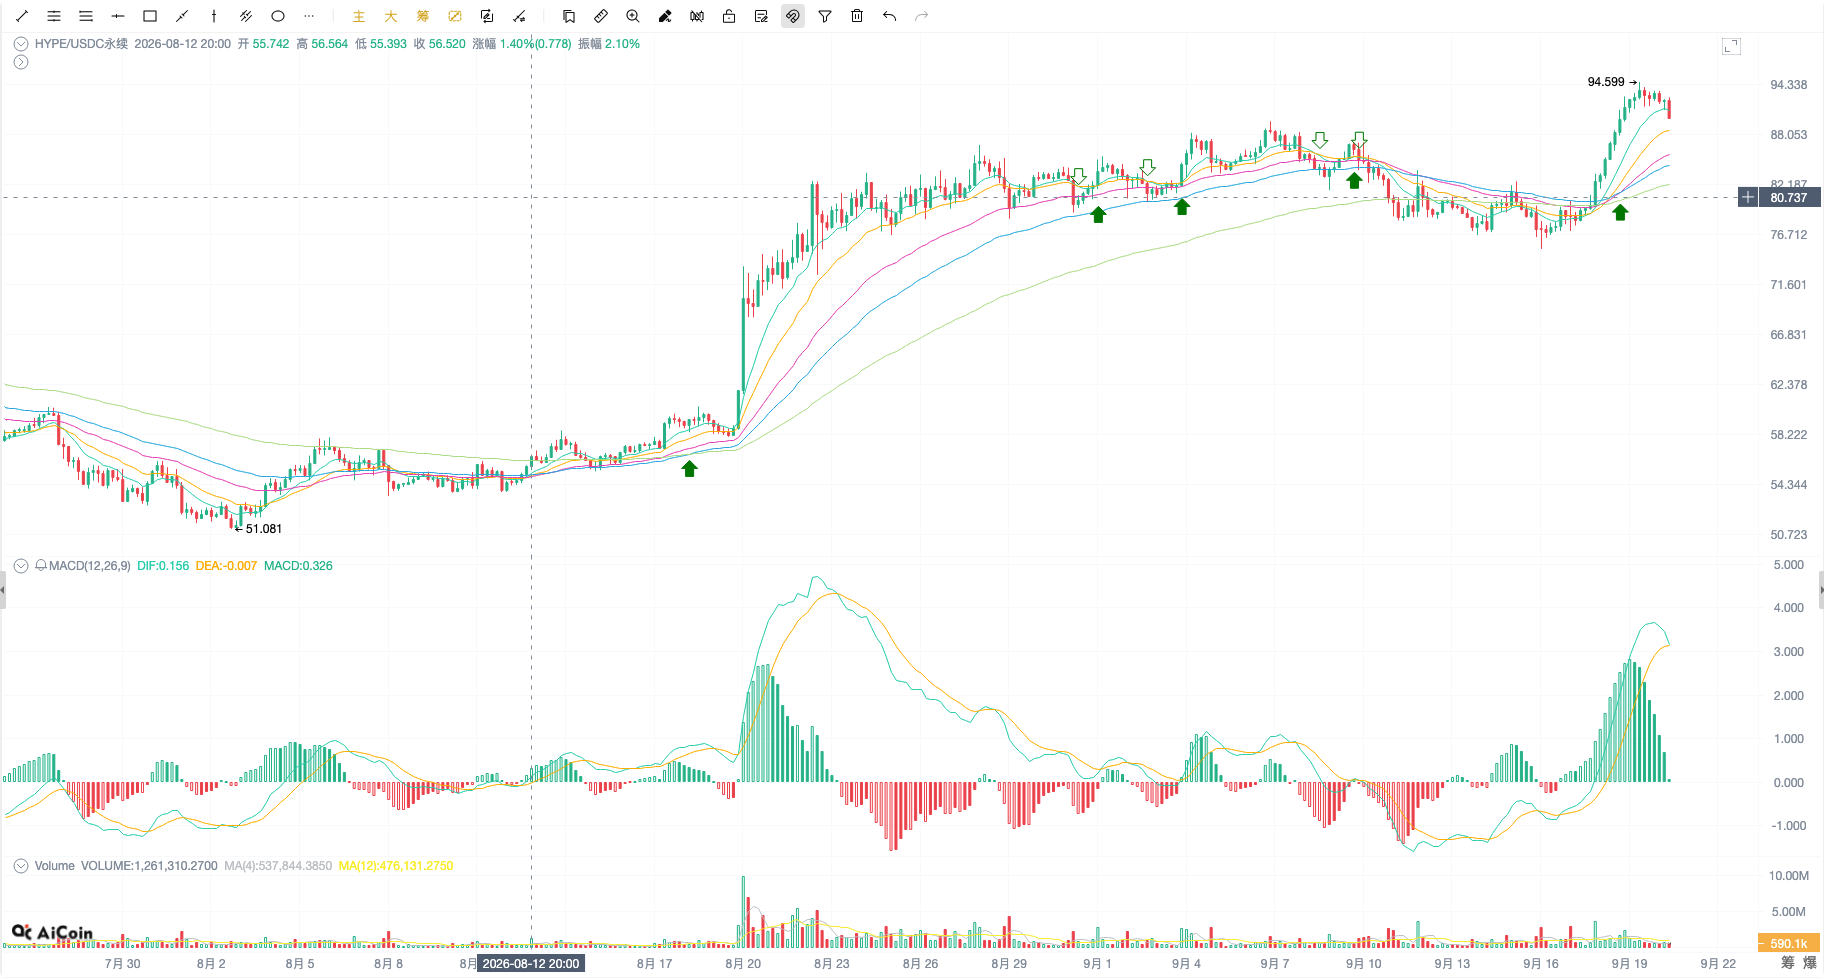
When users need USDC, they no longer have to sell HYPE exclusively. Pledged lending can reduce the need to sell coins in a pinch and provide more flexible capital deployment. For long-term holders, this is more important than any short-term yield increase.
However, "no need to sell" does not mean there are no costs.
Borrowing will continuously accrue interest, and a decline in HYPE will lower collateral value. The official FAQ states that the partial liquidation threshold for HYPE manual lending is 82.5% of the collateral value. Although a health ratio falling below 100% does not immediately trigger liquidation, it indicates that the account can no longer borrow; as the price continues to drop or interest accumulates, the account may enter partial or even complete liquidation.
Taking an example with 100 HYPE, a price of $40, and borrowing 2,000 USDC:
- The initial health ratio is 130%;
- When the price of HYPE is about $30.77, the health ratio drops to 100%, and borrowing cannot continue;
- Ignoring additional interest, when the price of HYPE is about $24.24, it may trigger partial liquidation.
Therefore, the 65% LTV is the maximum borrowing limit permitted by the protocol, not a safety line suggesting users should borrow to the maximum.
Pledged borrowing does not eliminate volatility risk; it transforms "sale risk" into "liability and liquidation risk."
The truly mature usage is not to pursue the highest borrowing limit but to increase liquidity for holdings while maintaining a sufficient safety cushion.
Using AiCoin to observe not just interest rates but also collateral risks
After the launch of manual lending, HYPE holders need to simultaneously monitor three things: whether the collateral price is falling quickly, whether the borrowing interest is continuously accumulating, and whether the borrowed stablecoins are pushing the market leverage up.
Users can first use AiCoin to check the price, trading volume, open interest, and funding rates of HYPE and BTC, and then track the smart money to see if large holders are increasing positions after pledging or actively reducing leverage when the market heats up. When sudden price fluctuations occur, alerts on mobile can help users reassess their risks promptly instead of waiting until liquidation is near.
After confirming the market structure, connect to Hyperliquid through AiCoin to complete transactions and centrally manage different assets and positions on mobile.
AiCoin will not make pledged lending a risk-free financial management option but can help users avoid a common mistake: only seeing "holding coins without selling" but forgetting that they have increased a liability.
Enter Hyperliquid through the exclusive AiCoin portal and use the invitation code AICOIN88 to receive 4% commission rebates according to the activity rules:
Exclusive link: https://app.hyperliquid.xyz/join/AICOIN88
Final Judgment
This time, Hyperliquid's real upgrade is not the lending page but the way of using coin holding finance.
Previously, users had to complete "holding coins," "borrowing money," and "earning interest" across different platforms. Now, HYPE and BTC can directly serve as collateral, USDC and USDT can be funds earning interest, and borrowed stablecoins can connect with Hyperliquid's existing trading system.
This transforms financial management from a passive operation into active capital management:
- If bullish on HYPE but needing liquidity, one can pledge instead of selling immediately;
- Holding idle stablecoins allows earning floating interest on the funding supply side;
- Funds continuing to accumulate in Hyperliquid may expand the protocol's yield base for AQAv2;
- Trading, borrowing, and asset management can now be completed within the same account system.
Regular financial management only allows idle funds to earn income; Hyperliquid's upgraded finance provides liquidity for holdings simultaneously.
The $269 million borrowing balance indicates that this is not a product waiting for demand. However, whether it can form a long-term flywheel remains to be observed regarding borrowing scale, utilization rate, net inflow of stablecoins, actual payments from AQAv2, and collateral performance in extreme market conditions.
For users, the most valuable aspect is not the maximum limit but the added optionality: not having to sell to access funds; not having to borrow to supply funds.
Exclusive Benefits for AiCoin Users
👉 Enter invitation code AICOIN88 when binding a Hyperliquid account for a 4% commission rebate.
🔗 Exclusive registration link:
https://app.hyperliquid.xyz/join/AICOIN88
📖 Beginner's Tutorial:
- "AiCoin PC Hyperliquid Authorization Trading Tutorial":
https://www.aicoin.com/zh-Hans/article/514197
- "AiCoin Mobile Hyperliquid Authorization Trading Tutorial":
https://www.aicoin.com/zh-Hans/article/541383
- "Beginner's Guide! Super Detailed Text and Image Tutorial for First Transaction on Hyperliquid":
https://www.aicoin.com/zh-Hans/article/510225
📖 Community Interaction:
-Telegram:
-Discord:
-AiCoin Group Chat:
https://www.aicoin.com/link/chat?cid=N6OVMor5g
The content of this article represents the author's personal views and does not represent the platform's stance. The views, conclusions, and suggestions in this article are for investor reference only and do not constitute any investment advice related to this platform. Investment in US stocks still requires the investor to bear market risks, regulatory risks, and compliance risks with local laws and regulations (especially foreign exchange controls and overseas investment declaration, etc.).
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。