Alright, the Federal Reserve raised interest rates early this morning. According to the agreement in "A Bet with Walsh for a Bottle of Moutai", let's draw a bottle (Flying Heaven) Moutai. I don't know if it's motivated by the lottery effect (no, today Moutai's stock price rebounded slightly against the trend).
I hope everyone learns from me and doesn't bet against the Federal Reserve lightly.
The rules are as follows:
①Betting subject: This Friday (that is, tomorrow), the closing point of the Shanghai Composite Index, such as 3888.88.
②Betting method: Leave a comment in the comment section (only for readers who have followed for more than 7 days). In addition to the index points, to narrow down the denominator, you need to add a sentence about your investment gains or lessons this year, for example, "3888.88 points, my biggest gain this year was bottom fishing in the dividend sector in June, and I resolutely executed the idea of buying more as it drops." Consider it as me buying some research samples; any nonsensical comments will be excluded (interpretation rights belong to this account), leaving opportunities for earnest friends.
③Time: From the time of this article's release until tomorrow at 8 AM.
④The closest one will win; if there are ties, based on the order of comments, the first to comment wins.
⑤The lottery result will be announced next Monday, at that time just private message me your address, and I will cover the shipping.
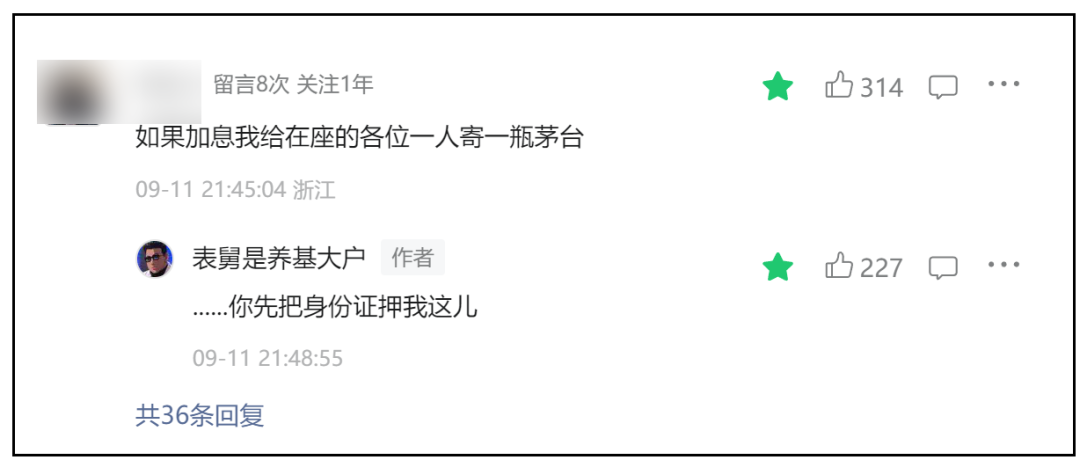
By the way, does what this brother below says still count?
......
Alright, let's return to the market.
The focus is to briefly discuss in order, the outlook for various assets after the rate hike.
1. First, let's look at a chart.
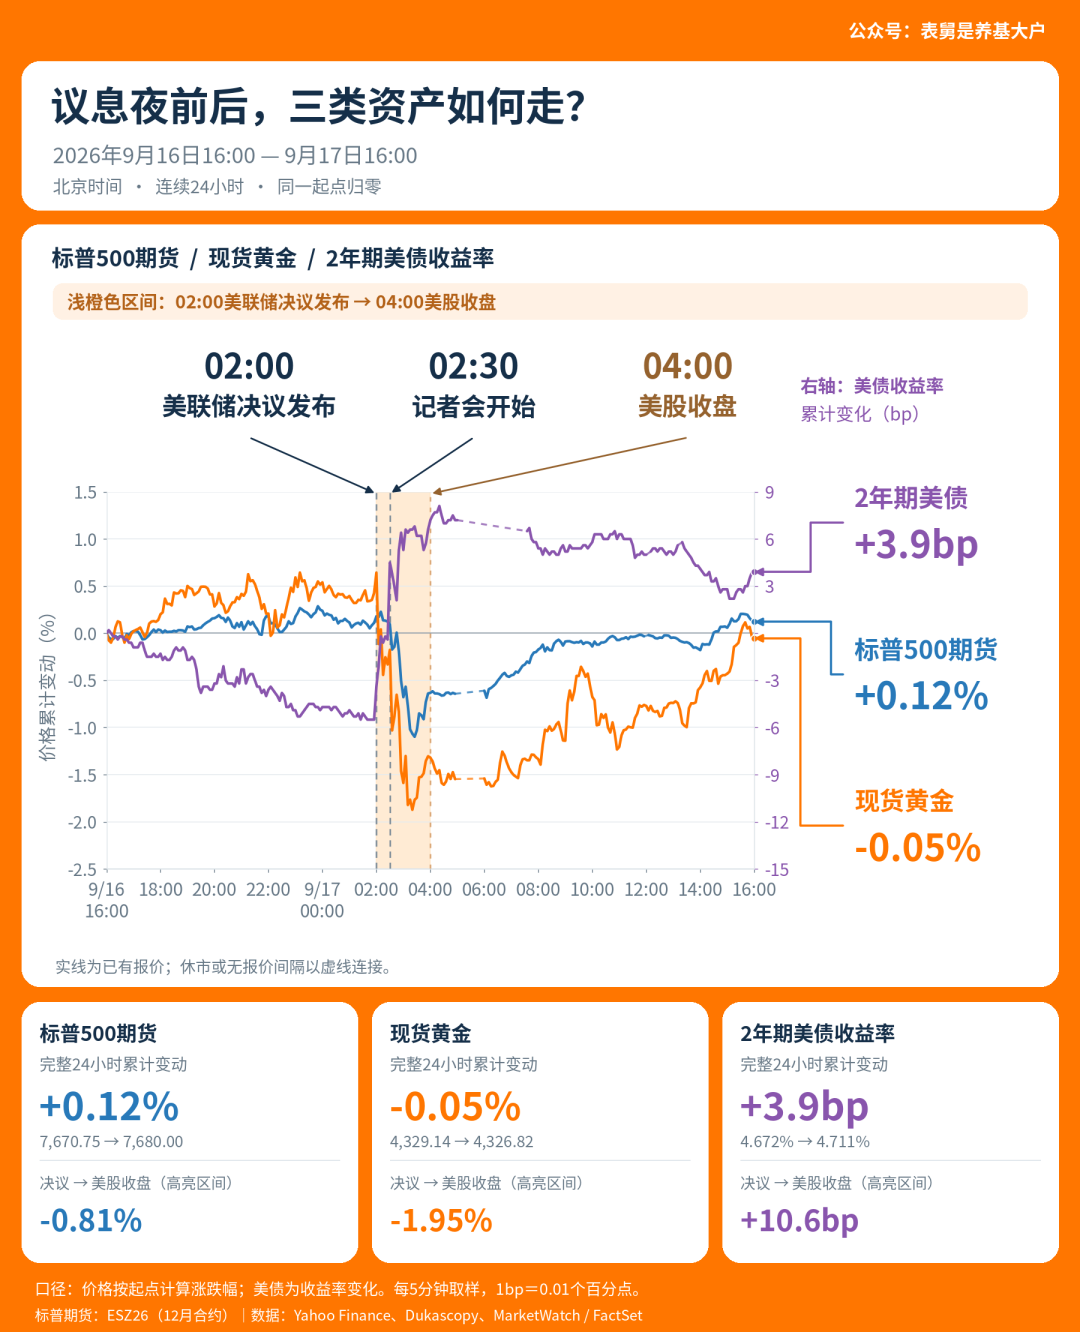
The chart below shows the trend of S&P 500 futures, spot gold, and 2-year U.S. Treasury bonds from 4 PM yesterday to 4 PM today, where I marked two time nodes: when the Federal Reserve announced the interest rate hike and when Walsh started the news conference. The highlighted area is the period from the announcement to just before the close of the U.S. stock market.
From the results, we can see:
After the interest rate decision was announced, combined with the dot plot indicating another hike is expected this year, the 2-year U.S. Treasury bonds rose significantly, gold plummeted, and U.S. stocks also dropped;
However, if we look at the entire range from 4 PM yesterday to 4 PM today, in fact, both U.S. stocks and gold have basically recovered from the earlier plunge, and the stock index futures even closed up.
This means that only the short-end U.S. Treasury rates have genuinely moved up, while other assets, having previously absorbed the rate hike expectations, returned to calm after a short-term shock.
As of tonight, the gains in U.S. stock futures and gold are further expanding.
2. First, let's talk about U.S. Treasuries, considering them in two parts.
For short-term U.S. Treasuries, the current 2-year yield is 4.7%, while the current policy interest rate cap is 4%, which is 70 basis points higher, indicating that pricing has factored in expectations for 2-3 more rate hikes. Frankly, this is already quite an extreme pricing, and I personally still believe that the Federal Reserve will return to a rate-cutting path in the medium term, so short-term U.S. Treasuries are among the most attractive assets globally. This is why more than half of Berkshire's current funds are still held in ultra-short bonds (within 1 year) and cash-like assets such as repurchases.
As for long-term U.S. Treasuries, it's harder to say. It's still a structural issue as mentioned before. This morning, Walsh attributed the rise in long-term bonds to three reasons: "geopolitics (oil prices), AI financing, and economic growth." The last two refer to the same thing because the underlying motivation of this round of economic development in the U.S. comes from the capital expenditures of major tech companies, which drive the development of the upstream and downstream industrial chains. The current long-term rates cannot suppress the bond issuance willingness of tech companies; only when credit spreads and CDS prices rise to levels that tech companies can no longer bear, or when the bond exposure expansion reaches a point where financial institutions can no longer handle it, will this supply slow down. Moreover, Bessen made an honest statement a few days ago during a congressional hearing stating that the core issue with long-term bonds concerns the deficit—hence, whether it’s the deficit or the AI bond supply issue, neither can be resolved by rate hikes; in fact, rate hikes may even worsen the deficit, so there are no signs of relief for long-term rates.
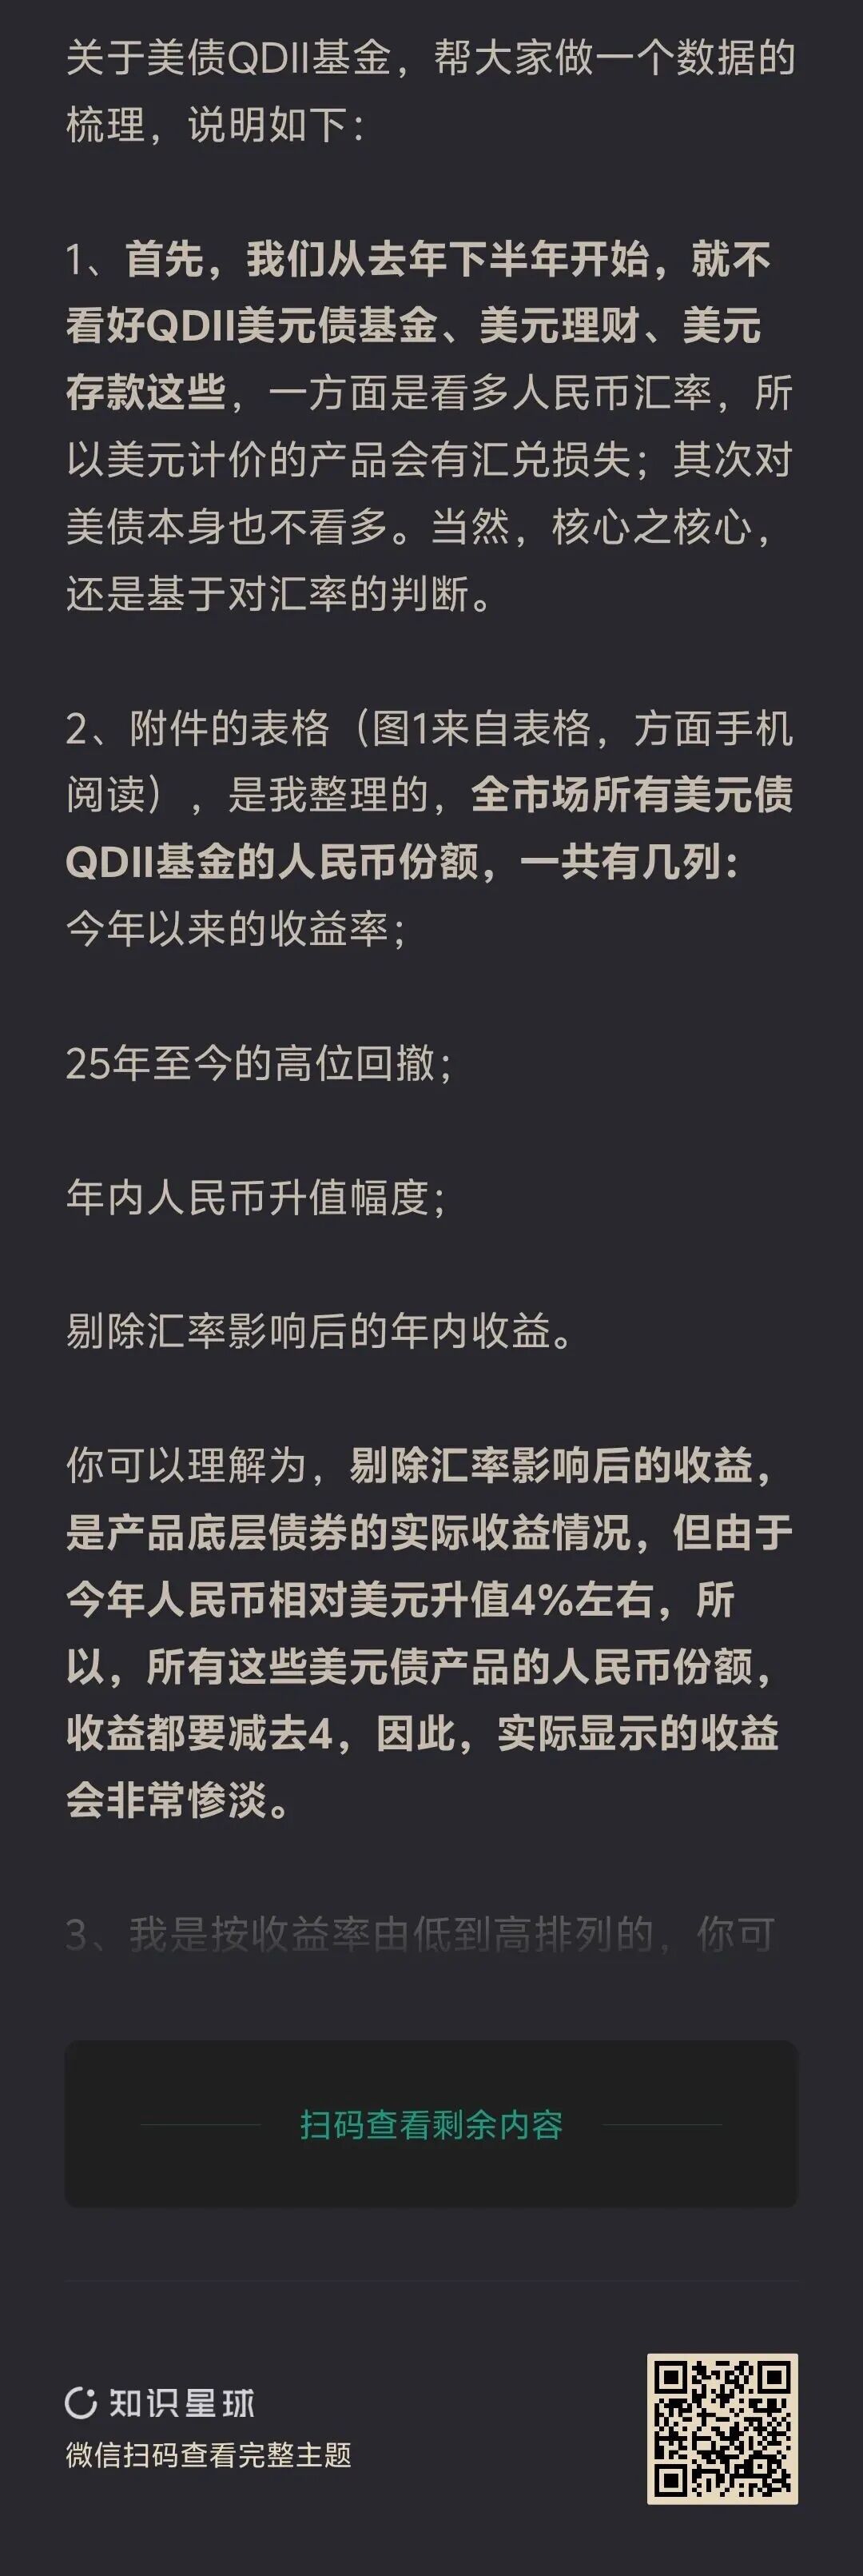
Additionally, short-duration U.S. Treasuries are attractive from the perspective of dollar funding, but from the perspective of RMB funding, currency exchange rates also need to be considered. This is also the reason we have continually been bearish on U.S. dollar bond QDII funds since the second half of last year; refer to the complete analysis in the Star posts (regardless of whether you’ve bought U.S. dollar bond QDII funds, U.S. dollar investments, U.S. dollar deposits, or financial insurance products in Hong Kong, you can take a look).
3. Next, let's discuss U.S. stocks.
The viewpoint has not changed much; the equity risk premium in U.S. stocks is still at historical lows, and the cost-performance ratio of equities is poor. Only when the risk premium rises to a certain level will there be a better position. Therefore, U.S. stocks still primarily offer structured opportunities without a chance for overall valuation uplifts.
To see a turning point in U.S. stock investments, there are three scenarios, as previously mentioned.
First, a trend decline in U.S. Treasury yields leads to a passive increase in risk premiums;
Second, if U.S. stocks remain sideways, but earnings continue to rise significantly in the second half, making the earnings yield increase as well, that would also elevate the risk premium.
Third, a sharp drop in U.S. stocks would also cause an increase in the risk premium.
We need to at least see one of these three.
4. Gold.
This morning, we shared a chart in the Star post, below, and we have repeatedly emphasized that the trend of gold prices is positively correlated with the yield spread of U.S. Treasuries.
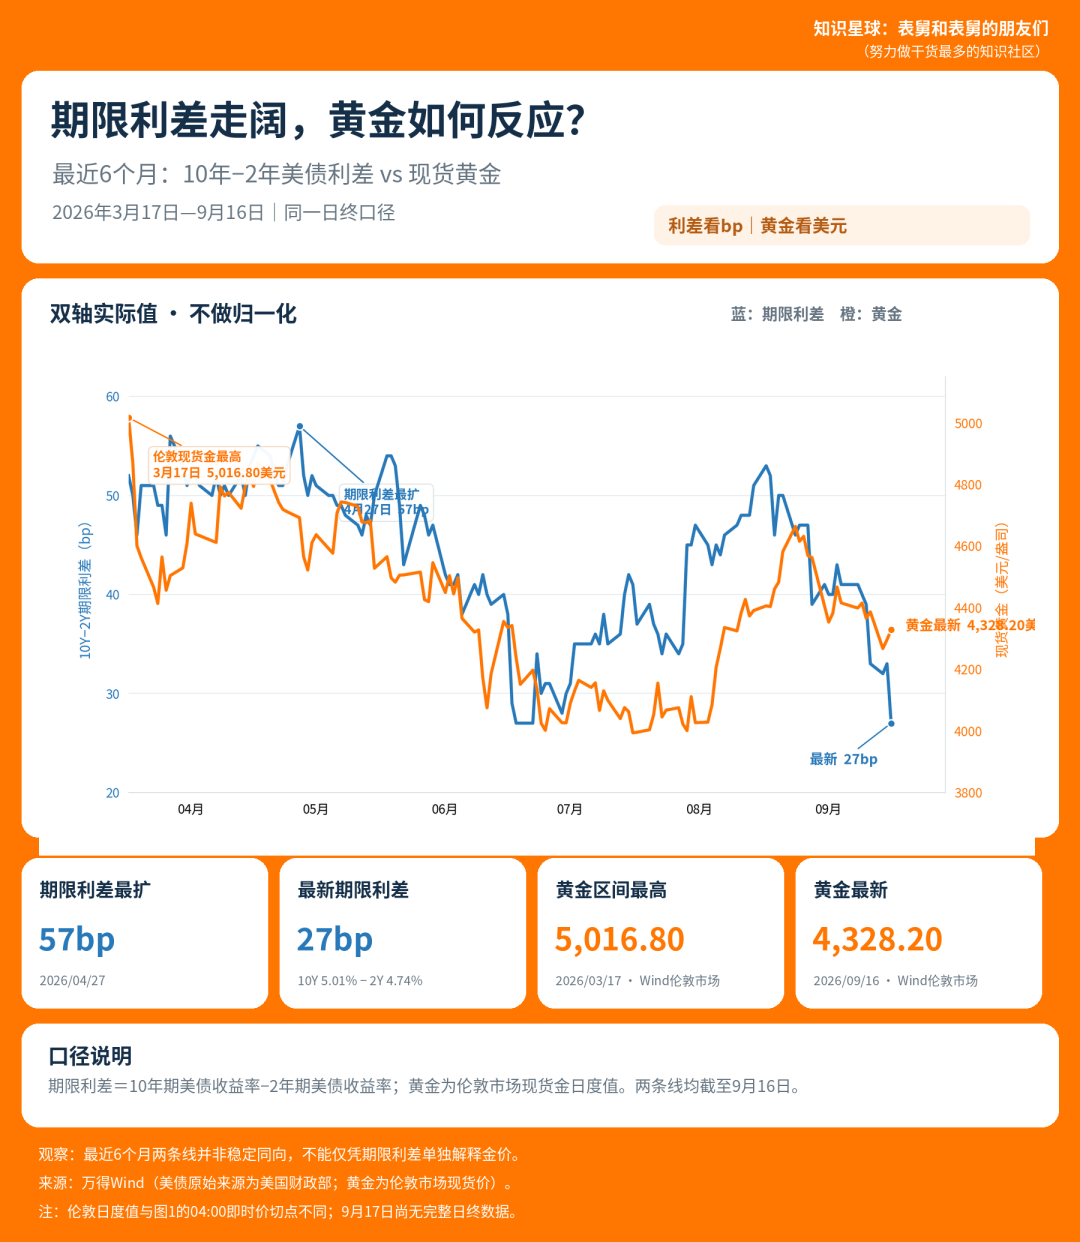
Currently, the yield spread between 10-year and 2-year U.S. Treasuries has narrowed to within 30 basis points, exhibiting a bearish flattening trend, which is the lowest range this year. Therefore, gold is evidently under pressure in the short term, which is also the reason for the leading drop of color metals and gold stocks in today's A-shares.
Of course, the positive side is that it is difficult for the yield spread to continue compressing.
The viewpoint remains the same; gold will be a very key part of a diversified asset portfolio in the second half of the year.
5. Hong Kong stocks.
Rate hikes and high U.S. Treasury yields are negative for Hong Kong stocks.
Continual IPOs and a wave of unlocking are also negative for Hong Kong stocks.
Hence, Hong Kong stocks have only structured opportunities, without any trend opportunities.
6. Chinese bonds.
Low rates, low volatility, no change.
7. RMB exchange rate.
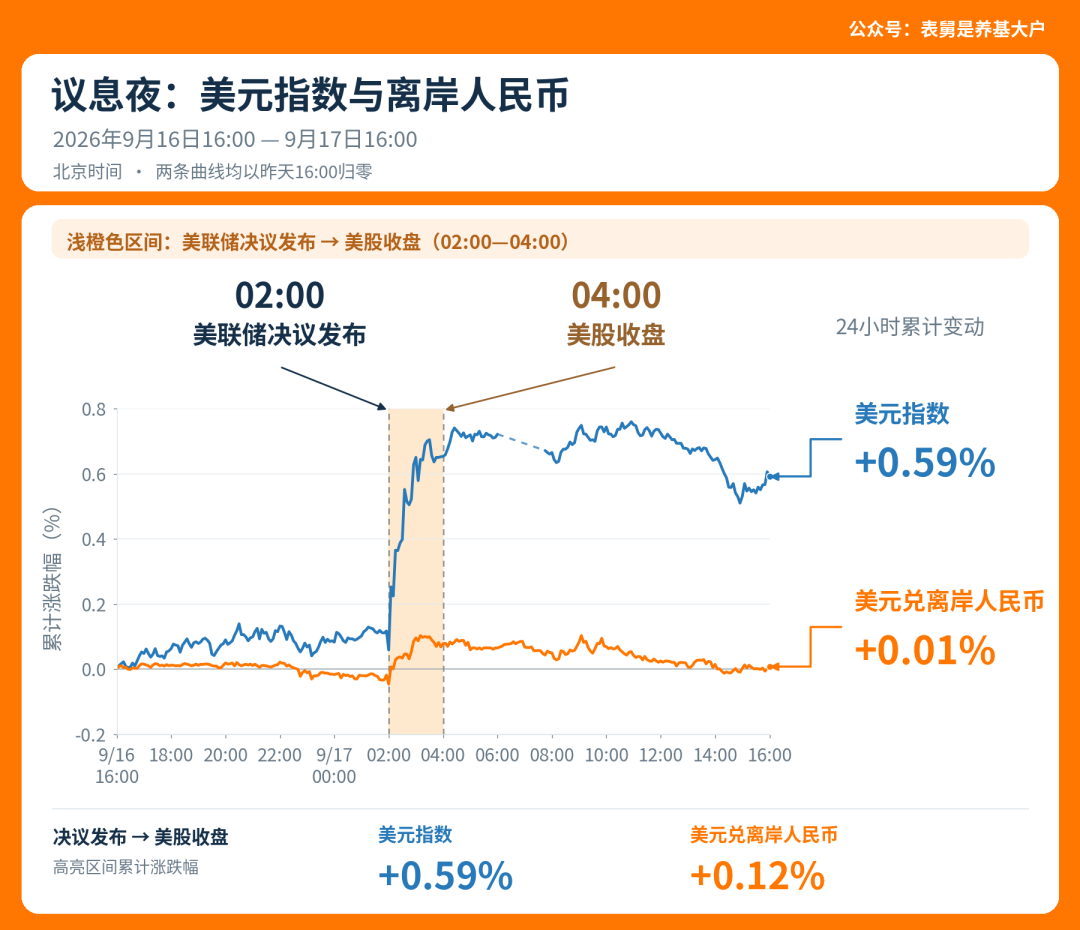
The chart below shows the trends of the U.S. dollar index and offshore RMB exchange rate from 4 PM yesterday to 4 PM today. The dollar has strengthened, but the RMB exchange rate has basically returned to yesterday's level.
We continue to hold a positive outlook for the medium- to long-term trend of the RMB.
8. A-shares.
Why are A-shares placed last?
Because the investment value of A-shares should first look at the strength of the exchange rate and then at the condition of Chinese bonds. If the exchange rate stabilizes, then monetary policy can continue confidently focused on domestic matters, with Chinese bonds maintaining low rates and low volatility. Ultimately, the equity risk premium of A-shares remains unaffected.
Therefore, the viewpoint remains unchanged.
......
免责声明:本文章仅代表作者个人观点,不代表本平台的立场和观点。本文章仅供信息分享,不构成对任何人的任何投资建议。用户与作者之间的任何争议,与本平台无关。如网页中刊载的文章或图片涉及侵权,请提供相关的权利证明和身份证明发送邮件到support@aicoin.com,本平台相关工作人员将会进行核查。


